Stock Analysis · American Water Works (AWK)
Overview
American Water Works is the largest publicly traded water and wastewater utility in the United States. Its core business is straightforward: it owns and operates local systems that treat, transport, and deliver drinking water, and it also collects and treats wastewater. Most of its customers are households, but it also serves commercial clients, industrial users, and public authorities. Because water service is essential and heavily regulated, the company operates in a business that usually produces steady demand rather than fast economic swings.
The company’s revenue is led by its regulated utility operations, where prices are generally set through state-approved rate structures. That matters because earnings growth is often tied less to sales volume and more to approved infrastructure investment and authorized returns. American Water Works also has a smaller market-based arm that serves military bases and offers contracted operations and maintenance services for water systems.
Based on the company’s recent segment reporting, revenue sources are approximately structured as follows:
- Regulated businesses: about 90% to 92% of total revenue. This includes water and wastewater services provided to residential, commercial, industrial, public authority, and other customers across multiple states.
- Military Services Group: about 5% to 7% of total revenue. This business runs water and wastewater systems on U.S. military installations under long-term contracts.
- Market-based businesses: about 2% to 4% of total revenue. This includes contracted operations, maintenance, and other related services for municipal and industrial customers.
Over the last several years, the business mix has remained heavily tilted toward regulated operations, which is generally the most predictable part of the company. Revenue has trended upward overall, and operating income has also expanded, although higher interest expense has become more noticeable as capital spending and borrowing needs have increased.
The broad pattern is favorable for a utility: revenue and operating income have grown over time, and margins remain solid. The main offset is that financing costs are rising, which is important for a company that must keep investing heavily in long-lived infrastructure.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Utilities | |
| Industry | Utilities - Regulated Water | |
| Market Cap ⓘ | $25.80B | |
| Beta ⓘ | 0.58 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 22.30 | 16.80 |
| P/B Ratio ⓘ | 2.18 | 1.48 |
| FCF Yield ⓘ | -3.99% | 0.64% |
| Dividend Yield ⓘ | 2.62% | 3.91% |
| EBIT / EV ⓘ | 4.57% | 5.01% |
| PEG ⓘ | 2.36 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 6.20% | 6.00% |
| RPS Growth (5Y CAGR) ⓘ | 5.11% | 4.14% |
| EPS Growth (5Y CAGR) ⓘ | -13.08% | -11.39% |
| BVPS Growth (5Y CAGR) ⓘ | 8.50% | 4.29% |
| Margin Growth (5Y Trend) ⓘ | 7.21% | 3.55% |
| FCF Growth (5Y CAGR) ⓘ | N/A | -9.10% |
| DPS Growth (5Y CAGR) ⓘ | 8.39% | 4.51% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.62% | 6.53% |
| ROA (Latest) ⓘ | 3.17% | 3.19% |
| ROIC (5Y Median) ⓘ | 6.19% | 6.12% |
| ROA (5Y Median) ⓘ | 3.25% | 2.76% |
| Net Debt / EBIT (Latest) ⓘ | 8.21 | 7.15 |
| Net Debt / EBIT (5Y Median) ⓘ | 7.76 | 7.24 |
| Net Debt / EBITDA (Latest) ⓘ | 5.54 | 4.40 |
| Net Debt / Assets ⓘ | 43.54% | 39.16% |
| EBITDA / Interest ⓘ | 4.41 | 4.41 |
| Operating Margin (Latest) ⓘ | 36.56% | 20.93% |
| Operating Margin (5Y Median) ⓘ | 39.11% | 20.18% |
| Debt to Equity (Latest) ⓘ | 137.69% | 140.88% |
| Profit Margin (Latest) ⓘ | 21.35% | 11.32% |
| Free Cash Flow (Latest) ⓘ | -$1.03B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +12.47% | +48.75% |
| 12M Return (excl. last month) ⓘ | -1.05% | +11.24% |
| 6M Return ⓘ | -3.55% | -3.69% |
| Price vs. 200-Day MA ⓘ | -0.90% | -1.97% |
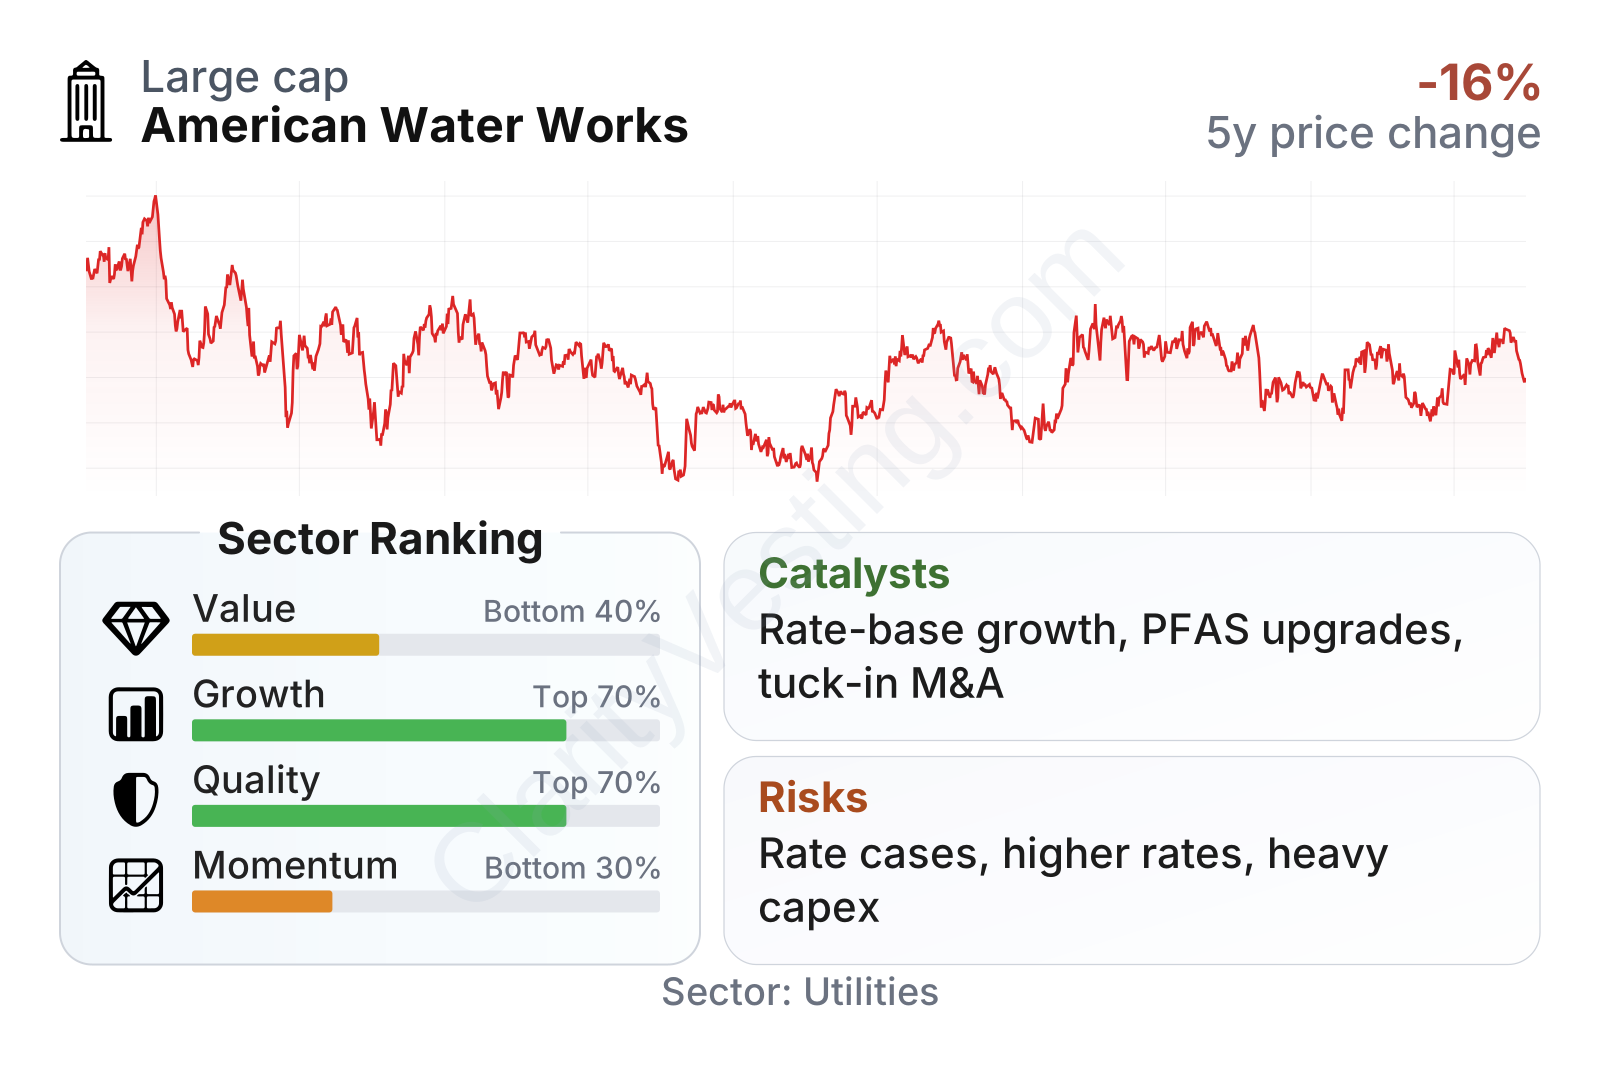
American Water Works is a large utility with relatively low share-price volatility, as shown by its beta of 0.58. Its overall profile is mixed but understandable for the sector: quality ranks well versus peers, growth is slightly above the middle of the pack, momentum is weak, and valuation is not cheap. Profitability stands out positively, while free cash flow remains pressured by heavy capital investment. The stock’s recent trading pattern also shows that the market has treated it more as a defensive name than a strong near-term performer.
Growth
American Water Works operates in a sector with durable long-term demand. Water infrastructure in the United States is old, replacement needs are significant, and local governments often lack the capital or operational scale to address these challenges alone. That creates a supportive backdrop for established regulated operators with engineering, compliance, and financing capabilities. In that context, the company is positioned in a growing niche of the utility sector rather than a mature business with no expansion runway.
The company’s strategy also fits this environment well. Growth mainly comes from three levers: rate-base investment in pipes, treatment plants, and system upgrades; acquisitions of municipal and smaller private systems; and selective contract wins in military and other water-services activities. For a water utility, this is a logical formula because infrastructure spending can support future regulated earnings, while acquisitions can add customers and spread fixed costs across a broader footprint.
Revenue per share has moved upward over the last five years, which points to real business expansion rather than growth driven only by financial engineering. The recent pace is not explosive, but it is steady and broadly consistent with the kind of measured compounding typically seen in regulated infrastructure businesses.
A notable growth support is the company’s multiyear capital plan. American Water Works has continued to emphasize large investment programs to modernize systems, improve resilience, and meet water quality standards. In regulated utilities, that matters because approved capital deployment can translate into a larger rate base and higher future earnings if regulators allow recovery on acceptable terms.
Free cash flow remains negative, which may look unattractive at first glance, but this is common for utilities in heavy buildout phases. The key issue is not whether free cash flow is currently below zero, but whether the spending is productive and recoverable through future rates. For American Water Works, that is the central growth debate: the company is spending today to support a larger regulated asset base tomorrow.
Recent company updates have continued to highlight infrastructure investment, regulated acquisitions, and water quality projects as central priorities. Another potential catalyst is tighter environmental regulation, especially around emerging contaminants, because stricter treatment requirements can increase the need for system upgrades. That can expand investment opportunities for utilities with technical expertise and established regulatory relationships.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


