Stock Analysis · Avantor Inc (AVTR)
Overview
Avantor is a life sciences and advanced technology materials company that supplies products and services used in research labs, biopharma manufacturing, healthcare settings, and a range of industrial applications. In simple terms, it helps customers develop, test, and produce medicines, diagnostics, and high-purity materials. Its catalog spans chemicals, reagents, laboratory consumables, single-use components, cleanroom and safety supplies, equipment, and specialized services such as procurement and production support.
Its business is largely built around repeat purchases rather than one-time big-ticket sales. Customers often need a steady flow of essential materials to keep laboratories and production lines running, which gives the company a relatively recurring revenue base. Avantor operates globally and serves pharmaceutical and biotechnology companies, academic and government laboratories, hospitals, and industrial customers.
Based on company reporting, revenue is primarily organized into two segments.
- Laboratory Solutions: approximately 60% of revenue. This includes reagents, chemicals, consumables, safety products, equipment, and procurement support sold into research, education, healthcare, and general laboratory environments.
- Bioscience Production: approximately 40% of revenue. This segment includes materials and components used in biopharma production, such as single-use assemblies, formulated solutions, excipients, process ingredients, and other products tied to drug manufacturing.
That mix matters for long-term analysis. Laboratory Solutions brings breadth and everyday demand across many end markets, while Bioscience Production offers exposure to higher-value pharmaceutical manufacturing, including biologics and cell and gene therapy workflows.
The longer financial pattern shows a business with solid gross profit generation but more uneven results lower down the income statement. Revenue has softened from earlier peaks, and 2025 stands out as a weak earnings year, even though cash generation has remained positive. That combination suggests the core franchise is still active, but current profitability is under pressure.
Over the past several years, Avantor has maintained a large gross profit pool even as total sales drifted lower from post-pandemic highs. The notable change is that operating profit and net income became much more volatile, which points to weaker volume, cost pressures, and likely charges below the gross profit line rather than a collapse in the company’s basic distribution and supply role.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $10.18B | |
| Beta ⓘ | 0.90 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.06 |
| P/B Ratio ⓘ | 1.81 | 3.08 |
| FCF Yield ⓘ | 4.47% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | -2.19% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 0.50% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | -5.93% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -29.52% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 11.37% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | -17.28% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | -12.45% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -2.99% | 3.29% |
| ROA (Latest) ⓘ | -4.97% | 3.02% |
| ROIC (5Y Median) ⓘ | 8.59% | 4.75% |
| ROA (5Y Median) ⓘ | 4.81% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.08 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 27.06 | 0.99 |
| Net Debt / Assets ⓘ | 29.24% | 5.33% |
| EBITDA / Interest ⓘ | 0.70 | 9.63 |
| Operating Margin (Latest) ⓘ | -4.47% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 13.14% | 7.80% |
| Debt to Equity (Latest) ⓘ | 65.68% | 28.99% |
| Profit Margin (Latest) ⓘ | -8.81% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $454.70M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -27.91% | +37.48% |
| 12M Return (excl. last month) ⓘ | +5.42% | +20.85% |
| 6M Return ⓘ | +93.44% | +9.73% |
| Price vs. 200-Day MA ⓘ | +40.27% | +4.69% |
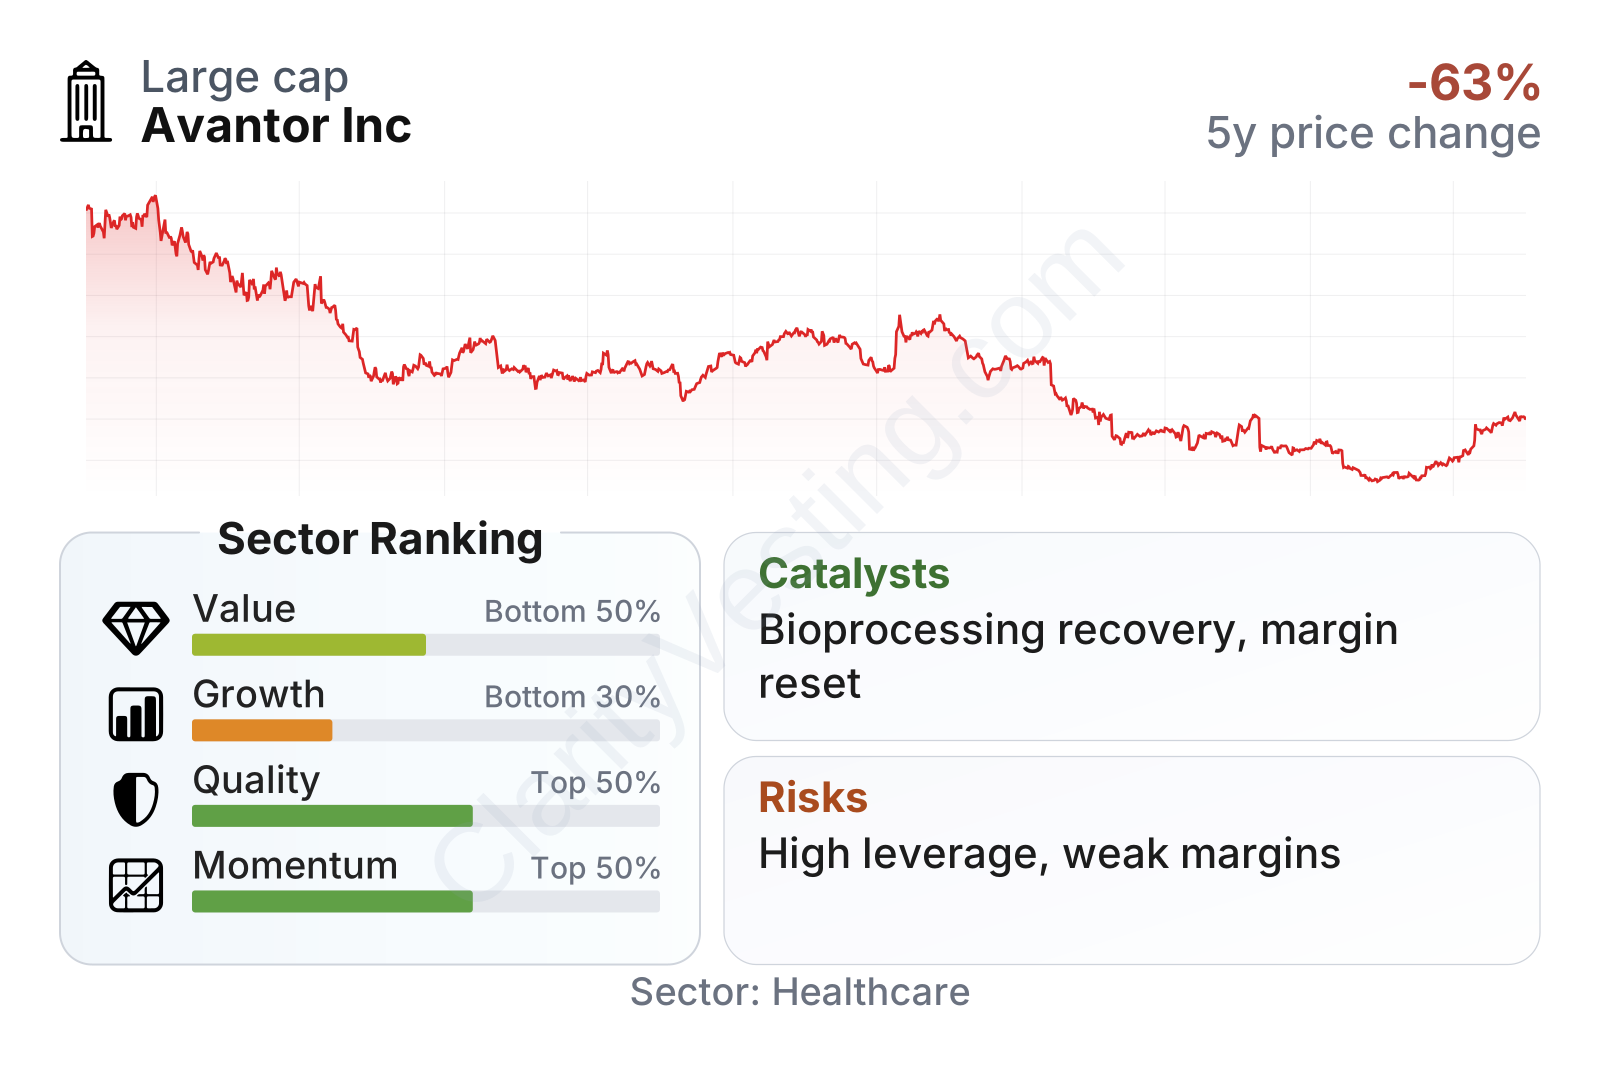
Avantor is a mid-to-large healthcare supplier with a stock that has been far more volatile than its business mix would normally suggest. The recent factor profile is mixed. On one hand, free cash flow yield and book value multiples look less demanding than the sector median. On the other hand, growth ranks weakly versus peers, and recent profitability metrics are distorted by losses and pressure on operating returns. Momentum has improved sharply in the last several months, but that follows a much weaker three-year share-price record.
Growth
Avantor operates in markets that generally benefit from long-term structural demand. Pharmaceutical research, biologics manufacturing, diagnostics, semiconductor-related materials, and high-purity laboratory workflows are all supported by secular trends such as an aging population, rising drug complexity, stricter quality standards, and the continued outsourcing and scaling of scientific production. Those end markets are attractive, even if demand can be uneven from quarter to quarter.
The strategy also makes sense in principle. Avantor is positioned as a critical supplier inside customer workflows rather than as a maker of blockbuster drugs or highly cyclical capital equipment. That role can be valuable because once materials are qualified in regulated processes, customers are often reluctant to switch quickly. The company has also built capabilities across both research and production environments, which can allow it to participate as a customer moves from early-stage work into commercial manufacturing.
The recent growth record is not strong. Revenue growth turned negative through much of 2023, 2024, and 2025, and only recently moved back to roughly flat to slightly positive territory. That suggests Avantor is still in a recovery phase rather than a clear expansion phase. Relative to the broader healthcare sector, the current pace remains modest.
Cash generation tells a somewhat better story than revenue growth. Free cash flow has declined from earlier levels, but it remains positive at several hundred million dollars on a trailing basis. That matters because it gives the company room to keep reducing debt, support operations, and absorb a period of slower demand without needing a dramatic change in its business model.
A major catalyst is any normalization in bioprocessing demand. During and after the pandemic, many suppliers to life sciences experienced inventory swings, delayed customer orders, and project timing disruptions. If biopharma production volumes, lab spending, and customer restocking continue to stabilize, Avantor could see an improvement in organic growth and operating leverage. Another important catalyst is internal execution: restructuring, portfolio simplification, and productivity programs can help restore margins even before revenue fully rebounds.
Recent company communications have also emphasized a sharpened focus on higher-value, workflow-critical categories and on disciplined cost actions. For a company like Avantor, that is meaningful because even a modest improvement in volume can have an outsized effect if the expense base is better aligned.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


