Stock Analysis · Avient Corp (AVNT)
Overview
Avient Corp is a specialty materials company that develops and sells customized polymer formulations, colorants, additives, and engineered materials. In simpler terms, it helps manufacturers improve plastics and related materials so products can become lighter, more durable, more attractive, more recyclable, flame resistant, or better suited for medical, packaging, consumer, transportation, and industrial uses. The company operates globally and serves customers that often need material performance tailored to strict technical and regulatory requirements.
Its revenue mainly comes from two operating segments reported in recent company filings:
- Color, Additives and Inks — about 59% of 2025 revenue: color concentrates, performance additives, specialty inks, and polymer-based solutions used in packaging, consumer products, healthcare, and industrial applications.
- Specialty Engineered Materials — about 41% of 2025 revenue: formulated compounds and engineered polymer materials designed for higher-performance applications in areas such as mobility, electrical, consumer, and industrial markets.
Geographically, Avient is diversified across North America, Europe, Asia, and Latin America, which reduces reliance on one single economy, although demand still tends to move with industrial production and manufacturing activity. The business model is less about commodity chemicals and more about formulation know-how, customer relationships, and application-specific materials, which usually supports better pricing than basic resin producers.
Over the last several years, the company’s sales base has been fairly stable around the low-$3 billion range, but profitability has been more uneven. Gross profit improved noticeably in 2024 and remained comparatively solid in 2025, while net income stayed more volatile because interest costs, restructuring items, and other below-operating-line factors had a meaningful effect.
The revenue mix has been relatively steady, but the more important shift has been margin recovery at the operating level after a weaker 2022-2023 period. That is encouraging, although the gap between operating income and net income shows that financing and other non-operating costs still matter a lot for Avient.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $3.70B | |
| Beta ⓘ | 1.29 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 21.81 | 16.92 |
| P/B Ratio ⓘ | 1.55 | 1.66 |
| FCF Yield ⓘ | 1.47% | 5.83% |
| Dividend Yield ⓘ | 2.77% | 2.07% |
| EBIT / EV ⓘ | 5.94% | 6.38% |
| PEG ⓘ | 1.22 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.80% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -0.34% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -12.48% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 7.74% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 2.72% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 10.00% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 6.28% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.33% | 9.59% |
| ROA (Latest) ⓘ | 2.85% | 4.92% |
| ROIC (5Y Median) ⓘ | 5.76% | 7.91% |
| ROA (5Y Median) ⓘ | 2.76% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 4.67 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.86 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 2.89 | 0.93 |
| Net Debt / Assets ⓘ | 24.15% | 13.69% |
| EBITDA / Interest ⓘ | 5.00 | 12.38 |
| Operating Margin (Latest) ⓘ | 9.33% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 8.41% | 11.82% |
| Debt to Equity (Latest) ⓘ | 76.97% | 40.30% |
| Profit Margin (Latest) ⓘ | 5.10% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $54.50M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +38.06% | +73.47% |
| 12M Return (excl. last month) ⓘ | +18.69% | +27.59% |
| 6M Return ⓘ | +8.37% | -4.02% |
| Price vs. 200-Day MA ⓘ | +7.72% | -0.65% |
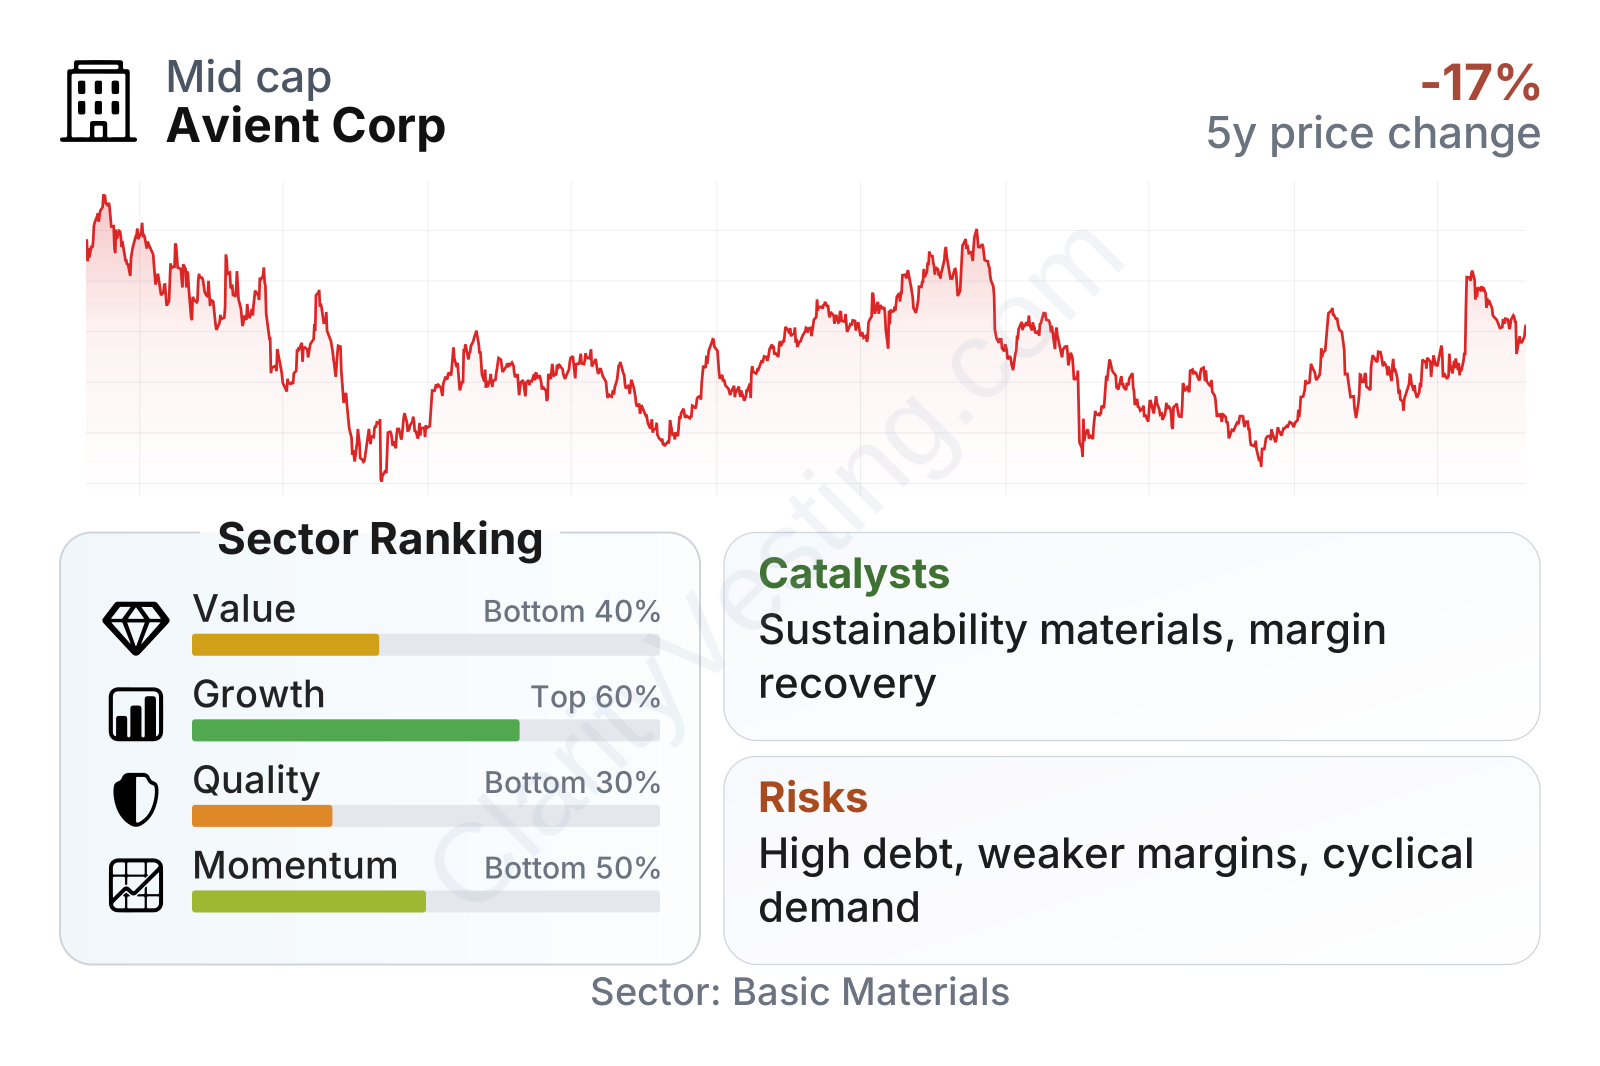
Avient is a mid-sized specialty chemicals company with above-average share price volatility, as shown by a beta modestly above 1. On valuation, it screens as somewhat mixed: the earnings multiple is above the sector median, while price-to-book is slightly lower than the sector median. The broader picture is less favorable on cash generation, because free cash flow yield is well below the sector median.
The factor breakdown also shows a split profile. Growth measures are around the middle of the sector, helped by improving margins, free cash flow expansion over five years, and steady dividend growth. Quality is weaker: returns on capital and assets are below sector norms, and leverage remains elevated. Momentum is neither particularly strong nor particularly weak over longer periods, though the shorter-term trend has improved.
Growth
Avient operates in a part of the chemical industry that has better long-term characteristics than basic commodity chemicals. Specialty materials benefit from several durable themes: lightweighting in vehicles, tighter product-performance standards, replacement of traditional materials by advanced polymers, medical and consumer product innovation, and demand for more recyclable or lower-impact packaging solutions. These are not explosive growth markets every year, but they can support steady expansion when the company is positioned in technically demanding niches.
Management’s strategy also makes sense in that context. Avient has spent years shifting toward higher-value formulations and away from lower-margin activities. That approach can support stronger margins and stickier customer relationships, because customers usually qualify these materials into their products and then rely on consistency, regulatory compliance, and technical support. In this industry, that kind of embedded relationship can be more valuable than simple scale alone.
Recent sales trends suggest a business that is recovering rather than accelerating dramatically. Revenue growth turned back positive through 2024 and stayed positive into the first half of 2026, with the latest year-over-year pace running in the mid-single digits. That is an improvement from the declines seen in 2022 and 2023, but it still points more to gradual normalization than to a breakout growth phase.
Cash generation has also rebounded from a weak 2024 level. Over a five-year view, free cash flow has improved meaningfully, and that matters because Avient’s investment case depends heavily on turning specialty-materials positioning into dependable cash, not just accounting earnings. Better cash flow gives the company more room to reduce debt, maintain dividends, and support selective investment in product development and portfolio upgrades.
One potential catalyst is Avient’s exposure to sustainability-linked materials, including solutions that help customers reduce material use, improve recyclability, or replace less attractive legacy materials. Another is the company’s strong presence in color and additive systems, where product customization can create repeat business. Recent company communications have also highlighted ongoing productivity actions and commercial discipline, which could support margin resilience if volumes continue improving.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


