Stock Analysis · ArriVent BioPharma Inc (AVBP)
Overview
ArriVent BioPharma is a clinical-stage biotechnology company focused on developing cancer medicines. Its lead program is firmonertinib, an oral treatment candidate for non-small cell lung cancer with certain EGFR mutations. The company is built around in-licensing promising therapies, running global clinical development, and trying to bring those medicines through late-stage trials toward potential regulatory approval.
At this stage, ArriVent is not yet a commercial company. Based on recent SEC filings, it has not reported product revenue, so its business remains centered on research and development rather than sales. That makes it different from established drugmakers: the investment case depends much more on clinical progress, regulatory outcomes, and future commercialization potential than on current income.
Main sources of revenue are currently very limited.
- Product revenue: 0% at present. The company has not reported recurring commercial sales because none of its drug candidates has reached full commercialization.
- Collaboration or licensing revenue: no meaningful recurring contribution disclosed recently.
- Interest and other income: effectively the only visible income stream today, driven by cash and investments held on the balance sheet rather than by operations.
The clearest operating pattern so far is rising spending on development. Research and development expense has expanded sharply over the last few years as ArriVent advances trials, while revenue has stayed at zero. That is typical for a biotech at this stage, but it also means the company’s value is tied to whether its pipeline can eventually convert clinical progress into approvals and commercial sales.
The operating flow shows a company still in heavy build-out mode: no revenue yet, steadily higher research spending, and widening losses as the lead program moves forward.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.49B | |
| Beta ⓘ | 1.36 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 25.42 |
| P/B Ratio ⓘ | 3.75 | 3.08 |
| FCF Yield ⓘ | -9.91% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | -15.73% | 0.56% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | N/A | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -29.48% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -42.13% | 3.17% |
| ROA (Latest) ⓘ | -45.40% | 2.98% |
| ROIC (5Y Median) ⓘ | N/A | 4.56% |
| ROA (5Y Median) ⓘ | -38.42% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | -39.10% | 5.06% |
| EBITDA / Interest ⓘ | N/A | 9.55 |
| Operating Margin (Latest) ⓘ | N/A | 9.25% |
| Operating Margin (5Y Median) ⓘ | N/A | 7.33% |
| Debt to Equity (Latest) ⓘ | 0.10% | 26.68% |
| Profit Margin (Latest) ⓘ | N/A | 3.34% |
| Free Cash Flow (Latest) ⓘ | -$147.93M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +51.61% |
| 12M Return (excl. last month) ⓘ | +57.69% | +19.90% |
| 6M Return ⓘ | +19.45% | +10.10% |
| Price vs. 200-Day MA ⓘ | +5.96% | +6.44% |
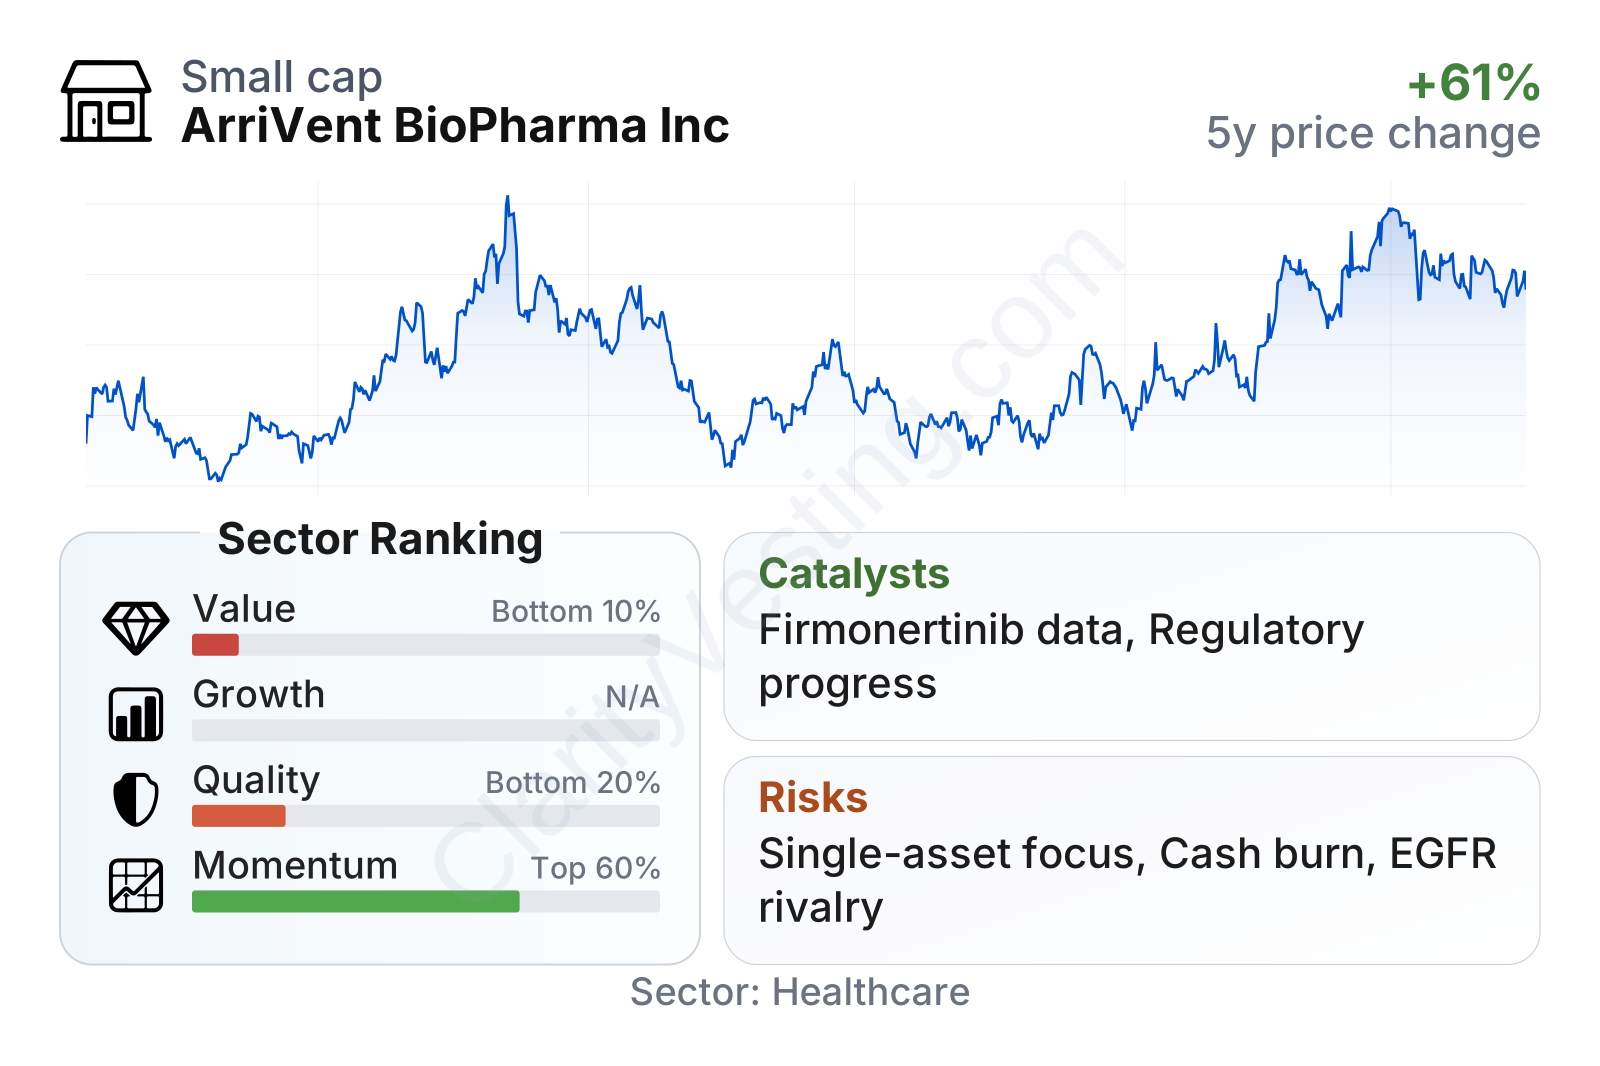
ArriVent is a mid-sized biotech by market value, with a share price that has been volatile but generally stronger than much of the healthcare sector over the past year. That market strength reflects rising expectations around the pipeline rather than operating profits. On traditional valuation and profitability measures, the company ranks weakly versus the sector, which is normal for a clinical-stage biotech but still important to recognize. The balance sheet stands out in a more favorable way: debt is close to zero, leaving the company far less leveraged than the typical peer.
Growth
ArriVent operates in one of the most active parts of healthcare: targeted oncology. Lung cancer remains a very large market, and EGFR-mutated non-small cell lung cancer is already an established segment for precision medicines. That matters because the company is not trying to create demand from scratch. It is pursuing a patient population where testing is already common, physicians are familiar with targeted drugs, and regulators have approved multiple products before. If ArriVent can show meaningful clinical differentiation, the commercial opportunity could be significant.
The company’s strategy is also fairly logical for a smaller biotech. Instead of building a broad discovery engine from the ground up, ArriVent has focused on acquiring rights to promising molecules and pushing them through global development. The lead asset, firmonertinib, is central here. Management has been positioning it for patients with uncommon EGFR mutations, an area where treatment options are more limited and where strong data can carry strategic value. In oncology, success in a narrower setting can later open the door to expansion into larger patient groups.
Recent company updates have kept attention on clinical execution, especially the progress of late-stage studies and regulatory interactions around firmonertinib. For a company with no product revenue, these are the main catalysts that can reshape perceptions of future sales potential. Positive trial readouts, clearer timelines for regulatory submissions, or broader development plans would likely matter much more than short-term accounting results.
Cash generation remains negative and has been moving further down as trial activity scales up. That is expected for a development-stage biotech, but it also shows how much future value depends on turning research spending into clinically and commercially meaningful outcomes.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


