Stock Analysis · Perenti Global Limited (AUSDF)
Overview
Perenti Global Limited is an Australian mining services group. Rather than primarily owning mines itself, the company helps mining customers plan, build, operate, and support mining projects. Its activities include underground and surface mining, drilling, mining support, equipment-related services, and technology-enabled services used on mine sites. This makes Perenti more of a contractor and service provider to the mining industry than a traditional metals producer.
The business is spread across several operating brands, with underground mining through Barminco being one of the best-known parts of the group. Perenti works with gold and base-metals miners across Australia, Africa, and other selected markets. That geographic reach matters because it reduces reliance on a single mine, customer, or commodity, although gold remains a major end-market.
Based on the company’s latest annual disclosures, revenue is mainly generated from mining services contracts. A simple way to think about the business mix is:
- Contract mining services: approximately 75% to 85% of revenue. This includes underground and surface mining work where Perenti supplies labor, equipment, and operational expertise to run parts of a customer’s mine.
- Drilling services: approximately 10% to 20% of revenue. This covers exploration, grade control, production, and other drilling activities through the group’s drilling operations.
- Mining support, technology, and other services: approximately 5% to 10% of revenue. This includes mine support activities, equipment-related services, and technology solutions that aim to improve productivity and safety.
That structure gives Perenti a practical role in the mining value chain: customers outsource difficult, capital-intensive operating work, while Perenti earns revenue from multi-year contracts and site-based service activity.
The long-term direction of the business has been positive on the revenue side, with sales rising from about A$2.4 billion in fiscal 2022 to about A$3.5 billion in fiscal 2025 before easing slightly in fiscal 2026. Operating income improved materially over that earlier expansion period, but the latest year also shows how contract mining remains a lower-margin business where cost mix and project execution can meaningfully affect reported profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $1.68B | |
| Beta ⓘ | 0.30 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 30.00 | 16.90 |
| P/B Ratio ⓘ | 0.98 | 1.65 |
| FCF Yield ⓘ | 17.55% | 5.76% |
| Dividend Yield ⓘ | 4.33% | 2.13% |
| EBIT / EV ⓘ | N/A | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -1.90% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 0.23% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -0.92% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 2.20% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 32.76% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 6.29% | 4.91% |
| ROIC (5Y Median) ⓘ | 6.09% | 7.70% |
| ROA (5Y Median) ⓘ | 3.09% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.63 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.22 | 0.95 |
| Net Debt / Assets ⓘ | 7.76% | 13.69% |
| EBITDA / Interest ⓘ | 8.12 | 12.34 |
| Operating Margin (Latest) ⓘ | N/A | 13.20% |
| Operating Margin (5Y Median) ⓘ | 7.38% | 11.80% |
| Debt to Equity (Latest) ⓘ | 32.28% | 40.56% |
| Profit Margin (Latest) ⓘ | 0.56% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $294.74M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +204.62% | +68.89% |
| 12M Return (excl. last month) ⓘ | +35.38% | +30.21% |
| 6M Return ⓘ | +23.29% | -4.16% |
| Price vs. 200-Day MA ⓘ | +22.69% | -1.27% |
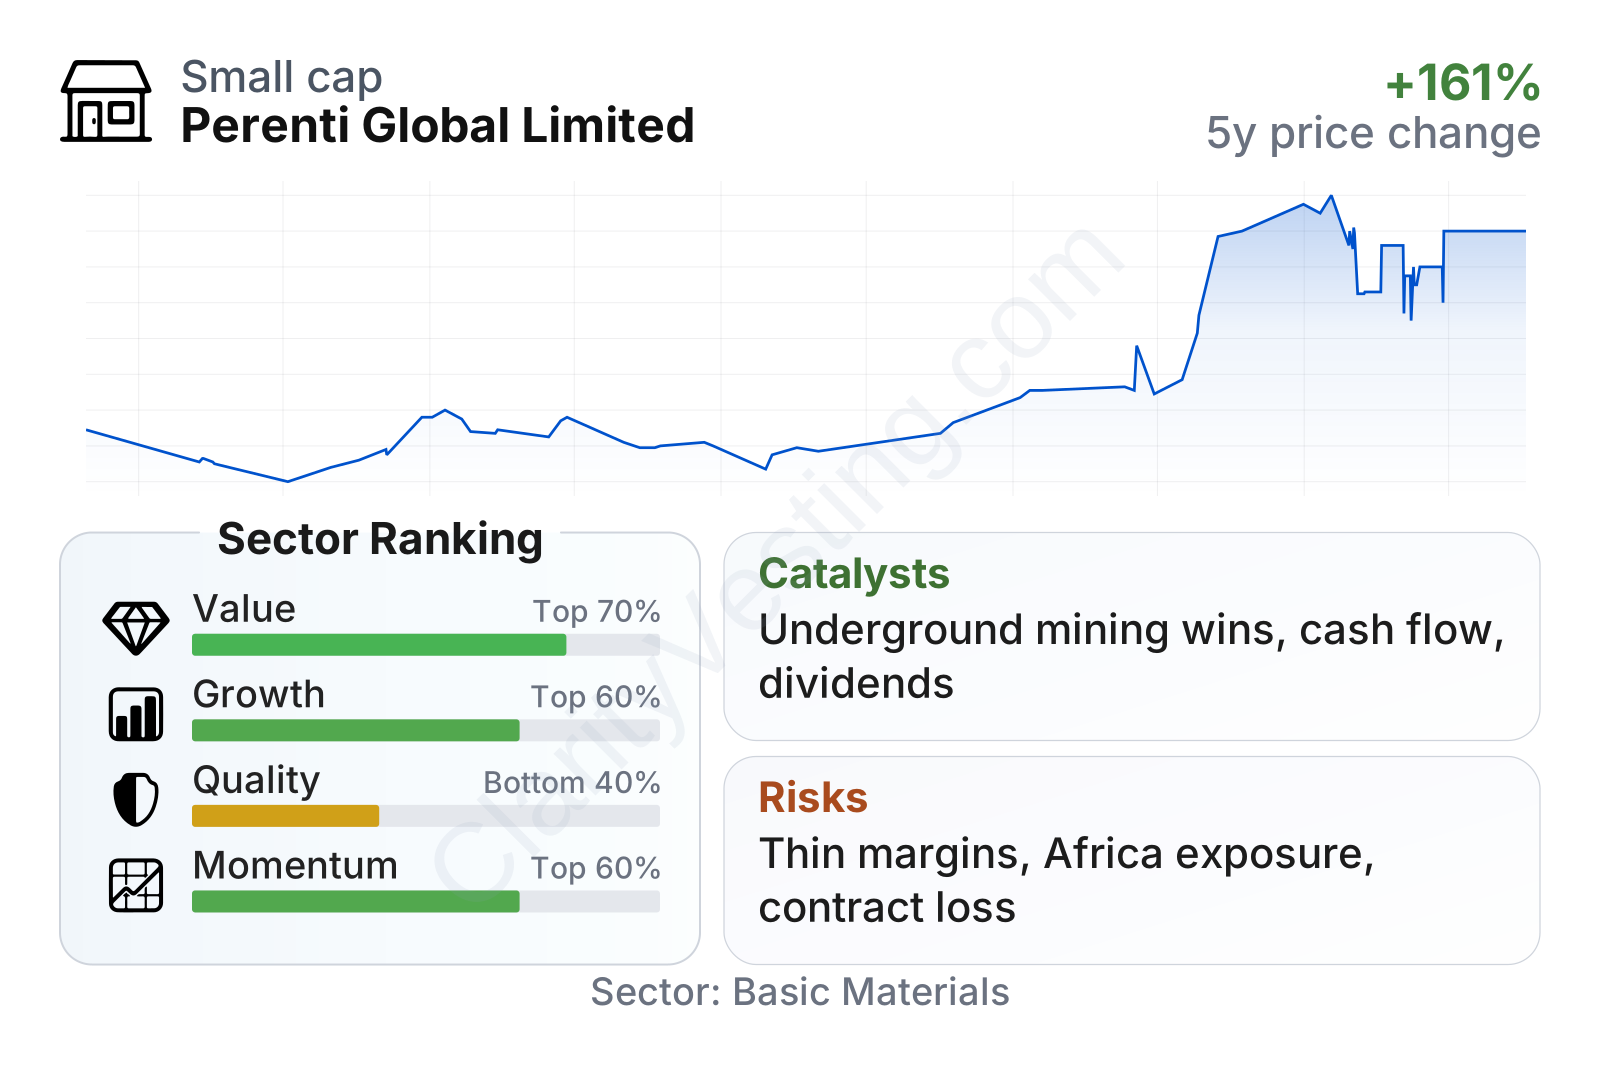
Perenti is a mid-sized mining services company with a relatively low beta of about 0.32, which suggests the shares have been less volatile than the broader equity market. The stock has also been strong over time, with a roughly tripled share price over three years and solid gains over the last six to twelve months.
On valuation, the picture is mixed. The earnings multiple sits above the sector median, which can make the shares look expensive at first glance. But the price-to-book ratio is below the sector median, free cash flow yield is far above the sector median, and the dividend yield is also notably higher than many peers. That usually points to a business where accounting earnings understate some of the cash generation, or where the market is still applying caution because of cyclicality, contract risk, and margin pressure.
Financial strength looks respectable. Net debt relative to EBITDA is low, debt to equity is moderate at roughly 32%, and free cash flow is strong in absolute terms. Profitability is more uneven: return on assets is decent, but net margin is thin and operating margins remain below sector norms. In other words, the balance sheet looks healthier than the margin profile.
Growth
Perenti operates in a sector with durable long-term relevance. Mines need contractors with equipment, skilled labor, underground expertise, and drilling capacity, especially as ore bodies become harder to access and mine plans become more complex. Gold and copper in particular support demand for mining contractors: gold because it remains heavily mined in Perenti’s core regions, and copper because electrification, grid expansion, and energy-transition infrastructure all require more supply.
The company’s strategy also makes industrial sense. Mining companies often prefer specialized contractors for underground development, production, and drilling because building those capabilities internally takes time, capital, and operational depth. Perenti’s model allows customers to outsource execution while focusing on resource ownership and project economics. For Perenti, that can support recurring work, contract renewals, and cross-selling across mining, drilling, and support services.
A key growth point is its position in underground mining, a technically demanding niche with higher barriers to entry than simpler site services. If mine development activity remains healthy, this part of the business can support revenue visibility better than many shorter-cycle mining services lines. The company has also highlighted technology, productivity improvement, and service integration as tools to deepen customer relationships rather than relying only on fleet expansion.
Recent operating momentum appears more solid than reported top-line growth alone suggests. While the latest year showed a slight revenue decline of about 2% year over year, the longer trend in cash generation, dividends, and share-price performance indicates the market has responded positively to improved execution, lower leverage, and stronger capital discipline. Dividend growth over five years has been especially strong, even if that pace is unlikely to continue indefinitely.
Another practical catalyst is contract visibility. In mining services, a meaningful new project award, contract extension, or mobilization in a core region can move earnings expectations more than small commodity price changes. Perenti’s scale and established presence in Australia and Africa make it well positioned to compete for those opportunities, especially in underground and drilling work where customer switching can be disruptive.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


