Stock Analysis · AngloGold Ashanti plc (AU)
Overview
AngloGold Ashanti plc is one of the world’s largest gold mining companies. It explores for gold, develops mines, extracts ore, processes it, and sells refined gold. The company operates across several regions, with producing assets in Africa, Australia, and the Americas. In addition to gold mining, it also has smaller by-product exposure from metals that can be recovered alongside gold at some operations, but gold is overwhelmingly the core business.
For a long-term reader, this is important because AngloGold Ashanti is not a diversified industrial group. Its results are driven mainly by three things: how much gold it produces, what it costs to mine each ounce, and the market price of gold.
The company’s revenue mix is relatively straightforward. Based on company reporting, the business is heavily concentrated in gold sales, with the remainder coming from by-products and other mining-related items.
- Gold sales: approximately 95% to 98% of revenue. This is the sale of mined and processed gold from the company’s operating mines.
- By-product revenue and other sales: approximately 2% to 5% of revenue. This can include silver and other associated metals, depending on the mine, as well as limited other operating items.
Geographically, AngloGold Ashanti is more diversified than many single-country miners. That diversification helps reduce dependence on one mine or one government, but it also means the company must manage multiple political, regulatory, labor, and operating environments at the same time.
The financial flow has improved sharply in the last two years. Revenue and gross profit expanded meaningfully from 2024 to 2025, while net income recovered strongly after a weak 2023. That pattern suggests the group benefited from a much better gold price environment, stronger operating leverage, and tighter control over costs relative to revenue growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 04, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $48.01B | |
| Beta ⓘ | 0.75 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.62 | 17.61 |
| P/B Ratio ⓘ | 6.76 | 1.78 |
| FCF Yield ⓘ | 8.82% | 5.86% |
| Dividend Yield ⓘ | 4.76% | 2.07% |
| EBIT / EV ⓘ | 13.02% | 6.43% |
| PEG ⓘ | 0.78 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 27.00% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | 19.38% | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | 37.07% | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | 6.38% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 25.32% | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | 89.65% | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | 59.35% | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 45.46% | 9.31% |
| ROA (Latest) ⓘ | 25.05% | 4.94% |
| ROIC (5Y Median) ⓘ | 9.45% | 7.91% |
| ROA (5Y Median) ⓘ | 7.83% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | -0.16 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.16 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.14 | 0.91 |
| Net Debt / Assets ⓘ | -6.37% | 13.69% |
| EBITDA / Interest ⓘ | 35.88 | 11.93 |
| Operating Margin (Latest) ⓘ | 53.89% | 13.07% |
| Operating Margin (5Y Median) ⓘ | 20.13% | 11.86% |
| Debt to Equity (Latest) ⓘ | 20.00% | 40.43% |
| Profit Margin (Latest) ⓘ | 32.20% | 6.57% |
| Free Cash Flow (Latest) ⓘ | $4.23B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +598.38% | +65.06% |
| 12M Return (excl. last month) ⓘ | +94.07% | +35.57% |
| 6M Return ⓘ | -4.48% | +1.69% |
| Price vs. 200-Day MA ⓘ | -0.28% | +0.95% |
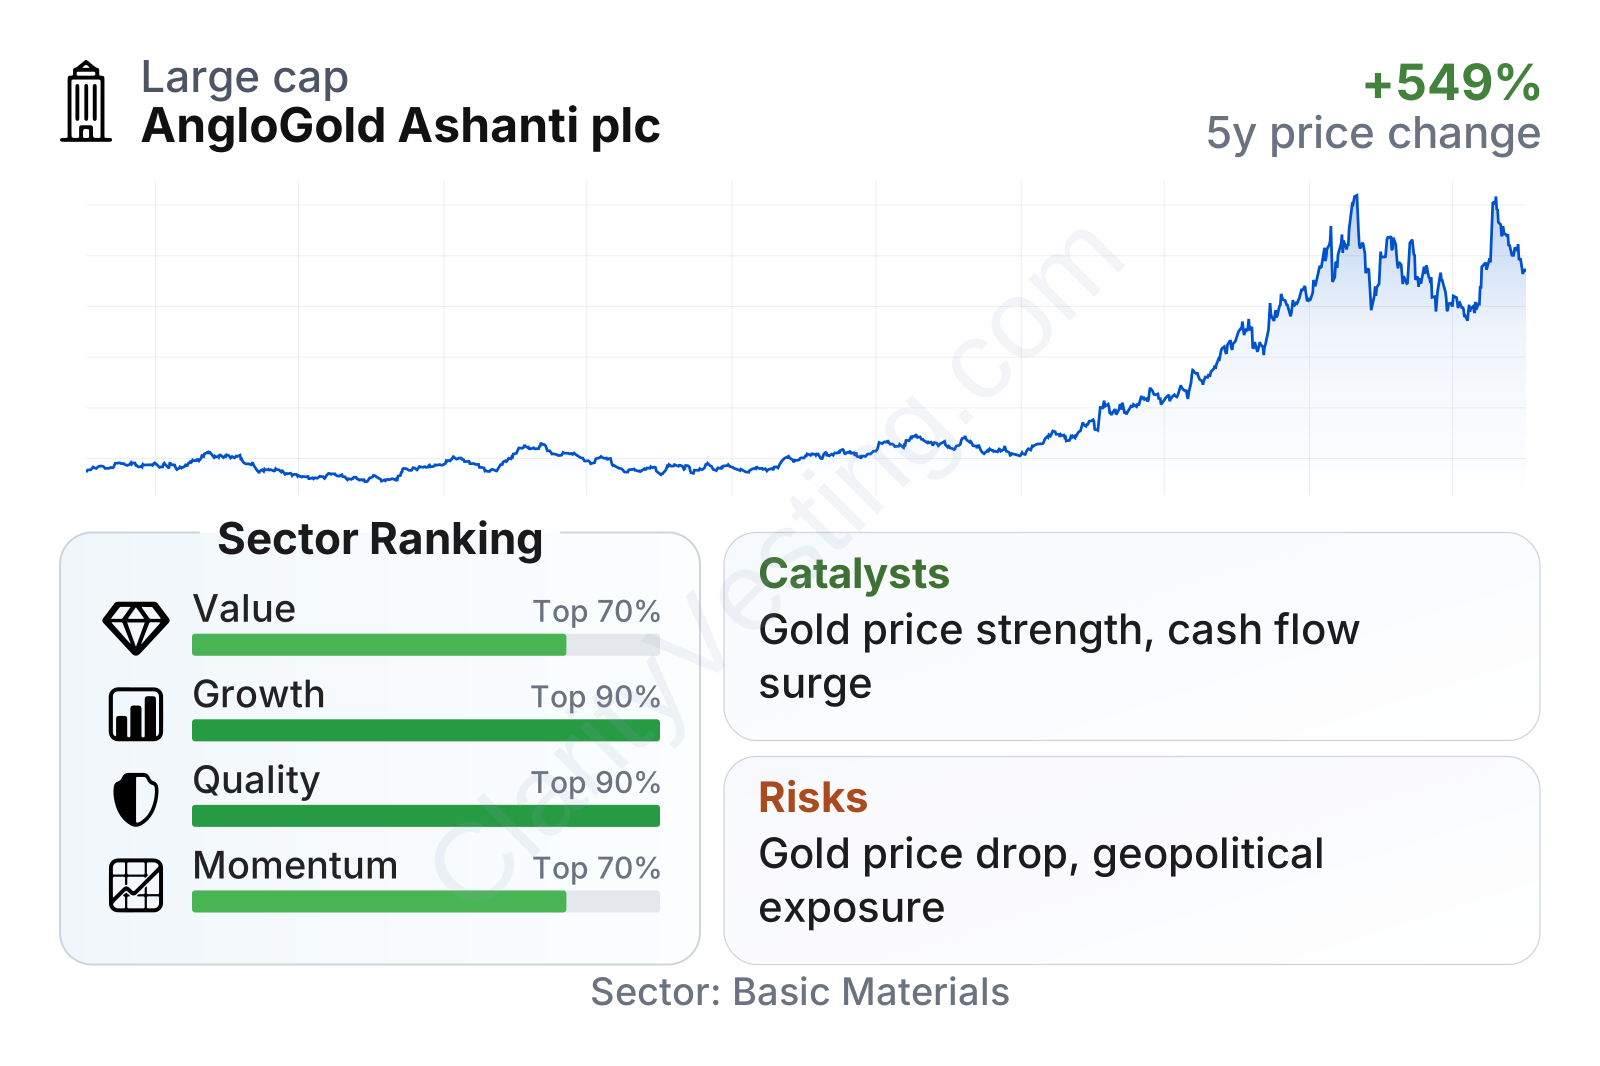
AngloGold Ashanti currently stands out as a large gold producer with a relatively moderate share-price volatility profile for a mining stock, as shown by its beta below 1. The broader factor picture is strong: growth ranks near the top of the sector, momentum is also well above average, and quality metrics are healthy. Value looks mixed rather than outright cheap, with a lower earnings multiple than the sector median but a much higher price-to-book ratio, reflecting the market’s willingness to pay more for the company’s improved profitability and cash generation.
The stock’s multiyear price trend has been powerful, but it has also been volatile, which is normal for gold miners. Operationally, free cash flow generation and margins have improved enough to support a stronger dividend profile than the sector median, which gives the company a more balanced financial profile than miners that rely only on rising commodity prices.
Growth
Gold mining is not a classic high-volume growth industry, but it can still be a favorable long-term sector when macro conditions support the gold price. Gold often gains attention during periods of inflation concerns, high government debt, geopolitical tension, central bank reserve diversification, or lower real interest rates. That means the sector’s growth is tied less to unit demand expansion and more to price strength, disciplined project development, and reserve replacement.
AngloGold Ashanti’s strategy broadly fits that reality. The company has been reshaping its portfolio over several years, focusing on operating quality, larger long-life assets, capital discipline, and jurisdictional balance. For a miner, that matters because long-term value depends not only on current production, but also on keeping reserves in the ground, extending mine life, and avoiding expensive growth projects that destroy returns.
Recent growth has been notably strong. Revenue growth has accelerated well above the sector median, and the company’s five-year trends in revenue per share, earnings per share, operating margin progression, and dividend growth all point to a business that has improved much faster than many peers. This does not mean growth will be smooth every year, since production can swing with mine sequencing and maintenance schedules, but the medium-term direction has clearly strengthened.
Free cash flow is one of the most encouraging features. After a much weaker period, cash generation has risen sharply and now sits at a level that gives the company more flexibility for dividends, debt reduction, exploration, and project development. In mining, strong free cash flow is especially important because it helps fund future ounces internally instead of relying heavily on debt or equity issuance.
A major catalyst has been the stronger gold price environment, but AngloGold Ashanti also has company-specific support. Its improved operating margins, lower leverage, and stronger balance sheet mean more of each additional dollar in gold price can flow through to earnings and cash flow than in the past. If gold remains firm and execution stays steady, this operating leverage remains a meaningful driver.
Recent company communications have also highlighted ongoing asset optimization and development work across the portfolio. That does not remove mining risk, but it suggests the group is trying to turn the current favorable market backdrop into a longer-lasting improvement in returns rather than simply enjoying a temporary price windfall.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


