Stock Analysis · AtriCure Inc (ATRC)
Overview
AtriCure is a medical device company focused on treating cardiac conditions, especially atrial fibrillation and related disorders. Its products are used mainly by heart surgeons and electrophysiologists in hospital settings. The company is best known for devices that help restore normal heart rhythm, close the left atrial appendage to reduce stroke risk, and manage post-operative pain through cryo-based nerve block technology.
The business is built around several product families rather than one single device. Based on the company’s recent annual reporting, revenue is concentrated in ablation products used in cardiac surgery, followed by left atrial appendage management and then pain management. A practical breakdown is:
- Open ablation products: about 50% of revenue — devices used in surgical ablation procedures, including clamps and related systems for treating atrial fibrillation during open-heart surgery.
- Left atrial appendage management: about 25% of revenue — mainly the AtriClip platform, used to exclude the left atrial appendage during surgery.
- Pain management: about 15% of revenue — cryo-based solutions, including cryoSPHERE and related systems, used to manage pain after thoracic and other procedures.
- Hybrid AF therapy and other minimally invasive ablation products: about 10% of revenue — products supporting less invasive and hybrid procedures, including EPi-Sense and related offerings.
This mix matters because it shows AtriCure is not purely dependent on one niche. Even so, its economic engine is still tied to procedure growth in heart surgery and atrial fibrillation treatment, so adoption trends in those areas remain central to the company’s long-term outlook.
Over the last several years, the company has consistently expanded revenue, while profitability has been much more uneven. Gross profit has grown steadily, but operating expenses—especially selling, administrative, and research spending—have stayed high as AtriCure has continued investing in commercialization and new indications. That helps explain why sales have scaled faster than earnings.
The overall picture is of a specialized healthcare company with a growing installed clinical presence, solid gross margins, and a strategy that prioritizes market expansion over near-term profit maximization.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $2.86B | |
| Beta ⓘ | 1.26 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 267.62 | 24.06 |
| P/B Ratio ⓘ | 5.09 | 3.08 |
| FCF Yield ⓘ | 2.03% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 0.57% | 0.63% |
| PEG ⓘ | 10.00 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 12.80% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 17.07% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | -0.49% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 2.45% | 3.29% |
| ROA (Latest) ⓘ | 1.61% | 3.02% |
| ROIC (5Y Median) ⓘ | -3.43% | 4.75% |
| ROA (5Y Median) ⓘ | -5.08% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | -5.73 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | -3.56 | 0.99 |
| Net Debt / Assets ⓘ | -14.30% | 5.33% |
| EBITDA / Interest ⓘ | 3.84 | 9.63 |
| Operating Margin (Latest) ⓘ | 2.96% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -5.74% | 7.80% |
| Debt to Equity (Latest) ⓘ | 13.76% | 28.99% |
| Profit Margin (Latest) ⓘ | 1.85% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $58.11M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +23.91% | +37.48% |
| 12M Return (excl. last month) ⓘ | +32.25% | +20.85% |
| 6M Return ⓘ | +89.30% | +9.73% |
| Price vs. 200-Day MA ⓘ | +47.76% | +4.69% |
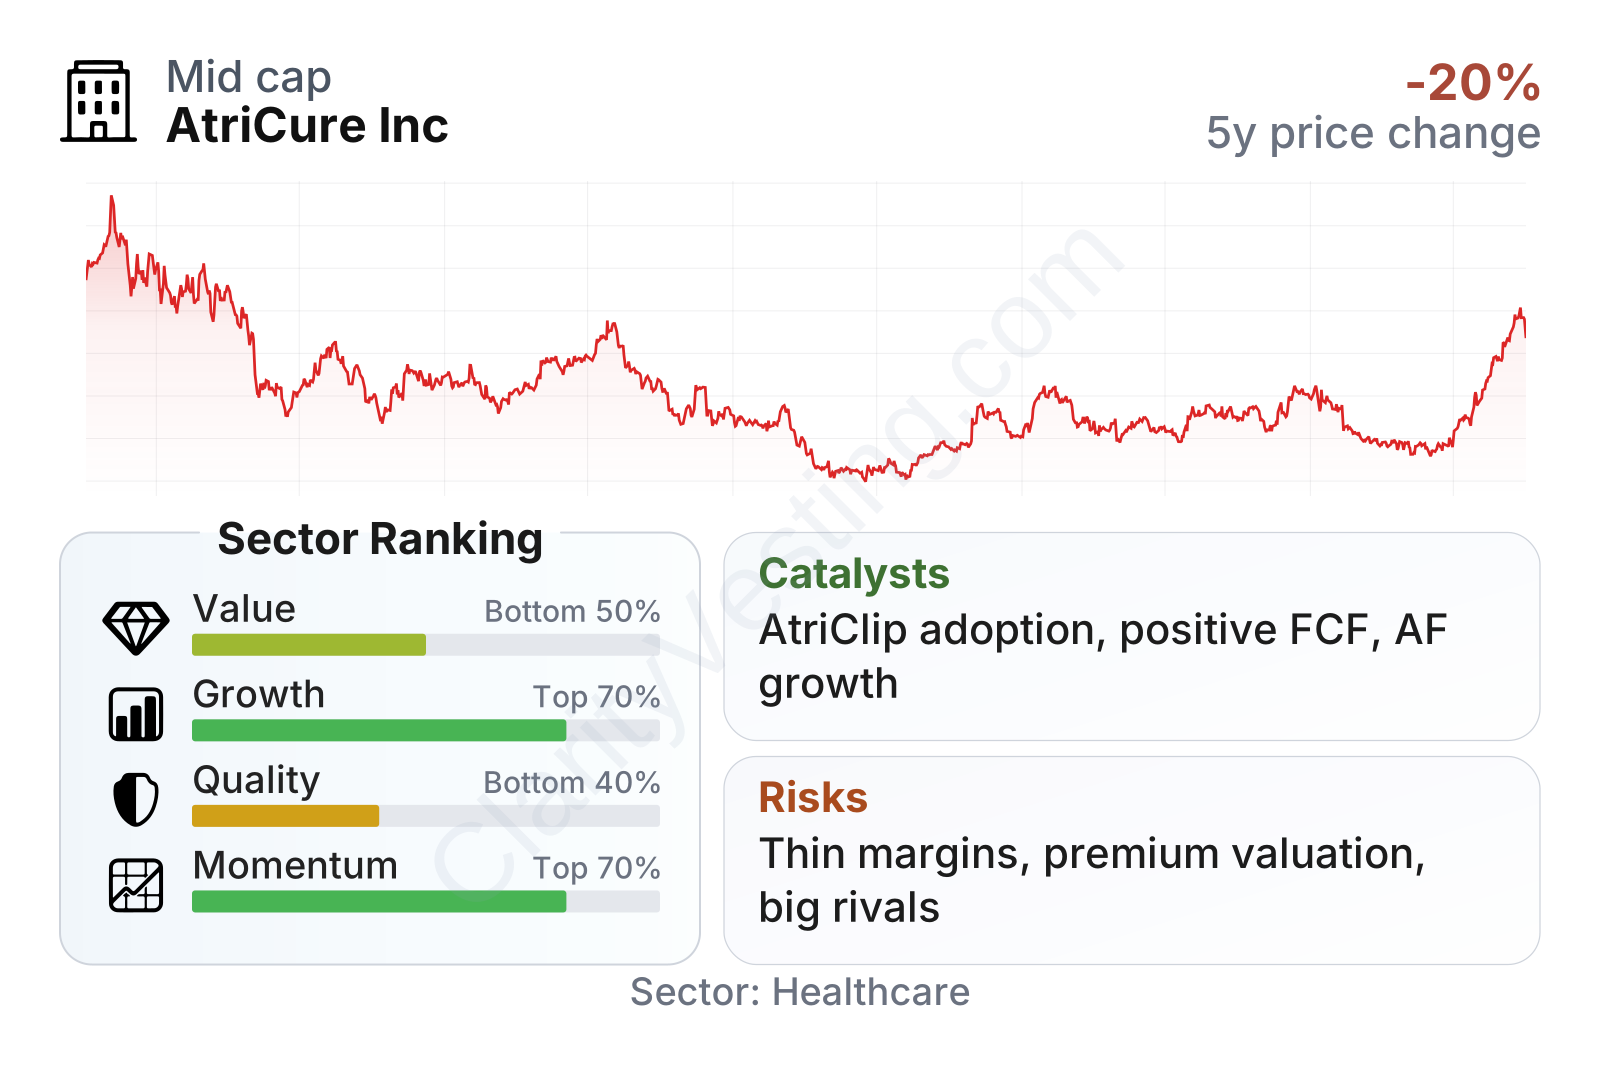
AtriCure is a mid-sized medical technology company with above-average share price volatility for the healthcare sector. On growth and market momentum, it ranks relatively well versus peers, supported by double-digit revenue expansion and a strong recent stock rebound. On quality and valuation, the picture is less favorable: profitability remains modest, returns on capital are still below sector norms, and valuation multiples are elevated compared with most healthcare equipment companies.
The stock history also shows that this is not a stable, low-volatility name. Shares fell sharply from 2021 through 2024 before recovering meaningfully, which suggests the market has repeatedly reassessed the balance between future growth potential and the company’s path to consistent earnings.
Growth
AtriCure operates in an attractive long-term area of healthcare. Atrial fibrillation is common, especially in older populations, and stroke prevention in cardiac patients is an important clinical priority. That gives the company exposure to structural drivers such as aging demographics, broader diagnosis rates, and increasing use of surgical and hybrid approaches to rhythm management.
The strategy also makes sense on a business level. Instead of relying only on one procedure type, AtriCure has built a portfolio around adjacent needs in the operating room: ablation, left atrial appendage exclusion, and pain management. That can deepen hospital relationships and make each account more valuable over time.
Revenue growth has stayed consistently positive for years, generally in the low-to-mid teens recently after periods above 20%. That moderation suggests AtriCure is now scaling from a larger base, but it is still expanding faster than the sector median. Its five-year revenue per share growth is also notably stronger than many peers, which supports the view that the company has real commercial traction rather than purely acquisition-driven expansion.
A particularly important development is the improvement in cash generation.
Free cash flow has moved from negative territory to clearly positive territory over the trailing twelve months. That shift is significant because it suggests the business may be entering a more mature phase where sales growth no longer needs to be fully offset by heavy cash burn. For long-term analysis, that is one of the most constructive financial changes in the recent profile.
Recent company updates have also pointed to continuing adoption across key franchises, especially AtriClip and pain management, while management has continued investing in physician education, clinical evidence, and market development. For a company like AtriCure, strong catalysts usually do not come from one headline event alone; they come from gradual changes in procedure guidelines, broader surgeon adoption, expanding reimbursement support, and more hospitals integrating these therapies into standard care.
Another growth support is the company’s position in areas that are still not fully penetrated. If AtriCure keeps converting eligible procedures into routine use of its devices, there is still room for revenue expansion without needing a dramatic change in the overall healthcare market.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


