Stock Analysis · AptarGroup Inc (ATR)
Overview
AptarGroup is a packaging and drug-delivery company that makes dispensing systems used in everyday consumer products and healthcare applications. Its products include pumps, sprayers, aerosol valves, closures, elastomer components, and active material science solutions that help protect sensitive products. In simple terms, Aptar often does not make the product inside the package; it makes the part that dispenses, seals, or helps preserve it.
The business is diversified across healthcare, beauty, personal care, home care, food, beverage, and pharmaceutical end markets. That mix matters because it gives Aptar exposure to both steady consumer demand and higher-value healthcare applications, especially nasal delivery, injectable components, and other specialized systems.
Based on recent company reporting, revenue is mainly generated from three operating segments:
- Aptar Pharma: approximately 36% of revenue. This segment provides drug-delivery systems, active packaging, and elastomeric primary packaging for prescription, consumer health, and injectables markets.
- Aptar Beauty: approximately 34% of revenue. This includes fragrance pumps, lotion pumps, cosmetic dispensing systems, and packaging components used in prestige and mass beauty products.
- Aptar Closures: approximately 30% of revenue. This segment serves food, beverage, personal care, and household products with closures, dispensing caps, and related packaging solutions.
Aptar’s business model is attractive because many of its components are small in cost relative to the final product, but important for performance, safety, branding, and convenience. That can support recurring customer relationships and healthier margins than standard commodity packaging.
Over the last several years, revenue has trended upward overall, while profitability improved even faster. The strongest visual takeaway is that earnings have expanded more than sales, suggesting better mix, pricing, and operating discipline rather than growth driven only by volume.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $7.99B | |
| Beta ⓘ | 0.34 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 22.68 | 25.42 |
| P/B Ratio ⓘ | 3.14 | 3.08 |
| FCF Yield ⓘ | 3.89% | 3.12% |
| Dividend Yield ⓘ | 1.50% | 1.85% |
| EBIT / EV ⓘ | 5.63% | 0.56% |
| PEG ⓘ | 2.60 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 6.30% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 4.38% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -9.47% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 7.82% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 3.50% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | 52.42% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | 5.60% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.17% |
| ROA (Latest) ⓘ | 7.08% | 2.98% |
| ROIC (5Y Median) ⓘ | 9.43% | 4.56% |
| ROA (5Y Median) ⓘ | 6.57% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 2.40 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.31 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 1.50 | 1.00 |
| Net Debt / Assets ⓘ | 24.10% | 5.06% |
| EBITDA / Interest ⓘ | 12.95 | 9.55 |
| Operating Margin (Latest) ⓘ | 13.09% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 11.91% | 7.33% |
| Debt to Equity (Latest) ⓘ | 54.31% | 26.68% |
| Profit Margin (Latest) ⓘ | 9.22% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $310.39M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +9.61% | +51.61% |
| 12M Return (excl. last month) ⓘ | -4.05% | +19.90% |
| 6M Return ⓘ | +3.62% | +10.10% |
| Price vs. 200-Day MA ⓘ | +1.49% | +6.44% |
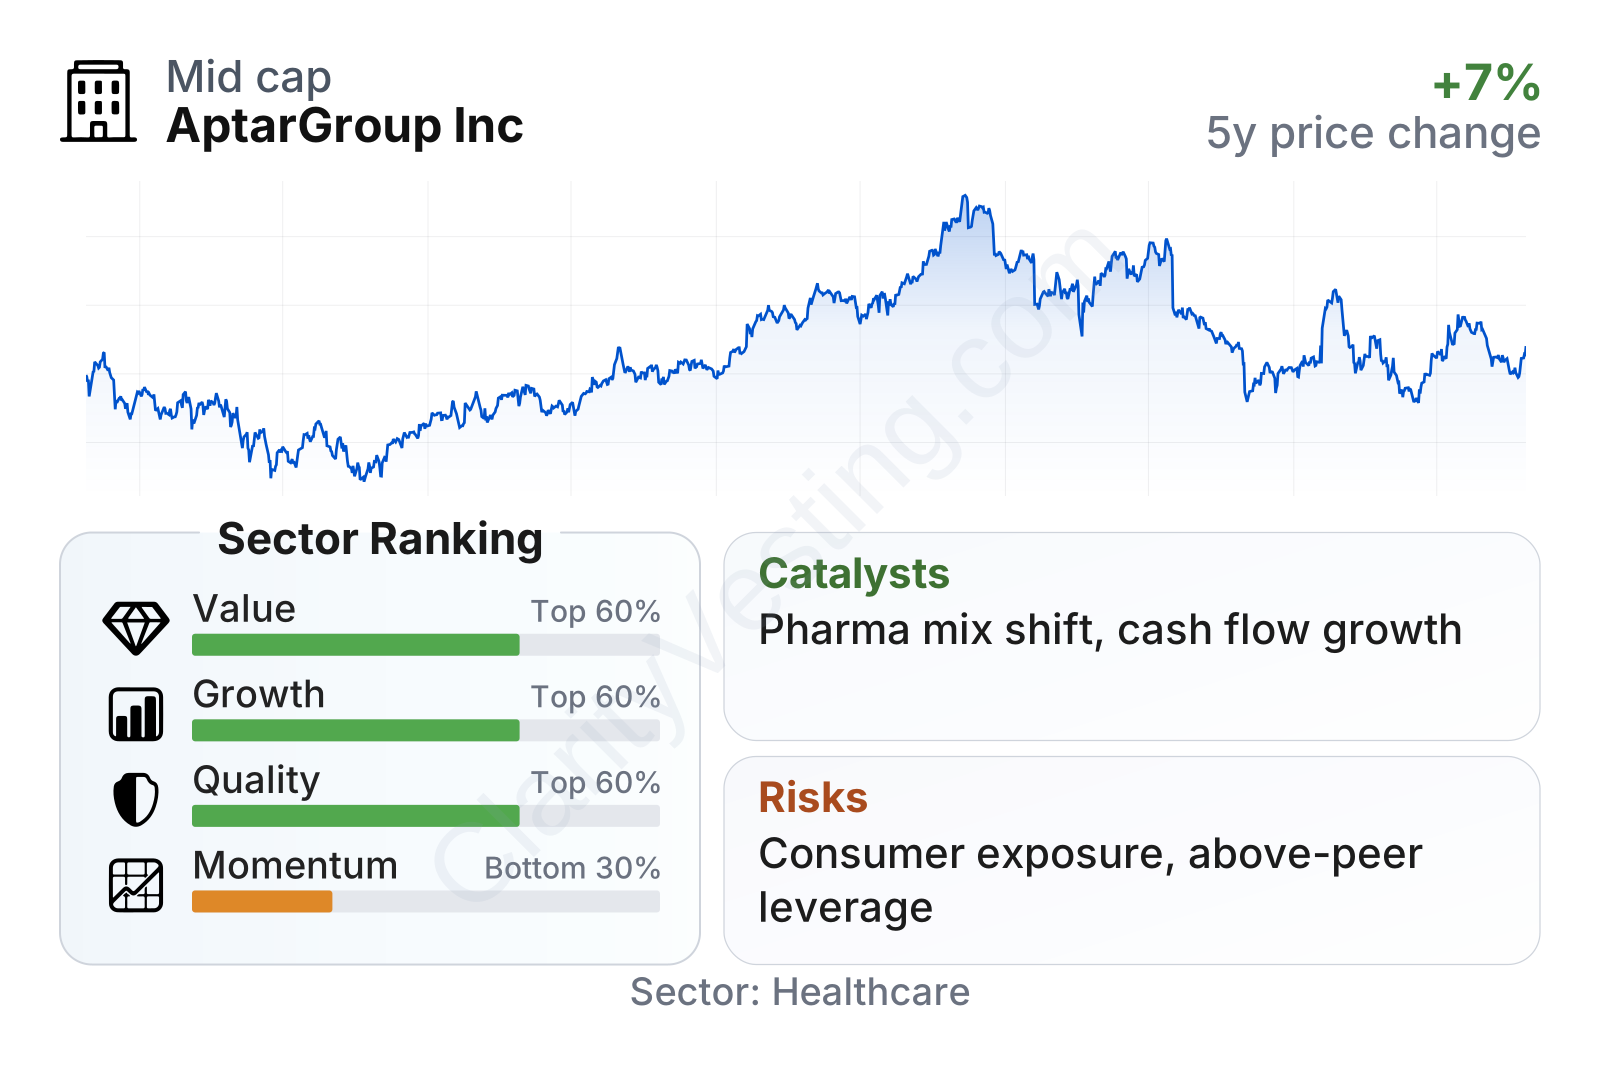
Aptar is a mid-sized healthcare and packaging supplier with a relatively low share-price volatility profile, as reflected by a beta well below 1. In the broader healthcare group, its overall value, growth, and quality characteristics sit around the better half of the sector, while recent stock performance has lagged. Profitability stands out more than headline growth: operating margin is around 13% and profit margin is near 9%, both clearly above sector medians. Free cash flow generation is also solid, and the cash flow yield appears somewhat stronger than the typical peer. The main weaker point in the snapshot is leverage, which is higher than the sector median, even though interest coverage remains comfortable.
Growth
Aptar operates in markets with favorable long-term demand drivers. In healthcare, demand is supported by aging populations, growing use of self-administration, biologics, nasal delivery, and stricter requirements for safe and reliable drug packaging. In consumer packaging, long-term growth is steadier and less exciting, but innovation still matters because brands want better dispensing, more sustainable designs, and differentiated user experiences.
The company’s strategy makes sense for future growth because it is gradually leaning toward segments with higher technical complexity and better margins, especially pharma. Pharmaceutical delivery and protection systems usually have longer product cycles, higher qualification barriers, and more demanding customer requirements than ordinary consumer packaging. That tends to create stickier business once a component is designed into a drug or healthcare product.
Revenue growth has not been perfectly smooth quarter to quarter, but the broader pattern remains positive. After a softer patch in 2022 and some uneven quarters later on, growth reaccelerated in several periods and most recently remained in the mid-single-digit range year over year. That points to a business that is still expanding, though not at a high-growth pace.
Cash generation is an encouraging part of the picture. Free cash flow climbed sharply over the last several years and remains well above earlier levels, even after a modest pullback from the peak. For a company like Aptar, that is important because cash supports capital spending, acquisitions, debt management, and shareholder returns without relying too heavily on external financing.
Recent company updates have also pointed to continued investment in pharma capacity, active material science, and product platforms tied to injectable and consumer health applications. These are not short-lived opportunities; they fit with durable healthcare trends and with customer demand for functionality, safety, and sustainability. Aptar has also emphasized transformation efforts and productivity initiatives, which can support earnings growth even when sales growth is moderate.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


