Stock Analysis · Atkore International Group Inc (ATKR)
Overview
Atkore International Group Inc. is an industrial manufacturer focused on electrical, safety, and infrastructure products used in non-residential construction, utilities, data centers, telecommunications, and some residential and industrial projects. In simple terms, the company makes the systems that help route, protect, and support electrical wiring and related infrastructure inside buildings and across networks.
Its business is built around products that are essential but often hidden from view after installation: electrical conduit, cable management systems, metal framing, mechanical pipe, fittings, and safety infrastructure. Demand is tied closely to construction activity, renovation spending, and infrastructure investment, especially in North America.
Based on recent company reporting, revenue is mainly generated from two operating segments.
- Electrical segment: about 80% to 85% of revenue — This is the core business and includes PVC conduit, steel conduit, fittings, armored cable, cable management, and related products used to protect and route electrical systems in commercial, industrial, utility, and data-related applications.
- Safety & Infrastructure segment: about 15% to 20% of revenue — This segment includes metal framing, mechanical pipe, perimeter security products, and infrastructure solutions supporting construction, industrial facilities, and physical security installations.
That mix matters because it shows Atkore is still primarily an electrical conduit and cable-routing company, even though it has broadened into adjacent categories through acquisitions and product expansion. Over the last few years, the company’s profit profile has been highly influenced by pricing and product mix in PVC conduit, a category that can be very profitable in tight supply conditions but also very cyclical when pricing normalizes.
From a broad financial flow perspective, the company has gone through a clear reset. Revenue has fallen from the unusually strong 2022 peak, and profits have compressed much faster than sales. That pattern suggests the earlier earnings surge was not fully structural and that the business is now moving through a more normal, and currently weaker, part of its cycle.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Electrical Equipment & Parts | |
| Market Cap ⓘ | $3.21B | |
| Beta ⓘ | 1.69 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 22.29 |
| P/B Ratio ⓘ | 2.53 | 1.98 |
| FCF Yield ⓘ | 1.79% | 6.26% |
| Dividend Yield ⓘ | 1.39% | 1.92% |
| EBIT / EV ⓘ | -4.94% | 4.83% |
| PEG ⓘ | 1.39 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.10% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 7.85% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -35.21% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 22.44% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -27.25% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | -12.68% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | -47.32% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -6.70% | 10.75% |
| ROA (Latest) ⓘ | -5.82% | 5.41% |
| ROIC (5Y Median) ⓘ | 34.19% | 9.37% |
| ROA (5Y Median) ⓘ | 24.93% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.56 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.39 |
| Net Debt / Assets ⓘ | 20.68% | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | -6.33% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 25.39% | 10.30% |
| Debt to Equity (Latest) ⓘ | 71.58% | 64.82% |
| Profit Margin (Latest) ⓘ | -5.55% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $57.48M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -28.62% | +67.77% |
| 12M Return (excl. last month) ⓘ | +55.33% | +12.05% |
| 6M Return ⓘ | +42.89% | 0.00% |
| Price vs. 200-Day MA ⓘ | +24.10% | +0.67% |
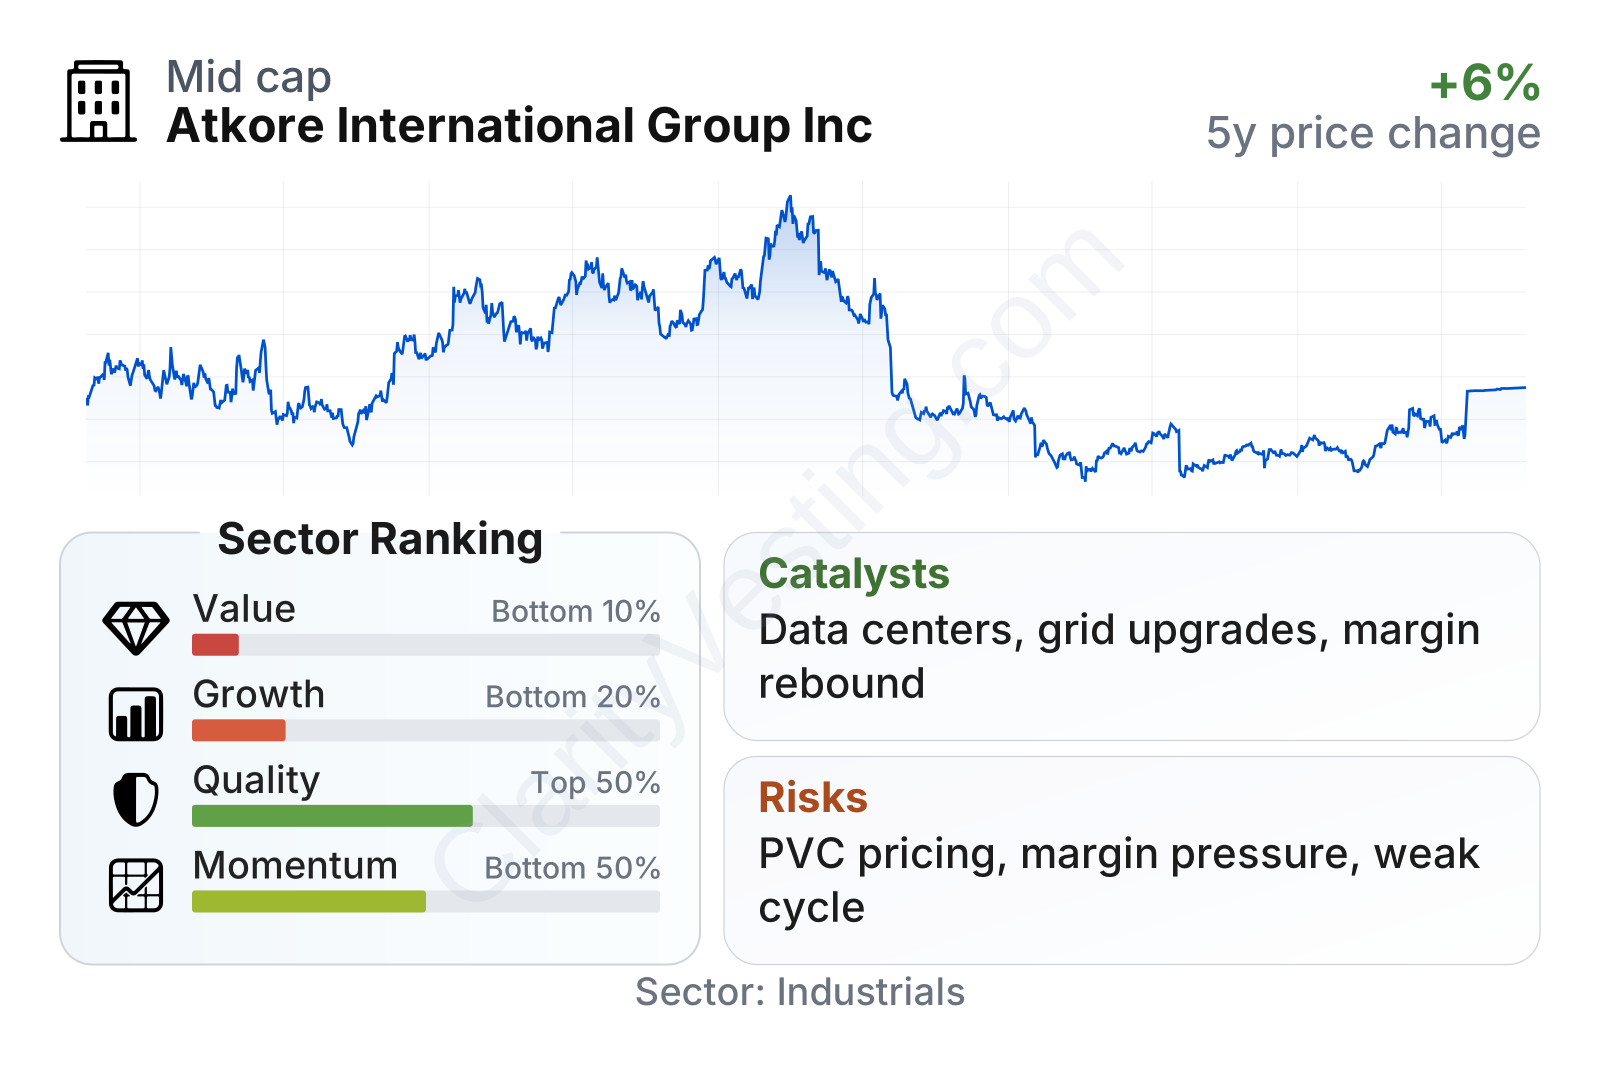
Atkore is a mid-sized industrial company with a stock that has been much more volatile than the average large U.S. company, as shown by its elevated beta. The factor breakdown is mixed. Quality looks better over a multi-year view than it does on the latest trailing numbers, reflecting how strong the business was during the peak years. By contrast, value and growth rankings currently look weak relative to the broader industrial peer group, largely because earnings and cash generation have come down sharply from prior highs while leverage has edged up.
The share price history also shows how cyclical market expectations have been. The stock climbed strongly through the earlier margin expansion period, then gave back a large part of those gains as earnings weakened. More recently, momentum has improved meaningfully, but that recovery in price has come before a full recovery in profitability.
Growth
Atkore operates in markets that benefit from several long-term themes: grid modernization, electrification, data center buildouts, infrastructure renewal, and the need for more resilient electrical systems in commercial and industrial facilities. Those are attractive end markets over a long horizon, and they support the idea that demand for conduit, cable management, and related infrastructure should remain relevant for years.
Its strategy also makes industrial sense. The company has historically combined large-scale manufacturing with a broad distribution footprint and bolt-on acquisitions that extend its product offering. That approach can help deepen customer relationships because contractors and distributors often prefer to source multiple related products from fewer suppliers. In principle, that creates cross-selling opportunities and can make Atkore more embedded in project workflows.
Still, recent growth has been uneven. Year-over-year revenue turned negative for an extended period after the extraordinary conditions of 2021 and 2022, and only recently returned to modest positive territory. That improvement is important because it suggests the decline phase may be easing, but the pace so far points more to stabilization than to a powerful new expansion cycle.
Cash generation tells a similar story. Atkore remains free-cash-flow positive, which is a useful sign of resilience, but trailing cash flow has dropped sharply from earlier levels. For a long-term business case, the key question is whether cash flow can rebuild as volumes, mix, and pricing normalize rather than continue to fade.
Potential catalysts are real, but they are specific. Data center construction is one of the most visible opportunities because these facilities require dense electrical infrastructure and cable management systems. U.S. manufacturing reshoring, utility upgrades, and public infrastructure spending can also support demand. In addition, if the company continues to broaden its product set in adjacent categories, it may reduce some of its dependence on the most cyclical conduit pricing swings.
Recent company updates have also highlighted ongoing capital returns and portfolio actions, showing management is still actively shaping the business rather than simply waiting for the cycle to improve. For long-term analysis, that matters more than short-term quarter-to-quarter noise: the underlying question is whether Atkore emerges from this downturn with a broader, more durable earnings base than it had before.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


