Stock Analysis · Avino Silver & Gold Mines Ltd (ASM)
Overview
Avino Silver & Gold Mines Ltd is a small precious-metals mining company focused on Mexico. It explores for mineral deposits, develops mining infrastructure, and produces concentrates containing silver, gold, and copper. Its main operating base is the Avino property in Durango, where the company has been working to expand production from existing areas while advancing additional zones that could support a larger mining operation over time.
The business makes money by extracting ore, processing it, and selling metal concentrates to smelters. Because it is a miner rather than a manufacturer, its results depend heavily on how much ore it processes, the grade of that ore, operating costs, and market prices for silver, gold, and copper.
Based on the latest annual results and company disclosures, revenue is mainly tied to payable metals in concentrate sales. The approximate mix is:
- Silver: about 47% to 50% of revenue, the company’s core product and main economic driver.
- Gold: about 25% to 30% of revenue, produced together with silver-bearing ore and important for cash generation.
- Copper: about 20% to 25% of revenue, largely from copper concentrate sales and a meaningful contributor to diversification.
This mix can shift from quarter to quarter depending on ore grades and metal prices, but silver remains the central part of the business model. Over the last several years, the company has moved from a weak earnings profile to a much more profitable one, helped by higher production, better grades, and stronger metal prices. Revenue rose from roughly $11 million in 2021 to nearly $87 million in 2025, while operating profit expanded sharply as costs grew much more slowly than sales.
The operating picture has improved materially since 2023. Sales increased strongly through 2024 and 2025, while operating expenses did not rise at the same pace, allowing a much larger share of revenue to reach operating income and net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Precious Metals & Mining | |
| Market Cap ⓘ | $942.70M | |
| Beta ⓘ | 3.00 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 21.35 | 16.90 |
| P/B Ratio ⓘ | 3.45 | 1.65 |
| FCF Yield ⓘ | 1.84% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 6.73% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 22.80% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 48.77% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 53.63% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 17.23% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 61.71% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 18.66% | 9.26% |
| ROA (Latest) ⓘ | 16.50% | 4.91% |
| ROIC (5Y Median) ⓘ | 3.46% | 7.70% |
| ROA (5Y Median) ⓘ | 2.98% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -2.27 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.67 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -2.29 | 0.95 |
| Net Debt / Assets ⓘ | -42.23% | 13.69% |
| EBITDA / Interest ⓘ | 84.73 | 12.34 |
| Operating Margin (Latest) ⓘ | 51.81% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 17.60% | 11.80% |
| Debt to Equity (Latest) ⓘ | 3.04% | 40.56% |
| Profit Margin (Latest) ⓘ | 38.18% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $17.31M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +974.54% | +68.89% |
| 12M Return (excl. last month) ⓘ | +63.31% | +30.21% |
| 6M Return ⓘ | -12.18% | -4.16% |
| Price vs. 200-Day MA ⓘ | -20.88% | -1.27% |
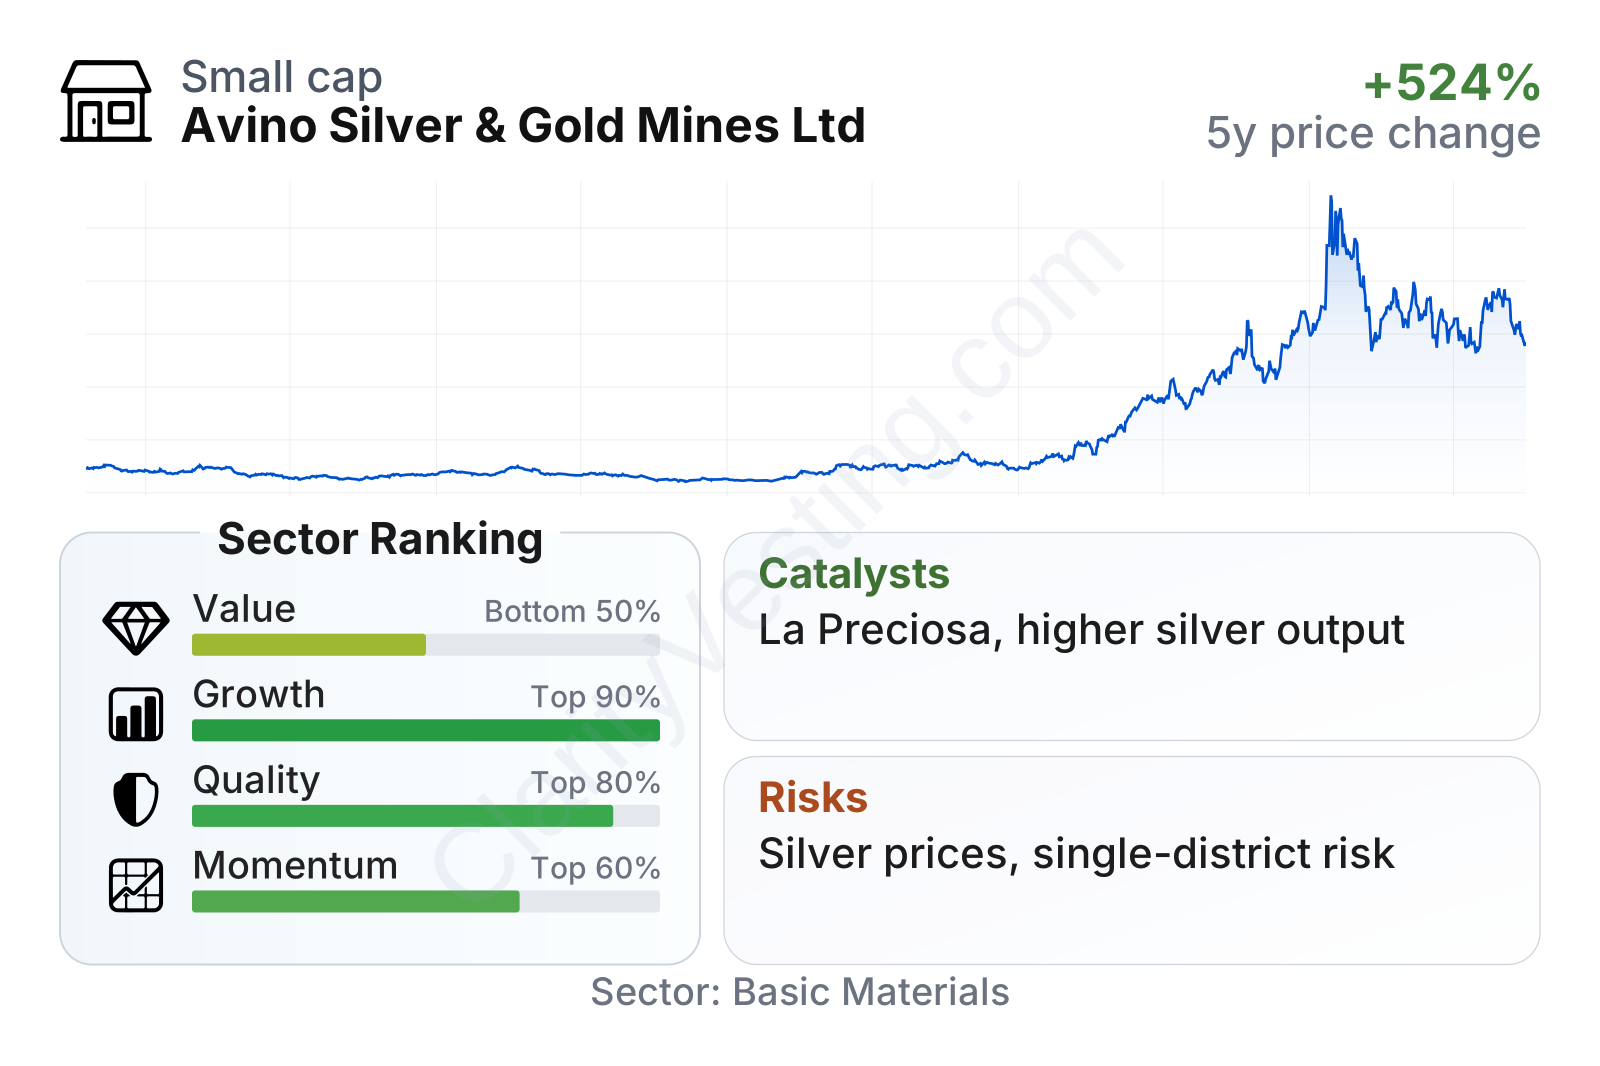
Avino sits in the smaller-company range, and the share price has been highly volatile, which is typical for junior and mid-tier miners. The stock’s growth and profitability indicators rank well against much of the sector, while valuation measures look less attractive on simple multiples such as price-to-earnings and price-to-book. The balance sheet is a clear strength: leverage is very low, cash generation is positive, and recent returns on capital are stronger than the industry median.
Growth
Silver and gold mining is part of a sector with long-term support from several themes. Silver has a dual role: it is both a precious metal and an industrial input used in solar panels, electronics, and electrification-related applications. Gold remains important as a store of value and often attracts demand during periods of inflation, currency weakness, or geopolitical stress. That gives companies with growing silver output a potentially favorable industry backdrop, although the sector always remains cyclical.
Avino’s strategy is relatively easy to understand. First, it is trying to get more from its current mining and milling base. Second, it is working to bring additional areas of its Avino district into production. Third, it is using exploration and engineering work to extend mine life and improve the scale of the operation. For a long-term view, that strategy is sensible because a small producer usually creates the most value by increasing throughput, extending reserves and resources, and spreading fixed costs over a larger production base.
Revenue growth has been strong but uneven, which is normal in mining. The more important point is the broader direction: after a soft period in 2023, sales accelerated in 2024 and remained positive into 2026, with recent year-over-year growth still above the sector median.
Cash generation has also improved. Free cash flow was negative during earlier development and ramp-up periods, but it turned clearly positive more recently. That matters because internally generated cash gives a mining company more flexibility to fund exploration, development, and plant improvements without relying as much on debt or equity issuance.
A key catalyst is the company’s effort to advance the La Preciosa project and integrate it with the broader Avino district plan. Management has described La Preciosa as an important future source of production growth, particularly for silver. If development milestones, permitting progress, and mine planning continue to move forward, the company could gain a larger production platform than it has today.
Another meaningful opportunity comes from operating leverage. When a miner already has processing infrastructure in place, additional tons and better grades can lift earnings quickly. Avino’s recent financial improvement suggests it is benefiting from this dynamic. In simple terms, if production expands and metal prices stay supportive, profit can rise faster than revenue.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


