Stock Analysis · Amerigo Resources Ltd (ARREF)
Overview
Amerigo Resources Ltd is a copper-focused company that operates in Chile through Minera Valle Central, or MVC. Rather than running a traditional large-scale mine, the business recovers copper and molybdenum from tailings and fresh tailings produced by Codelco’s El Teniente mine, one of the world’s largest underground copper operations. In simple terms, Amerigo processes material that has already been mined to extract additional metal that was not recovered the first time.
This business model is unusual in the copper industry. It gives Amerigo exposure to copper prices without the same level of exploration risk, mine development risk, or reserve replacement pressure faced by many miners. At the same time, it also means the company depends heavily on one operating site and one broader mining complex.
Revenue comes mainly from the sale of recovered metals. Based on the company’s recent annual disclosures, the breakdown is approximately:
- Copper: about 90% to 95% of revenue. This is the core business and includes copper produced from historic and fresh tailings processed at MVC.
- Molybdenum: about 5% to 10% of revenue. This is a by-product recovered from the same processing stream and provides a smaller but useful secondary income source.
The recent financial flow shows a business that weakened meaningfully in 2022 and 2023, then recovered in 2024 and improved further in 2025. Revenue moved back above prior lows, while operating profit and net income expanded faster than sales, suggesting improved operating leverage when metal prices and plant performance are favorable.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Copper | |
| Market Cap ⓘ | $1.02B | |
| Beta ⓘ | 2.12 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 19.72 | 16.90 |
| P/B Ratio ⓘ | 8.50 | 1.65 |
| FCF Yield ⓘ | 7.75% | 5.76% |
| Dividend Yield ⓘ | 1.93% | 2.13% |
| EBIT / EV ⓘ | 9.72% | 6.30% |
| PEG ⓘ | 0.30 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 52.20% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 3.89% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -14.55% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -3.28% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -4.11% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -20.87% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 54.19% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 65.95% | 9.26% |
| ROA (Latest) ⓘ | 28.77% | 4.91% |
| ROIC (5Y Median) ⓘ | 23.94% | 7.70% |
| ROA (5Y Median) ⓘ | 9.50% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | 111.29 | 12.34 |
| Operating Margin (Latest) ⓘ | 23.12% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 11.61% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | 20.88% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $78.99M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +767.17% | +68.89% |
| 12M Return (excl. last month) ⓘ | +284.52% | +30.21% |
| 6M Return ⓘ | +41.51% | -4.16% |
| Price vs. 200-Day MA ⓘ | +31.94% | -1.27% |
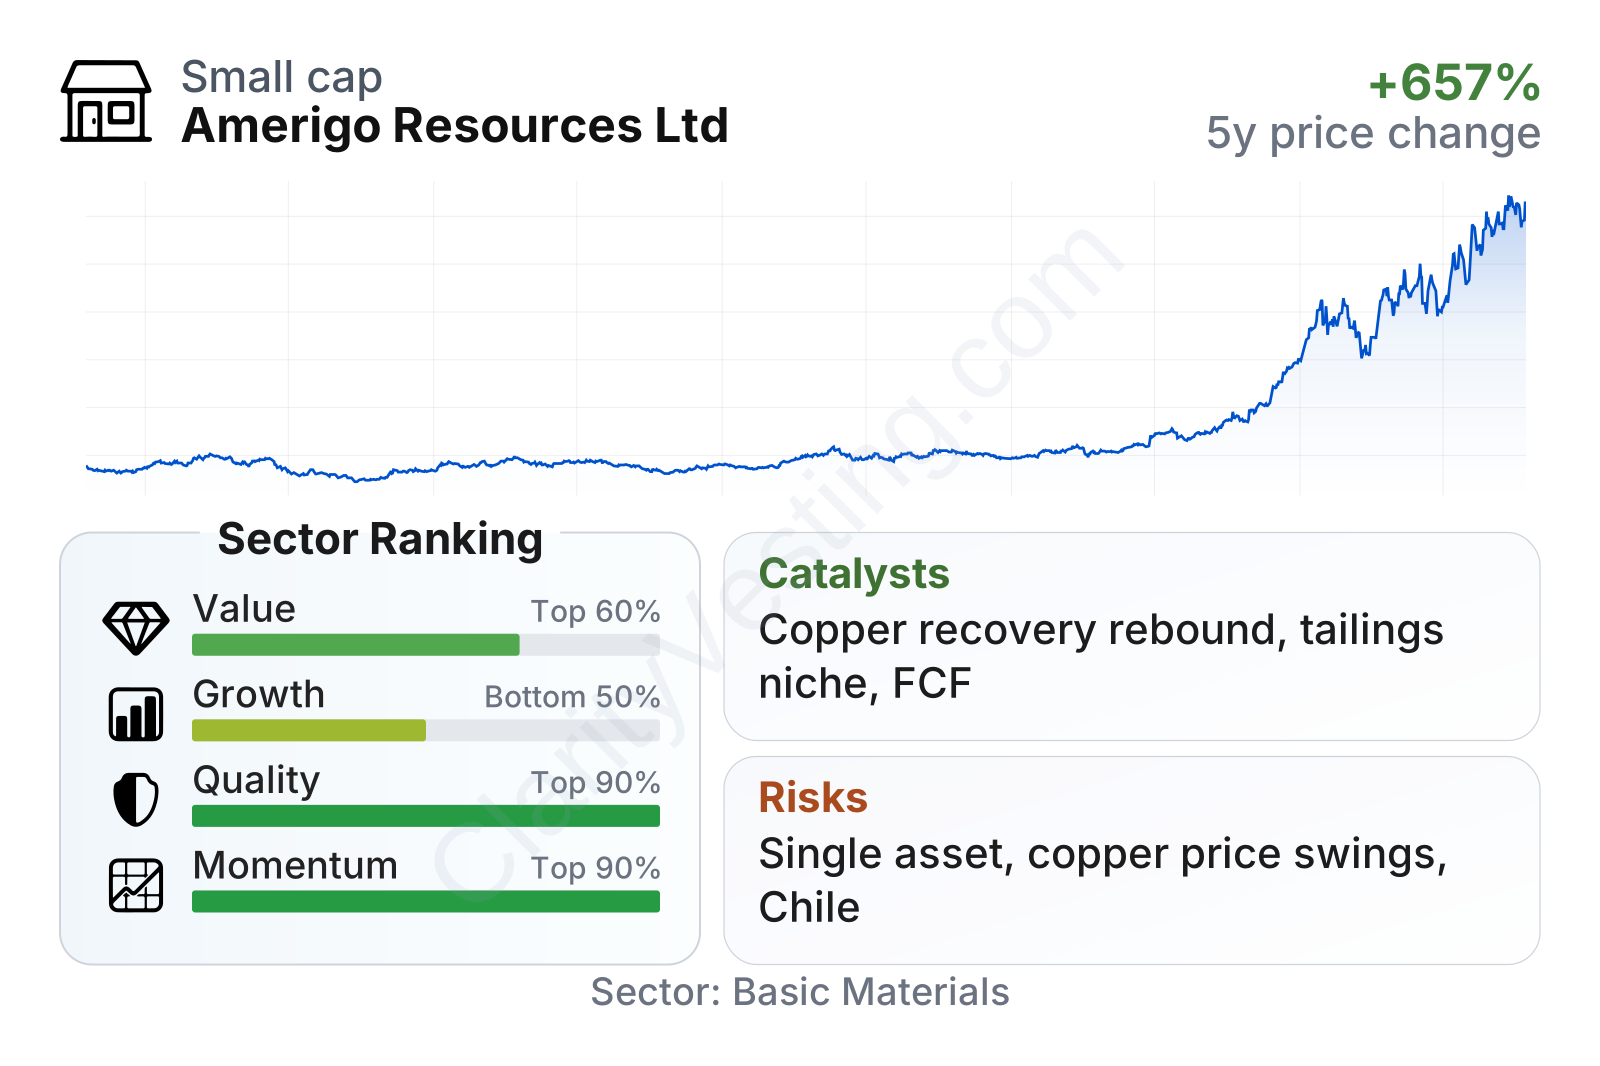
Amerigo is a relatively small public company by market value, which usually brings both opportunity and higher share-price swings. That volatility is visible in its beta above 2. The stock’s recent market performance has been exceptionally strong versus most basic materials peers, but that strength has come after a long period in which earnings and margins were uneven.
The overall metric profile is mixed in an interesting way. Quality indicators are very strong, with returns on capital, returns on assets, operating margin, and interest coverage all standing well above the sector median. Value measures are not stretched on earnings and cash flow, but the price-to-book ratio is far above the sector median, which suggests the market is placing a premium on the company’s current profitability and cash generation rather than on its asset base alone.
Growth indicators are less impressive over a full five-year span. Recent revenue growth has been strong, but longer-term earnings, book value, and free cash flow trends have been choppy. In other words, the company currently looks financially efficient, but not consistently smooth through the cycle.
Growth
Amerigo operates in a sector with favorable long-term fundamentals. Copper demand is widely supported by grid investment, electrification, renewable power systems, electric vehicles, and broader infrastructure needs. Supply growth is harder to deliver because new mines are expensive, slow to permit, and often face political or technical challenges. A company that can increase metal recovery from existing mining waste sits in a niche that fits well with this backdrop.
The company’s strategy also makes practical sense. Recovering copper from tailings can be economically attractive when copper prices are supportive and plant recoveries improve. It is also easier to explain from a sustainability perspective than opening a brand-new mine, because it extracts additional value from material already disturbed by prior mining activity.
Revenue growth has been volatile, which is normal for a commodity-linked business, but the direction improved sharply after the downturn in 2023. The latest annual growth rate is far above the sector median, showing how quickly results can rebound when operations and pricing align. That said, the five-year pattern still reflects a cyclical company rather than a steady compounder.
Cash generation tells a similar story. Free cash flow dropped heavily from earlier highs, briefly turned negative, and then recovered strongly. The latest trailing free cash flow level is solid for a company of this size and supports the view that the business can generate meaningful cash when conditions are favorable. This matters because Amerigo has emphasized capital returns and balance-sheet discipline in recent years.
A notable catalyst has been the stronger earnings recovery visible in 2024 and 2025, helped by firmer copper conditions and improved profitability at MVC. Another important longer-term driver is Amerigo’s relationship with El Teniente’s tailings streams: if throughput and recovery remain reliable, the company can continue to benefit from a very specific niche within copper production without taking on the full burden of developing a new mine.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


