Stock Analysis · Antero Resources Corp (AR)
Overview
Antero Resources is a U.S. natural gas and natural gas liquids producer. The company develops wells primarily in the Appalachian Basin, with a large position in the Marcellus Shale and the Utica Shale. In simple terms, it drills for gas-rich resources, brings them to market, and benefits from both the volume it produces and the prices it receives for those commodities.
The business is more concentrated than that of a large integrated energy company. Antero is mainly an upstream producer, which means its results are driven mostly by production volumes, realized commodity prices, hedging, and the cost of drilling and completing wells. A notable part of its business model is its exposure to natural gas liquids such as ethane, propane, and butane, which helps diversify revenue beyond dry natural gas alone.
Based on recent annual reporting, Antero’s revenue mix is centered on commodity sales and can be summarized approximately as follows:
- Natural gas sales: roughly 45% to 55% of total revenue, depending on market prices and hedge effects.
- Natural gas liquids sales: roughly 35% to 45% of total revenue; this includes products such as ethane, propane, isobutane, normal butane, and natural gasoline.
- Oil sales: typically 0% to 5% of total revenue, a much smaller contributor than gas and liquids.
- Hedging and other revenue items: these can materially lift or reduce reported revenue in certain periods, so the exact mix can shift from year to year.
Antero’s operating footprint is relatively focused, but that focus comes with scale inside its niche. The company has built a position around liquids-rich Appalachian production, access to export-linked markets for liquids, and a drilling inventory that management has presented as long-lived and highly economic when commodity prices are supportive.
The longer-term pattern in the income flow shows how cyclical this business can be. Revenue and profits surged in the strong commodity environment of 2022, weakened sharply in 2023 and 2024 as pricing softened, and then improved again in 2025. That swing matters because it highlights both Antero’s operating leverage and the dependence of earnings on energy prices rather than on steady, predictable demand alone.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas E&P | |
| Market Cap ⓘ | $11.54B | |
| Beta ⓘ | 0.54 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 10.79 | 15.44 |
| P/B Ratio ⓘ | 1.37 | 1.73 |
| FCF Yield ⓘ | 12.22% | 8.20% |
| Dividend Yield ⓘ | N/A | 3.59% |
| EBIT / EV ⓘ | 10.12% | 7.46% |
| PEG ⓘ | 0.45 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 12.60% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | -3.87% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | -25.01% | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | 6.07% | 6.07% |
| Margin Growth (5Y Trend) ⓘ | 20.23% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | -5.29% | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | -2.48% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.33% | 11.40% |
| ROA (Latest) ⓘ | 7.70% | 6.06% |
| ROIC (5Y Median) ⓘ | 4.79% | 10.30% |
| ROA (5Y Median) ⓘ | 1.44% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | 2.93 | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | 7.23 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 1.93 | 1.08 |
| Net Debt / Assets ⓘ | 30.30% | 17.29% |
| EBITDA / Interest ⓘ | 20.80 | 9.64 |
| Operating Margin (Latest) ⓘ | 28.05% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 11.19% | 20.39% |
| Debt to Equity (Latest) ⓘ | 55.49% | 54.76% |
| Profit Margin (Latest) ⓘ | 18.75% | 8.82% |
| Free Cash Flow (Latest) ⓘ | $1.41B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +31.62% | +67.38% |
| 12M Return (excl. last month) ⓘ | +15.21% | +49.19% |
| 6M Return ⓘ | +1.44% | +7.07% |
| Price vs. 200-Day MA ⓘ | +0.62% | +9.56% |
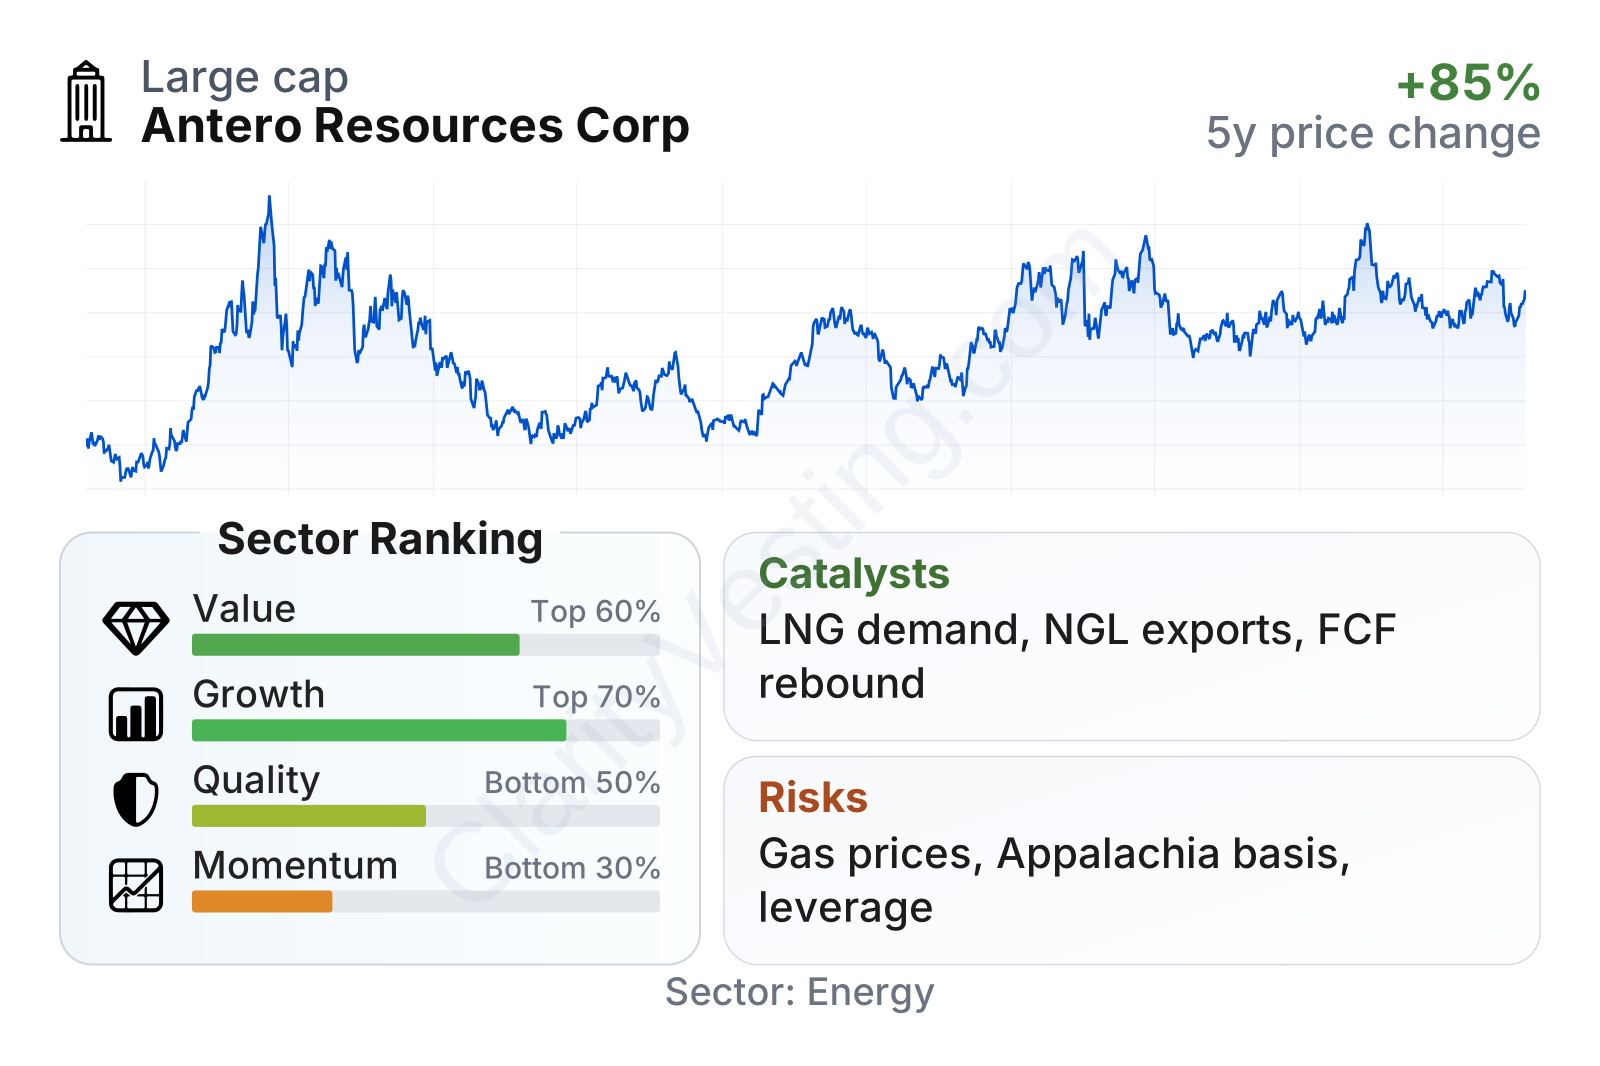
Antero sits in the mid-to-large range among independent U.S. exploration and production companies, with a market value around $10 billion. The table points to a mixed but understandable profile: valuation metrics look relatively favorable versus the sector, profitability is currently strong, while quality and momentum are less convincing. Free cash flow yield stands above the sector median, and both earnings and book value multiples are below median levels, which suggests the market is not assigning a premium valuation despite the recent recovery in margins.
The more cautious reading is that the company’s five-year growth record is uneven and the stock’s recent trading trend has lagged much of the energy group. Beta is low for an energy producer, but that does not remove commodity sensitivity; it mainly means the shares have not moved in lockstep with the broader market as aggressively as some peers.
Growth
Natural gas remains an important fuel in the U.S. power market and an increasingly global commodity through LNG exports. Natural gas liquids also have attractive end markets, including petrochemicals, heating, and export demand. That places Antero in a sector with long-term relevance, especially because Appalachian gas is often among the lower-cost supply sources in North America.
The company’s strategy appears coherent for this setting. Antero has emphasized disciplined capital spending, maintaining a deep inventory of drilling locations, and targeting premium pricing for liquids through diversified marketing arrangements. It also benefits from integration with midstream infrastructure relationships that support transportation, processing, and export access. For a producer in the Appalachian Basin, market access is a meaningful differentiator because regional price discounts can erode realized revenue.
Revenue growth has been volatile rather than linear. After a very strong expansion phase in 2021 and parts of 2022, sales contracted heavily during the commodity reset of 2023. The more recent pattern is better, with a return to positive year-over-year growth through much of 2025 and into 2026, though at more moderate rates than during the peak cycle. That suggests the business is recovering, but not in a straight line.
Free cash flow is one of the strongest points in the recent picture. It fell sharply during the weaker pricing period, then rebounded to roughly $1.8 billion on a trailing basis by early 2026. For a company of this size, that is a meaningful level of cash generation and gives Antero flexibility to reduce debt, repurchase shares, or reinvest selectively. Stronger free cash flow also matters more than headline revenue growth in this industry because commodity producers can grow sales without creating much value if costs and capital intensity rise too fast.
A key catalyst is the continued expansion of U.S. LNG export capacity, which can improve domestic gas demand over time. Another is sustained global demand for LPG and other liquids, an area where Antero has been more differentiated than many gas-focused peers. If gas and liquids prices remain constructive while production stays efficient, operating leverage can be significant because much of the cost base is already in place.
Recent company updates have also continued to emphasize operational execution, shareholder returns, and balance-sheet management rather than aggressive production growth for its own sake. In the current energy market, that disciplined approach is generally more durable than a volume-at-any-cost model.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


