Stock Analysis · Api Group Corp (APG)
Overview
APi Group is a large industrial services company focused on essential safety and infrastructure work. In simple terms, it helps customers install, inspect, maintain, and upgrade systems that protect buildings and support day-to-day operations. Its work includes fire protection, life safety systems, security and communication systems, specialty services, and industrial maintenance. The company serves commercial buildings, healthcare facilities, education sites, data centers, manufacturing plants, and other critical properties where safety and uptime matter.
Its business model is attractive because a meaningful share of work is tied to recurring inspection, repair, and maintenance needs rather than one-time construction activity. That creates more predictable demand than a pure project-based contractor. APi has also grown through acquisitions, building a broad network of operating businesses across North America and other selected markets.
Based on the company’s recent reporting structure, revenue is mainly generated from two operating segments.
- Safety Services: approximately 75% to 80% of revenue. This includes fire protection, life safety, security, and related inspection, service, and installation work.
- Specialty Services: approximately 20% to 25% of revenue. This includes industrial plant services, infrastructure-related work, and other specialty contracting activities.
Within those segments, service, inspection, and monitoring activities are especially important because they tend to repeat regularly and often carry better margins than large installation projects. Over the last several years, the company has also improved the share of revenue converting into gross profit and operating income, even though overhead costs remain significant for a labor-intensive business.
The business has scaled meaningfully since 2021, with revenue roughly doubling over that period and operating income expanding faster than sales. Interest expense has remained material, which shows why debt reduction and disciplined execution still matter for the long-term picture.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $17.28B | |
| Beta ⓘ | 1.58 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 22.29 |
| P/B Ratio ⓘ | 4.99 | 1.98 |
| FCF Yield ⓘ | 3.91% | 6.26% |
| Dividend Yield ⓘ | N/A | 1.92% |
| EBIT / EV ⓘ | 2.89% | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 13.30% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 10.48% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -7.31% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 2.14% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 4.75% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 51.16% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 24.18% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 6.50% | 10.75% |
| ROA (Latest) ⓘ | 3.71% | 5.41% |
| ROIC (5Y Median) ⓘ | 5.84% | 9.37% |
| ROA (5Y Median) ⓘ | 1.95% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 5.35 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 5.35 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 3.33 | 1.39 |
| Net Debt / Assets ⓘ | 30.07% | 19.27% |
| EBITDA / Interest ⓘ | 10.09 | 9.58 |
| Operating Margin (Latest) ⓘ | 6.62% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 5.44% | 10.30% |
| Debt to Equity (Latest) ⓘ | 109.27% | 64.82% |
| Profit Margin (Latest) ⓘ | 4.10% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $676.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +138.40% | +67.77% |
| 12M Return (excl. last month) ⓘ | +7.18% | +12.05% |
| 6M Return ⓘ | -17.09% | 0.00% |
| Price vs. 200-Day MA ⓘ | -4.16% | +0.67% |
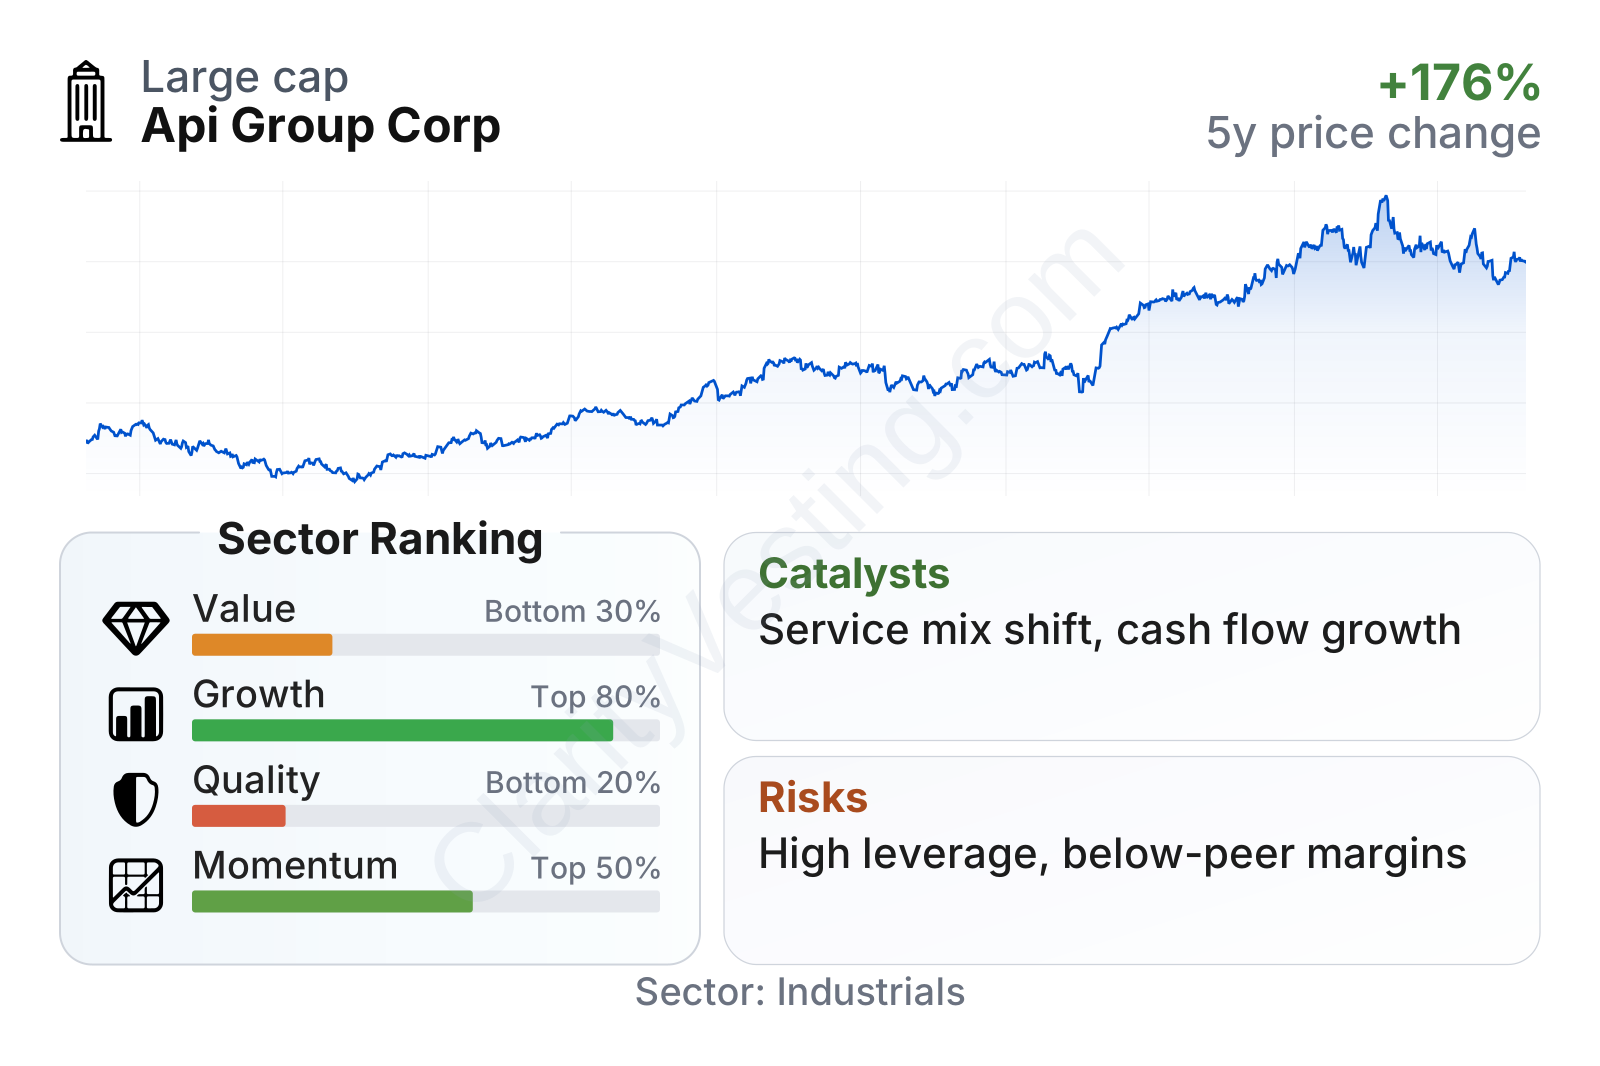
APi Group stands out more for growth than for cheap valuation or top-tier profitability. Its growth profile ranks well within the industrial peer group, supported by double-digit recent revenue growth and very strong free cash flow expansion over five years. By contrast, value and quality measures are weaker: returns on capital and margins remain below sector norms, while leverage is above average. The stock has delivered a strong multiyear share-price gain, but recent momentum has cooled.
APi is now a large-cap industrial company with above-average share-price volatility, as shown by a beta around 1.6. That higher volatility is worth keeping in mind because the business is still in a transition from acquisition-driven expansion toward margin improvement and balance-sheet strengthening.
Growth
APi operates in an area with favorable long-term demand drivers. Fire and life safety systems are not optional for most buildings. They are supported by regulations, inspections, insurance requirements, and the need to protect people and property. That makes the sector structurally resilient, especially for service-heavy providers. In addition, data centers, healthcare facilities, advanced manufacturing, and other mission-critical facilities often require increasingly sophisticated safety and monitoring systems, which can support both volume growth and more technical service work.
The company’s strategy also makes practical sense for future growth. Management has emphasized increasing recurring service revenue, improving margins, and using acquisitions selectively to add density and capabilities. That approach can be powerful in a fragmented market where local scale, technician availability, and customer relationships matter. APi’s broad branch network and installed base can create repeat service opportunities after initial system installation.
Revenue growth was exceptionally strong in 2022 because of acquisitions, then slowed materially in 2023 and parts of 2024 before reaccelerating. More recently, year-over-year growth has returned to the low-teens range, which is ahead of the sector median and suggests the company still has expansion momentum beyond the large step-up from earlier deals.
Free cash flow has improved sharply, moving from slightly negative levels a few years ago to roughly $700 million on a trailing basis. That matters because cash generation gives APi more flexibility to reduce debt, pursue bolt-on acquisitions, and invest in operational improvements without relying as heavily on external financing.
A notable catalyst in recent years has been the company’s continued focus on higher-margin inspection, service, and monitoring work. Another is exposure to end markets that remain active despite uneven construction conditions, particularly mission-critical facilities and regulated safety work. If APi continues to expand service mix while integrating past acquisitions effectively, the gap between revenue growth and earnings growth could narrow in a favorable direction.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


