Stock Analysis · Artivion Inc (AORT)
Overview
Artivion is a medical device company focused on surgery for the heart and major blood vessels. Its products are used mainly in complex cardiac and aortic procedures, where surgeons need implants, preservation services, and specialty devices designed for life-threatening conditions. The company operates in a part of healthcare where demand is supported by aging populations, better diagnosis of structural heart disease, and the need for highly specialized surgical treatment.
Its business is built around a relatively concentrated portfolio rather than a broad hospital supply model. Based on the company’s recent annual reporting and investor materials, revenue comes primarily from three areas:
- Aortic stent grafts: approximately 34% of 2025 revenue. This includes the company’s E-vita platform used in complex aortic repair, especially for aortic arch and thoracic aortic disease.
- On-X products: approximately 31% of 2025 revenue. These are mainly mechanical heart valves and related surgical products used in valve replacement procedures.
- BioGlue and other surgical products: approximately 22% of 2025 revenue. This group includes surgical adhesives and patch-related products used in cardiovascular repair.
- Preservation services: approximately 13% of 2025 revenue. This activity supports the processing and distribution of cardiac and vascular tissues for transplant and surgical use.
The overall revenue mix shows a company that is no longer defined by one legacy product alone. Aortic stent grafts and On-X now represent the largest contributors, which matters because these categories are tied to procedural growth and international expansion rather than only mature domestic demand.
Over the last several years, Artivion has expanded revenue steadily while improving operating profit more clearly than net income. Gross profit has grown, but interest expense has remained a meaningful drag, showing that the business has become stronger operationally while still carrying a capital structure that limits how much of that progress reaches the bottom line.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Devices | |
| Market Cap ⓘ | $1.11B | |
| Beta ⓘ | 1.25 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.06 |
| P/B Ratio ⓘ | 2.39 | 3.08 |
| FCF Yield ⓘ | -0.98% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 1.79% | 0.63% |
| PEG ⓘ | 181.50 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 11.30% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 5.11% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | 46.65% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 5.35% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | 8.68% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | -50.90% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | -2.66% | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.30% | 3.29% |
| ROA (Latest) ⓘ | -0.33% | 3.02% |
| ROIC (5Y Median) ⓘ | 0.49% | 4.75% |
| ROA (5Y Median) ⓘ | -1.87% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 12.48 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 80.64 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 5.76 | 0.99 |
| Net Debt / Assets ⓘ | 30.85% | 5.33% |
| EBITDA / Interest ⓘ | 2.37 | 9.63 |
| Operating Margin (Latest) ⓘ | 5.62% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 1.05% | 7.80% |
| Debt to Equity (Latest) ⓘ | 91.56% | 28.99% |
| Profit Margin (Latest) ⓘ | -0.67% | 3.60% |
| Free Cash Flow (Latest) ⓘ | -$10.91M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +44.09% | +37.48% |
| 12M Return (excl. last month) ⓘ | -38.33% | +20.85% |
| 6M Return ⓘ | -35.80% | +9.73% |
| Price vs. 200-Day MA ⓘ | -31.06% | +4.69% |
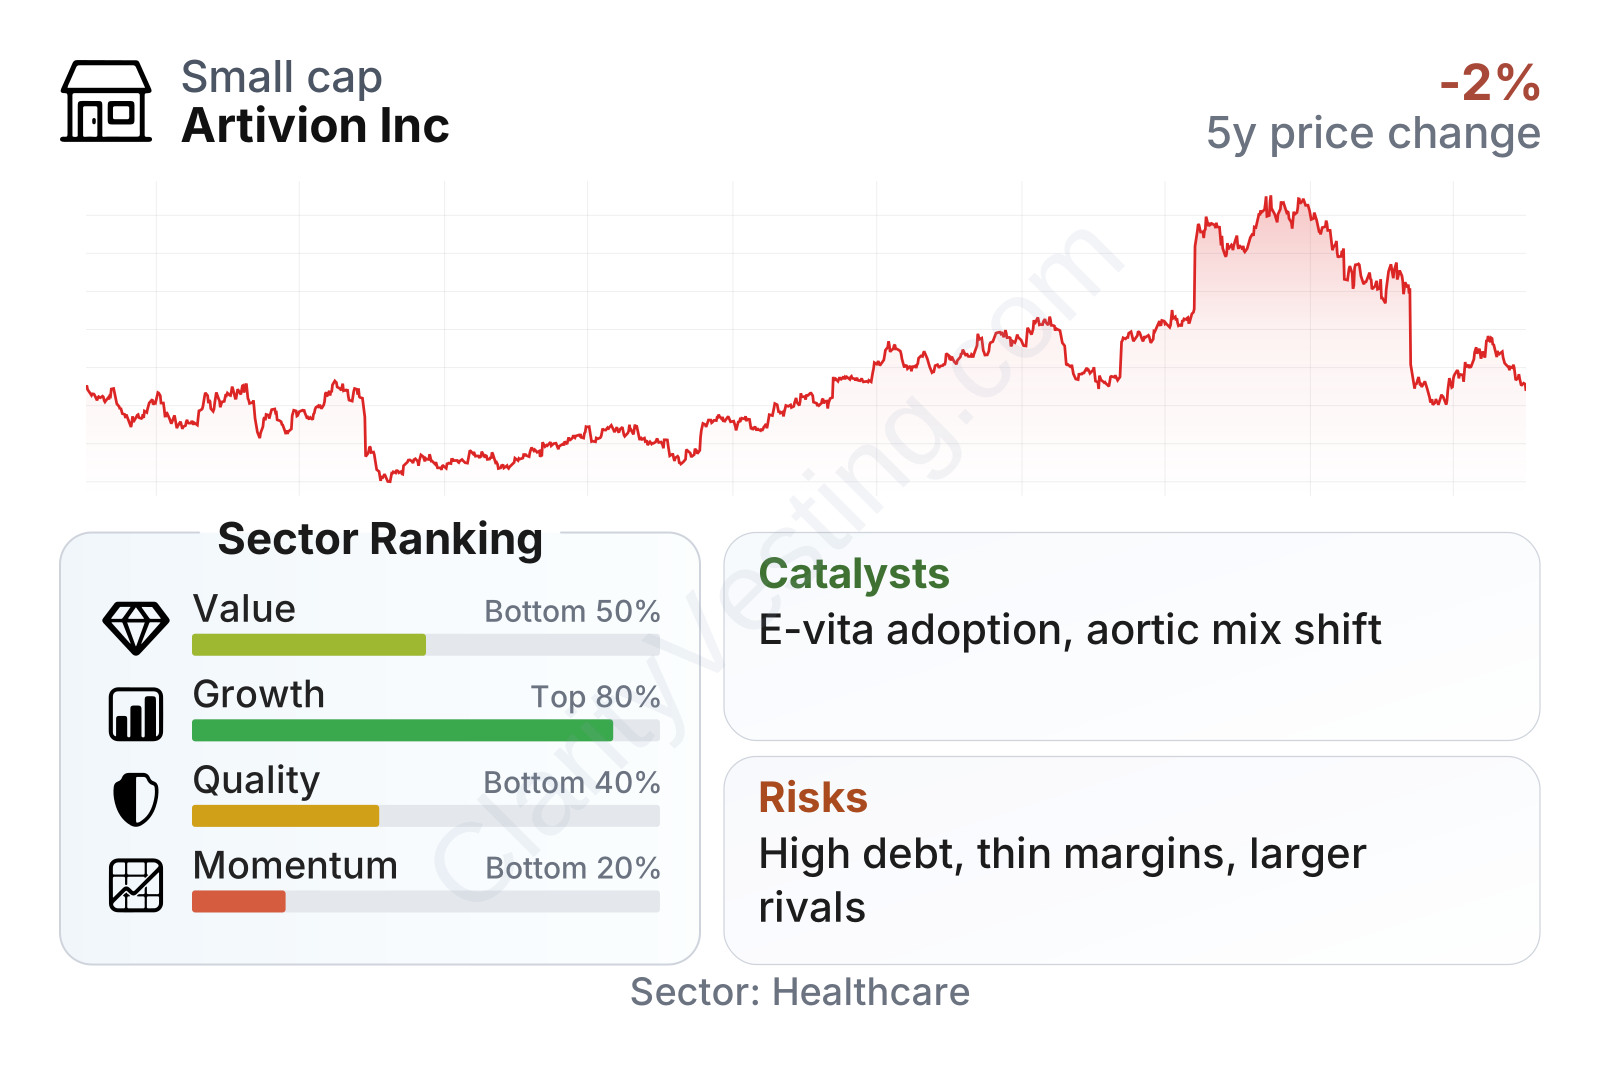
Artivion is a small-cap healthcare company with above-average share price volatility. Its growth profile ranks well versus much of the medical device sector, especially on recent revenue growth and improvement in earnings trends. However, quality metrics remain mixed because leverage is still high, free cash flow is inconsistent, and profitability is not yet firmly established. Valuation measures also look uneven: some balance-sheet-based metrics appear moderate, but earnings-based measures are hard to read because profits remain thin.
The share price history reflects that tension. The stock advanced strongly over the multi-year period, but the recent pullback has been sharp, with performance over the last six to twelve months lagging the broader healthcare group. That kind of movement usually signals that the market is reassessing how durable the company’s margin improvement and growth outlook really are.
Growth
Artivion operates in a healthcare niche with attractive long-term demand drivers. Cardiovascular disease remains a major global health burden, and the company serves procedures that are specialized, difficult to postpone, and often supported by demographic aging. Aortic repair in particular is an area where device innovation and surgeon adoption can create durable growth if clinical results remain strong.
The company’s strategy is broadly coherent. It is concentrating on higher-value products in aortic repair and heart valve surgery, while using its established surgeon relationships and international commercial network to widen adoption. This makes sense because these are markets where specialized training, clinical familiarity, and regulatory approvals can create staying power once a product is accepted in practice.
Revenue growth has been solid in recent years and remained positive into 2026, even if the pace has moderated from stronger periods. Recent year-over-year growth has generally stayed above the sector median, which suggests Artivion is still gaining business faster than many healthcare peers. That is an encouraging sign for a company of this size, particularly in a medical device segment where steady procedural adoption matters more than one-time spikes.
A meaningful catalyst is the company’s aortic stent graft platform, especially the E-vita family. Management has spent several years building this category, and it has become the largest revenue contributor. If procedure adoption continues in the United States and Europe, this segment could remain the main engine of mix improvement because these products are more specialized and strategically important than older legacy lines.
Another supportive factor is the On-X franchise. Mechanical valves are not a high-growth category across the whole market, but On-X has differentiated clinical positioning and remains a sizeable source of recurring procedure-driven revenue. That gives Artivion a second major platform alongside aortic devices rather than relying on one growth product alone.
Cash generation, however, has not yet become consistently strong. Free cash flow has moved between positive and negative territory over the past several years. There has been evidence of improvement at points, but the pattern still shows a business in transition rather than one already producing dependable surplus cash every year. For long-term analysis, that makes future execution more important than headline sales growth alone.
Recent company updates in 2026 have continued to emphasize commercial progress in aortic technologies and ongoing procedure adoption. The main opportunity is straightforward: if revenue keeps compounding while operating discipline holds, Artivion has room to improve margins from a low base, which could have a larger effect on earnings than on sales.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


