Stock Analysis · Adlai Nortye Ltd (ANL)
Overview
Adlai Nortye Ltd is a clinical-stage biotechnology company focused on cancer treatments. Its work centers on developing targeted therapies and immuno-oncology medicines, especially for solid tumors, with operations and partnerships spanning China and international markets. This is not a mature pharmaceutical business with broad commercial sales. It is primarily a drug-development company whose value depends on clinical progress, licensing activity, and its ability to move candidates through trials.
For now, revenue appears limited and uneven, which is common for biotech companies at this stage. Based on recent annual reporting patterns, the company’s revenue has come mainly from collaboration or licensing-related arrangements rather than recurring product sales. That means annual revenue can swing sharply depending on milestone timing and deal structure.
The revenue mix is therefore best understood as follows:
- Collaboration and licensing revenue: typically the main source when present, and in some reported periods effectively close to 100% of total revenue. This can include upfront payments, milestone recognition, or other partner-related income tied to development agreements.
- Product revenue: currently minimal or none in the latest reported annual pattern, meaning the business is not yet supported by a broad, steady commercial base.
- Other income: may include smaller non-core items such as grants, interest, or accounting-related items, but these do not appear to be a primary driver of the business model.
That business profile matters for long-term analysis: Adlai Nortye is essentially being assessed on the future potential of its pipeline rather than on the stability of today’s sales.
The operating picture also shows a familiar biotech pattern: research and development is the largest cash use, far above administrative costs, while revenue has been inconsistent. There has been a visible reduction in operating expenses from the 2023 peak into 2024 and 2025, which suggests tighter spending discipline, but the company is still loss-making and remains dependent on pipeline progress.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.03B | |
| Beta ⓘ | 1.10 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.06 |
| P/B Ratio ⓘ | 1.17 | 3.08 |
| FCF Yield ⓘ | -3.12% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | -3.55% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 178.10% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | -40.40% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | -52.29% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.29% |
| ROA (Latest) ⓘ | -15.58% | 3.02% |
| ROIC (5Y Median) ⓘ | N/A | 4.75% |
| ROA (5Y Median) ⓘ | -67.22% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.99 |
| Net Debt / Assets ⓘ | -42.63% | 5.33% |
| EBITDA / Interest ⓘ | N/A | 9.63 |
| Operating Margin (Latest) ⓘ | -159.85% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -680.80% | 7.80% |
| Debt to Equity (Latest) ⓘ | 12.43% | 28.99% |
| Profit Margin (Latest) ⓘ | -124.77% | 3.60% |
| Free Cash Flow (Latest) ⓘ | -$32.17M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +20.31% | +37.48% |
| 12M Return (excl. last month) ⓘ | +706.51% | +20.85% |
| 6M Return ⓘ | +99.49% | +9.73% |
| Price vs. 200-Day MA ⓘ | +53.33% | +4.69% |
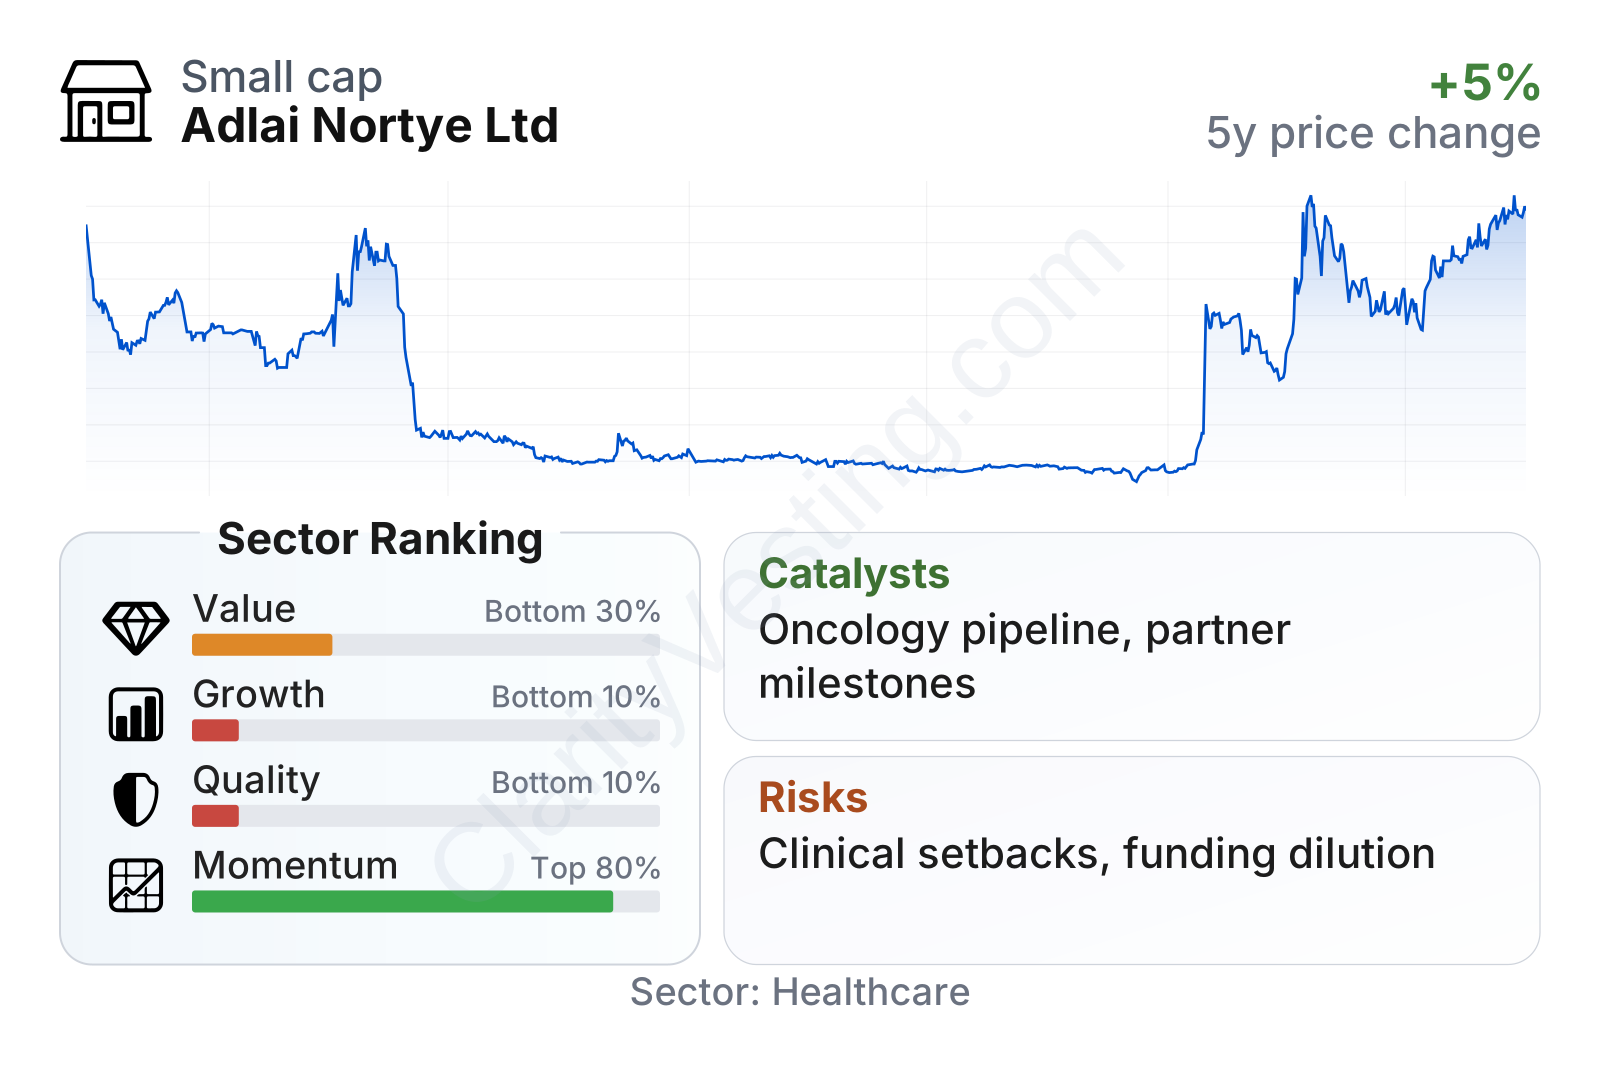
Adlai Nortye is a small-cap biotech with above-average share-price volatility. The stock has been extremely unstable over the past three years, including a deep decline followed by a sharp rebound in 2026. That kind of move usually reflects changing expectations around clinical milestones, financing risk, and strategic developments rather than steady business execution.
The metrics table paints a mixed picture. On valuation, the shares look optically inexpensive on book value compared with the healthcare sector median, but standard earnings-based measures are not very useful because the company remains unprofitable and free cash flow is still negative. On quality and growth factors, the company ranks near the bottom of the sector, which is largely explained by persistent losses, negative returns on assets, and a weak multiyear record in per-share value creation. Momentum is the clear exception: recent share performance has been far stronger than the sector, showing that market sentiment has improved materially even though underlying fundamentals are still early-stage.
Growth
Biotechnology remains a structurally growing sector because cancer treatment continues to attract major research spending, partnership activity, and regulatory attention. Oncology is one of the largest and most active areas in drug development, and companies with differentiated assets can create significant value if clinical data are strong. In that sense, Adlai Nortye operates in an attractive segment of healthcare.
The company’s strategy also makes sense for a smaller biotech: focus resources on a limited set of oncology candidates, seek development partnerships, and control costs while trying to generate important trial readouts. This is a realistic model for a company of its size because it does not require building a full global commercial infrastructure before the science is proven.
A major catalyst is the pipeline itself. In companies like Adlai Nortye, value can change quickly when there is meaningful news on trial enrollment, efficacy, safety, regulatory interactions, or licensing deals. Recent market action suggests investors are paying closer attention again, likely because expectations around one or more pipeline programs have improved or financing concerns have eased.
Cash burn remains important, but the recent trend is somewhat less severe than before. Free cash flow is still negative, yet losses have narrowed from earlier levels, which indicates management has made progress in reducing spending pressure. That does not remove execution risk, but it does improve flexibility if the company can continue advancing programs without sharply increasing its burn rate.
Another encouraging sign is that annual net loss and operating loss improved noticeably after 2023, while research spending remained substantial. In practical terms, Adlai Nortye appears to be trying to preserve the core of its development engine while trimming the broader cost base. For a pre-commercial biotech, that is usually a healthier direction than cutting research too aggressively.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


