Stock Analysis · AnaptysBio Inc (ANAB)
Overview
AnaptysBio is a biotechnology company focused on developing antibody-based medicines, mainly for inflammatory and immune-related diseases. In simple terms, it tries to create targeted drugs that can block specific biological pathways involved in conditions such as asthma, atopic dermatitis, and other immune system disorders. Like many biotech companies at this stage, its value depends less on a broad portfolio of marketed products and more on the progress of its drug candidates, licensing agreements, and milestone payments tied to partnerships.
The business model is built around internal drug development and collaboration deals with larger pharmaceutical companies. That means revenue can be uneven from year to year because it often depends on payments received after achieving development, regulatory, or commercial milestones rather than on recurring product sales.
Based on the latest available annual results, the main revenue sources appear to be:
- Collaboration and license revenue: approximately 100% of total revenue. This includes upfront payments, milestone payments, and recognized revenue from research and development partnerships.
- Direct product sales: 0% disclosed as a meaningful recurring source in the latest public filings.
This concentration is important. In 2025, total revenue rose sharply to roughly $235 million after being much lower in earlier years, showing how dependent reported performance can be on deal activity and milestone timing rather than on a stable commercial base.
The financial picture has improved dramatically from the heavy operating losses seen in 2021 through 2024. Revenue rebounded strongly in 2025 while research spending remained large, which is typical for a clinical-stage biotech. The key takeaway is that AnaptysBio is still primarily a pipeline-and-partnership company, not yet a traditional drug seller with predictable recurring revenue.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.43B | |
| Beta ⓘ | 0.45 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 25.42 |
| P/B Ratio ⓘ | 163.48 | 3.08 |
| FCF Yield ⓘ | 1.26% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | 6.56% | 0.56% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 23.50% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 34.27% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -20.29% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -45.02% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.17% |
| ROA (Latest) ⓘ | 58.42% | 2.98% |
| ROIC (5Y Median) ⓘ | -27.14% | 4.56% |
| ROA (5Y Median) ⓘ | -20.54% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 1.51 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 1.48 | 1.00 |
| Net Debt / Assets ⓘ | 42.83% | 5.06% |
| EBITDA / Interest ⓘ | 1.10 | 9.55 |
| Operating Margin (Latest) ⓘ | 37.76% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -104.23% | 7.33% |
| Debt to Equity (Latest) ⓘ | 2546.89% | 26.68% |
| Profit Margin (Latest) ⓘ | 246.96% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $18.07M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +310.88% | +51.61% |
| 12M Return (excl. last month) ⓘ | +277.94% | +19.90% |
| 6M Return ⓘ | -10.18% | +10.10% |
| Price vs. 200-Day MA ⓘ | -3.55% | +6.44% |
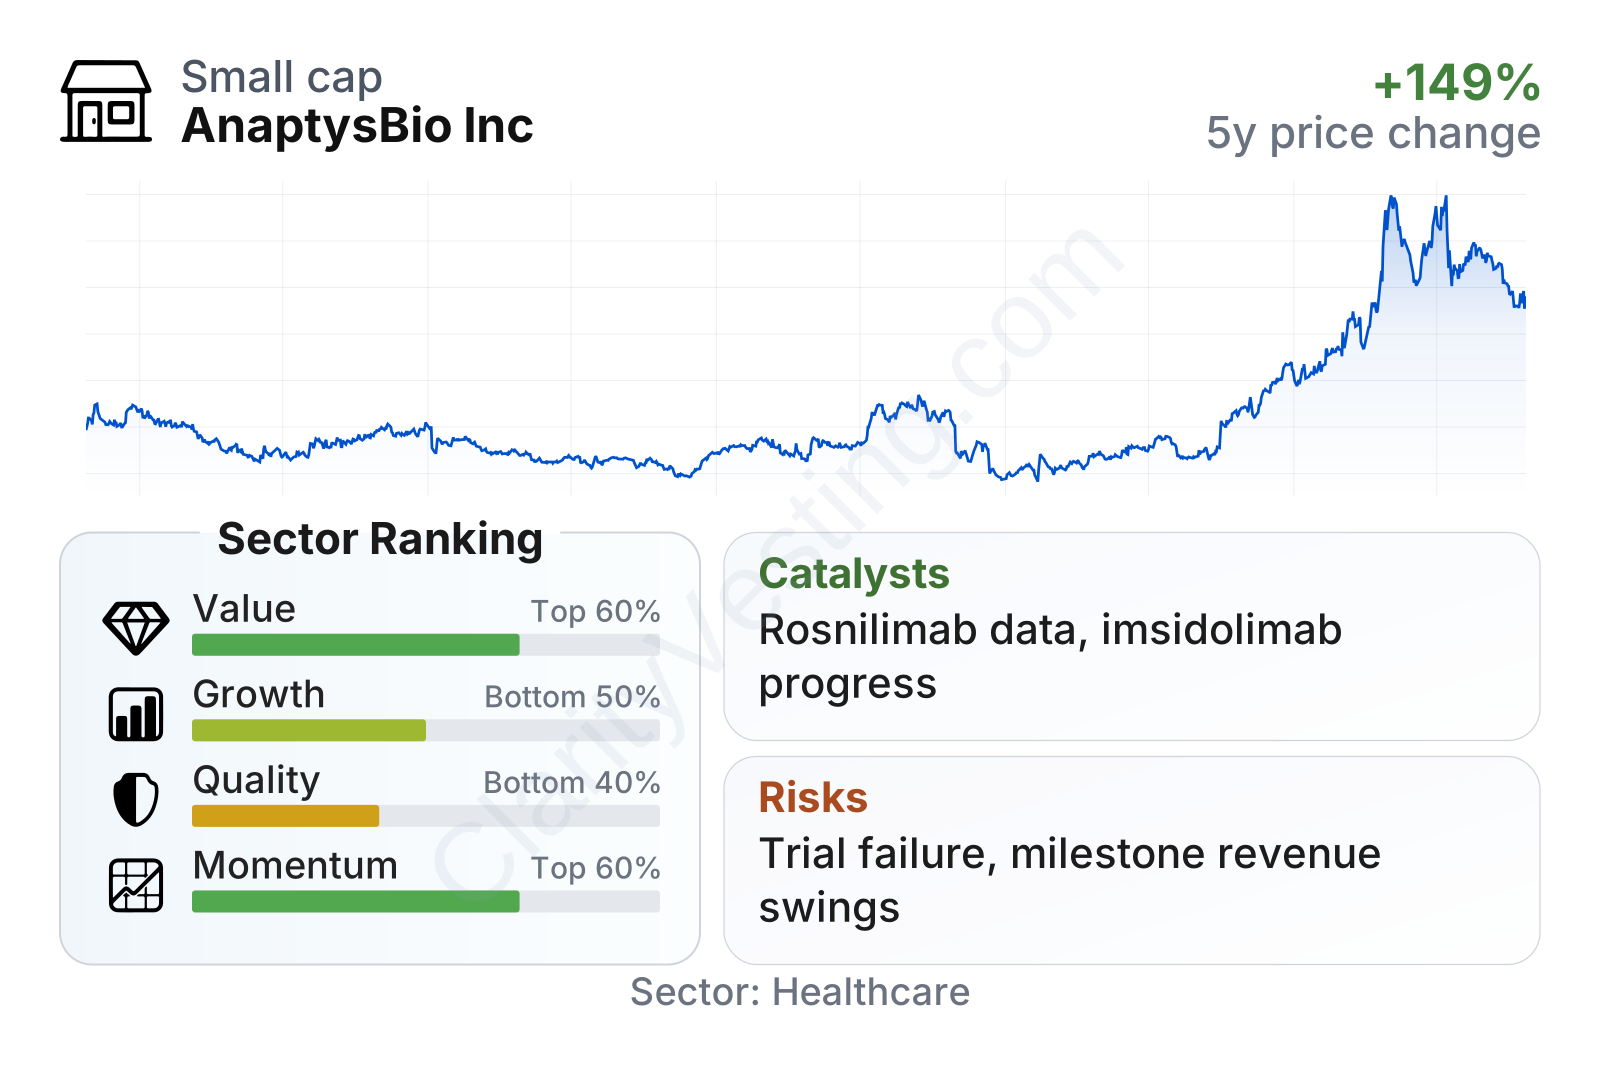
AnaptysBio is a small-to-mid-sized biotech by market value, with unusually strong recent stock momentum and a low beta, meaning its recent trading pattern has been less correlated with broader market swings than many stocks. The factor summary is mixed: value looks acceptable relative to parts of the biotech sector, momentum is very strong, but growth and quality rankings are weaker because the business still shows the uneven economics common in development-stage biotechnology.
One important point is that some headline ratios can look extreme for biotech companies after licensing gains or accounting shifts. For AnaptysBio, very high price-to-book and unusual profitability readings should be read carefully because they may reflect a narrow equity base and milestone-driven earnings rather than a mature, repeatable profit engine.
Growth
Biotechnology remains a structurally growing sector because large drugmakers continue to look for new immune, inflammation, and rare disease assets to replenish their pipelines. Within that broader market, antibody therapeutics are still a major area of interest, especially when they target diseases with large patient populations and clear unmet need. That gives AnaptysBio exposure to an attractive part of healthcare, even though the path from clinical data to durable economics is long and uncertain.
AnaptysBio’s strategy makes sense for a company of its size. Rather than trying to build a full commercial infrastructure too early, it has leaned on partnerships and milestone economics while advancing selected internal programs. This approach can reduce some commercialization burden and spread development risk, but it also means growth can come in bursts instead of steadily.
Revenue growth has been highly volatile, which is normal for collaboration-driven biotech businesses. Still, the broader trend over the past few years shows that the company has been able to convert pipeline progress and business development activity into meaningfully higher reported revenue than in the low point of 2022 and 2023. The latest year-over-year increase is well above the sector median, although that number should not be treated as a stable recurring growth rate.
Cash generation also improved materially. Free cash flow was deeply negative in earlier periods and has recently turned positive on a trailing basis. That matters because it suggests the company is not relying only on optimism around clinical programs; it has also recently shown an ability to bring in enough cash to offset a substantial part of its research spending. For a biotech company, this is a meaningful improvement in financial flexibility.
A major catalyst is the company’s late-stage and mid-stage pipeline in immune-mediated diseases, particularly programs that could generate important clinical data, partnership payments, or broader strategic interest if results are strong. Recent company updates have highlighted progress in key assets such as imsidolimab and rosnilimab, and the market’s strong reaction over the past year suggests that expectations around future readouts and business-development potential have increased significantly. In this type of company, one good trial result can reshape the entire earnings outlook.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


