Stock Analysis · Amentum Holdings Inc (AMTM)
Overview
Amentum Holdings Inc is a government-focused engineering and technical services company. It supports complex missions for U.S. federal agencies and allied governments, with work that ranges from operating secure facilities and maintaining critical infrastructure to providing environmental cleanup, logistics, training, data and cyber support, and specialized engineering for defense, intelligence, energy, and civilian programs.
The business is built around long-duration contracts, many of them tied to essential government functions. That usually makes demand steadier than in many commercial industries, but it also means performance depends heavily on contract execution, recompetes, and public-sector budget priorities.
Based on the company’s recent public filings and investor materials, revenue is primarily generated from the following activities:
- Defense and national security services: the largest revenue source, likely representing a majority of total sales. This includes mission support, systems engineering, logistics, sustainment, training, and technical services for military and security customers.
- Energy, environmental, and infrastructure programs: a significant share of revenue, including nuclear cleanup, environmental remediation, facility operations, and engineering support for government-owned sites.
- Intelligence and digital solutions: a smaller but strategically important area covering cyber, data analytics, secure IT, and mission technology services for classified and civilian customers.
- International and allied government work: a modest portion of revenue tied to U.K. and other allied-country contracts, often related to defense, engineering, and technical support.
At a high level, the company’s financial flow shows a low-margin contract services model: revenue is large, direct costs consume most of it, and interest expense remains a meaningful drag on bottom-line earnings. At the same time, operating income and cash generation improved materially after a weaker period, which is important for a company carrying elevated leverage.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Business Services | |
| Market Cap ⓘ | $4.53B | |
| Beta ⓘ | 0.31 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 22.31 | 22.10 |
| P/B Ratio ⓘ | 0.97 | 1.97 |
| FCF Yield ⓘ | 10.71% | 6.38% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 5.96% | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -2.00% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 1.05% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 14.95% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | -20.45% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -2.48% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 25.05% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 4.57% | 10.84% |
| ROA (Latest) ⓘ | 1.80% | 5.41% |
| ROIC (5Y Median) ⓘ | N/A | 9.38% |
| ROA (5Y Median) ⓘ | -0.89% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 6.90 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 11.11 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 3.63 | 1.39 |
| Net Debt / Assets ⓘ | 30.06% | 19.28% |
| EBITDA / Interest ⓘ | 1.56 | 9.58 |
| Operating Margin (Latest) ⓘ | 3.45% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 3.25% | 10.29% |
| Debt to Equity (Latest) ⓘ | 81.47% | 65.48% |
| Profit Margin (Latest) ⓘ | 1.44% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $485.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +61.68% |
| 12M Return (excl. last month) ⓘ | -17.23% | +12.58% |
| 6M Return ⓘ | -34.02% | 0.00% |
| Price vs. 200-Day MA ⓘ | -27.87% | +0.02% |
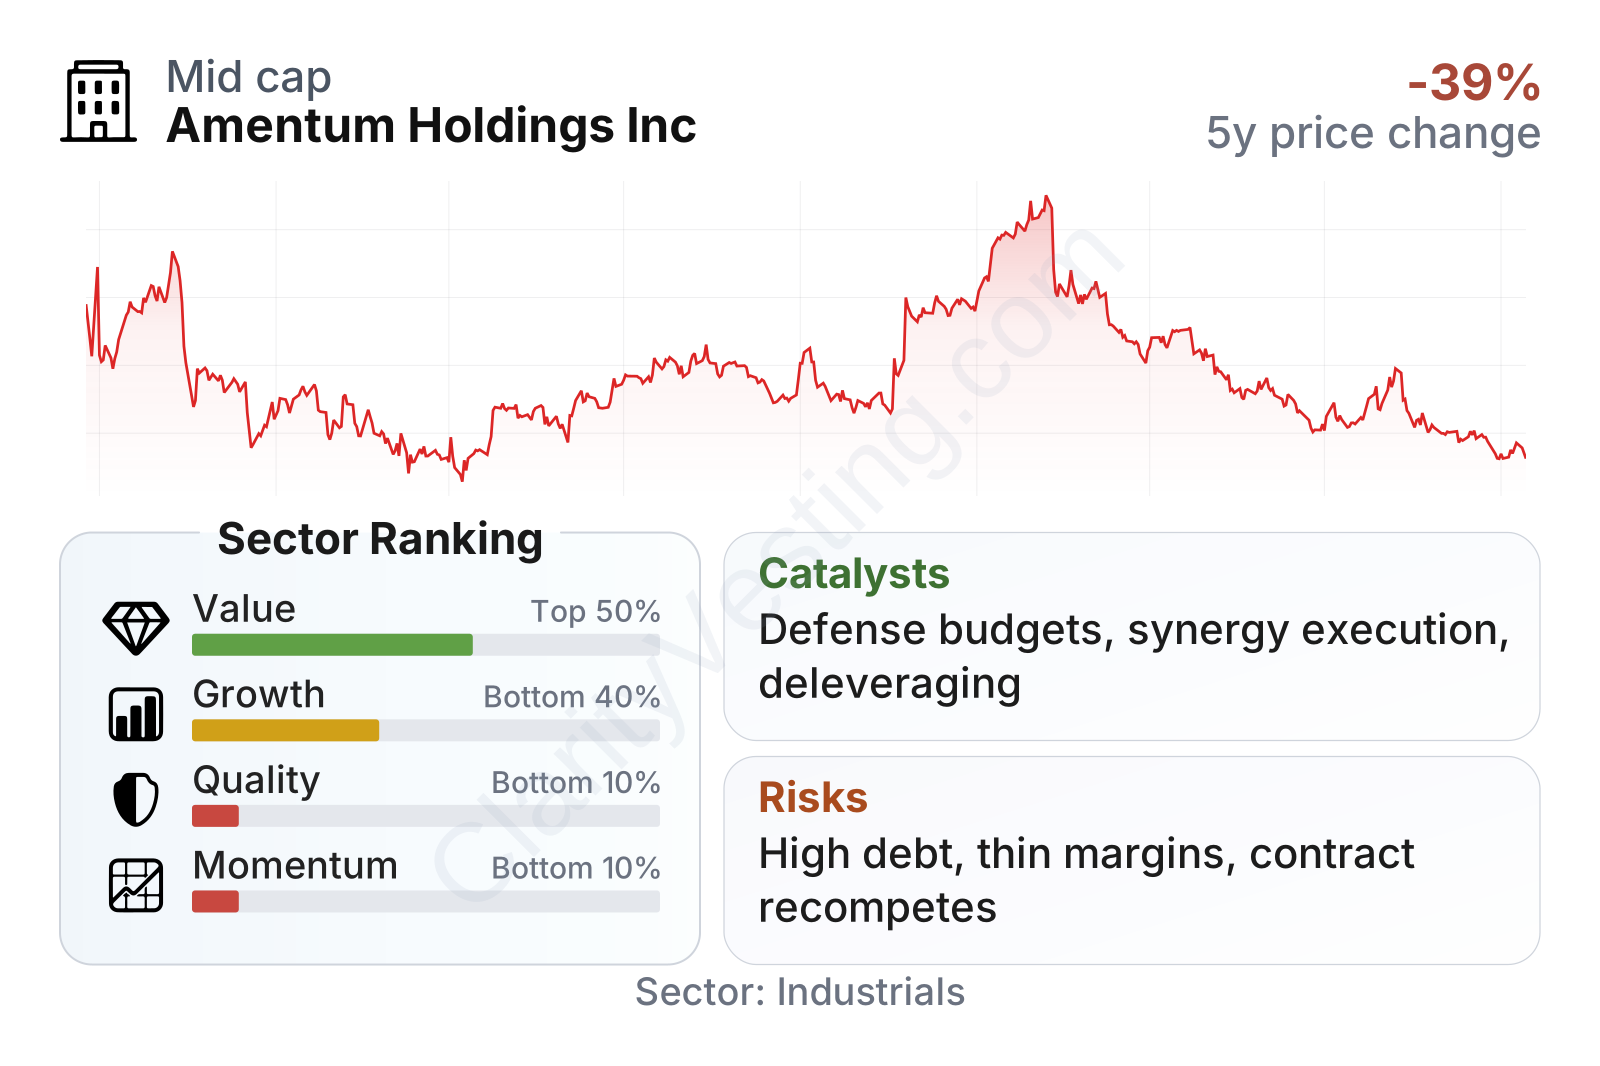
Amentum is a mid-sized industrial services company with a market value in the low single-digit billions. The stock’s volatility has been relatively low versus the broader market, but the recent share-price trend has been weak. In the factor breakdown, valuation looks roughly in line with the sector on earnings and cheaper on book value, while free cash flow yield stands out positively. The weaker side is quality and momentum: profitability remains thin, returns on capital are below sector norms, and leverage metrics are stretched compared with peers.
Growth
Amentum operates in areas with durable long-term demand. Defense modernization, nuclear site management, environmental remediation, cybersecurity, space-related support, and infrastructure resilience are all markets supported by national security priorities and multi-year public spending. That does not guarantee smooth revenue growth every quarter, but it does provide a large addressable market with recurring needs.
The company’s strategy also fits that backdrop. Amentum focuses on work that is difficult to replicate quickly: highly regulated programs, cleared personnel, embedded customer relationships, and technical know-how developed over many years. In government services, these capabilities can matter as much as scale because customers often prioritize past performance, compliance, and reliability over aggressive expansion alone.
Near-term revenue growth has been soft, with year-over-year comparisons still slightly negative in recent quarters. That places Amentum below the sector median on growth metrics. Still, the pattern suggests the rate of decline has moderated from earlier periods, which can matter if contract wins and integration efforts begin to feed into reported sales more consistently.
Cash generation has improved much faster than revenue. Trailing free cash flow moved sharply higher, reaching roughly $450 million to $500 million. That is one of the more encouraging developments in the company’s profile because stronger cash conversion can support debt reduction, interest burden management, and greater financial flexibility even when top-line growth is modest.
A meaningful catalyst is the enlarged scale of the combined platform following recent corporate changes and integration work. A larger contract base can improve bidding reach, allow broader customer coverage, and create opportunities to cross-sell technical, digital, and program-management capabilities. Another potential tailwind is continued U.S. and allied government spending on defense readiness, nuclear security, and mission-critical infrastructure, all areas where Amentum is already established.
Recent company communications have also emphasized backlog, pipeline depth, and synergy execution. For a business like this, those items matter more than short-term consumer-style demand indicators. If the company converts more of its contract opportunities into funded work while keeping costs under control, the path to steadier growth becomes more credible.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


