Stock Analysis · American Tower Corp (AMT)
Overview
American Tower is a real estate investment trust focused on communications infrastructure. In simple terms, it owns and operates sites that wireless carriers, broadcasters, governments, and enterprise customers use to place equipment for mobile networks and data transmission. Its portfolio is centered on cell towers, but it also includes distributed antenna systems, small-cell-related assets, and a growing presence in data centers through CoreSite.
The business model is relatively straightforward: American Tower builds or acquires infrastructure, then leases space on that infrastructure to customers under multi-year contracts. A key feature of this model is that one tower can host several tenants, so adding extra customers often brings high incremental margins. That helps explain why the company has historically produced strong operating profitability and cash generation.
Based on its recent reporting structure, revenue is mainly generated from the following sources:
- Property operations - United States & Canada: approximately 29% of total revenue. This includes leasing space on communications sites in North America, with the major wireless carriers as core customers.
- Property operations - Asia-Pacific: approximately 23% of total revenue. This segment includes tower leasing and related site services across major international markets in the region.
- Property operations - Africa: approximately 16% of total revenue. Revenue comes largely from tower leasing to mobile network operators in fast-growing wireless markets.
- Property operations - Europe: approximately 14% of total revenue. This is mostly recurring lease revenue from telecom infrastructure assets across European markets.
- Property operations - Latin America: approximately 11% of total revenue. This reflects tower rental income and related services in markets with ongoing mobile data expansion.
- Services: approximately 4% of total revenue. This includes site development, zoning, and other support activities tied to customer deployments.
- Data centers: approximately 3% of total revenue. This comes mainly from interconnection and colocation services through CoreSite.
That mix shows a company still dominated by towers, with broad geographic diversification. It also means results are not dependent on a single country, even though the U.S. remains its largest market.
The long-term attraction of this model is that mobile data demand keeps rising while carriers often prefer leasing infrastructure rather than owning every site themselves. American Tower sits between that demand and the physical assets needed to support it.
Over the last several years, revenue has continued to edge upward while gross profit remained strong. Net income has been more uneven because interest expense became a larger burden when borrowing costs rose, but the underlying operating structure still shows a business with substantial recurring rental economics.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Real Estate | |
| Industry | REIT - Specialty | |
| Market Cap ⓘ | $84.60B | |
| Beta ⓘ | 0.89 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.44 | 17.85 |
| P/B Ratio ⓘ | 21.20 | 0.87 |
| FCF Yield ⓘ | 4.68% | 7.30% |
| Dividend Yield ⓘ | 3.93% | 4.83% |
| EBIT / EV ⓘ | 4.02% | 3.78% |
| PEG ⓘ | 1.61 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.70% | 5.35% |
| RPS Growth (5Y CAGR) ⓘ | 2.39% | 6.02% |
| EPS Growth (5Y CAGR) ⓘ | 4.63% | -10.65% |
| BVPS Growth (5Y CAGR) ⓘ | 34.05% | 0.43% |
| Margin Growth (5Y Trend) ⓘ | -1.39% | -0.69% |
| FCF Growth (5Y CAGR) ⓘ | 2.38% | 5.40% |
| DPS Growth (5Y CAGR) ⓘ | 7.66% | 5.07% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 10.71% | 5.69% |
| ROE (Latest) ⓘ | 88.06% | 7.37% |
| ROA (Latest) ⓘ | 5.31% | 2.85% |
| ROIC (5Y Median) ⓘ | 8.22% | 4.26% |
| ROE (5Y Median) ⓘ | 86.50% | 6.04% |
| ROA (5Y Median) ⓘ | 3.55% | 2.45% |
| Net Debt / EBIT (Latest) ⓘ | 8.75 | 7.55 |
| Net Debt / EBIT (5Y Median) ⓘ | 13.53 | 8.26 |
| Net Debt / EBITDA (Latest) ⓘ | 6.17 | 5.26 |
| Net Debt / Assets ⓘ | 68.27% | 37.45% |
| EBITDA / Interest ⓘ | 5.02 | 4.11 |
| Operating Margin (Latest) ⓘ | 45.13% | 33.86% |
| Operating Margin (5Y Median) ⓘ | 38.16% | 37.49% |
| Debt to Equity (Latest) ⓘ | 1209.23% | 88.76% |
| Profit Margin (Latest) ⓘ | 31.08% | 18.94% |
| Free Cash Flow (Latest) ⓘ | $3.96B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +26.72% | +36.33% |
| 12M Return (excl. last month) ⓘ | -5.79% | +4.32% |
| 6M Return ⓘ | +5.09% | -1.74% |
| Price vs. 200-Day MA ⓘ | +4.50% | -1.42% |
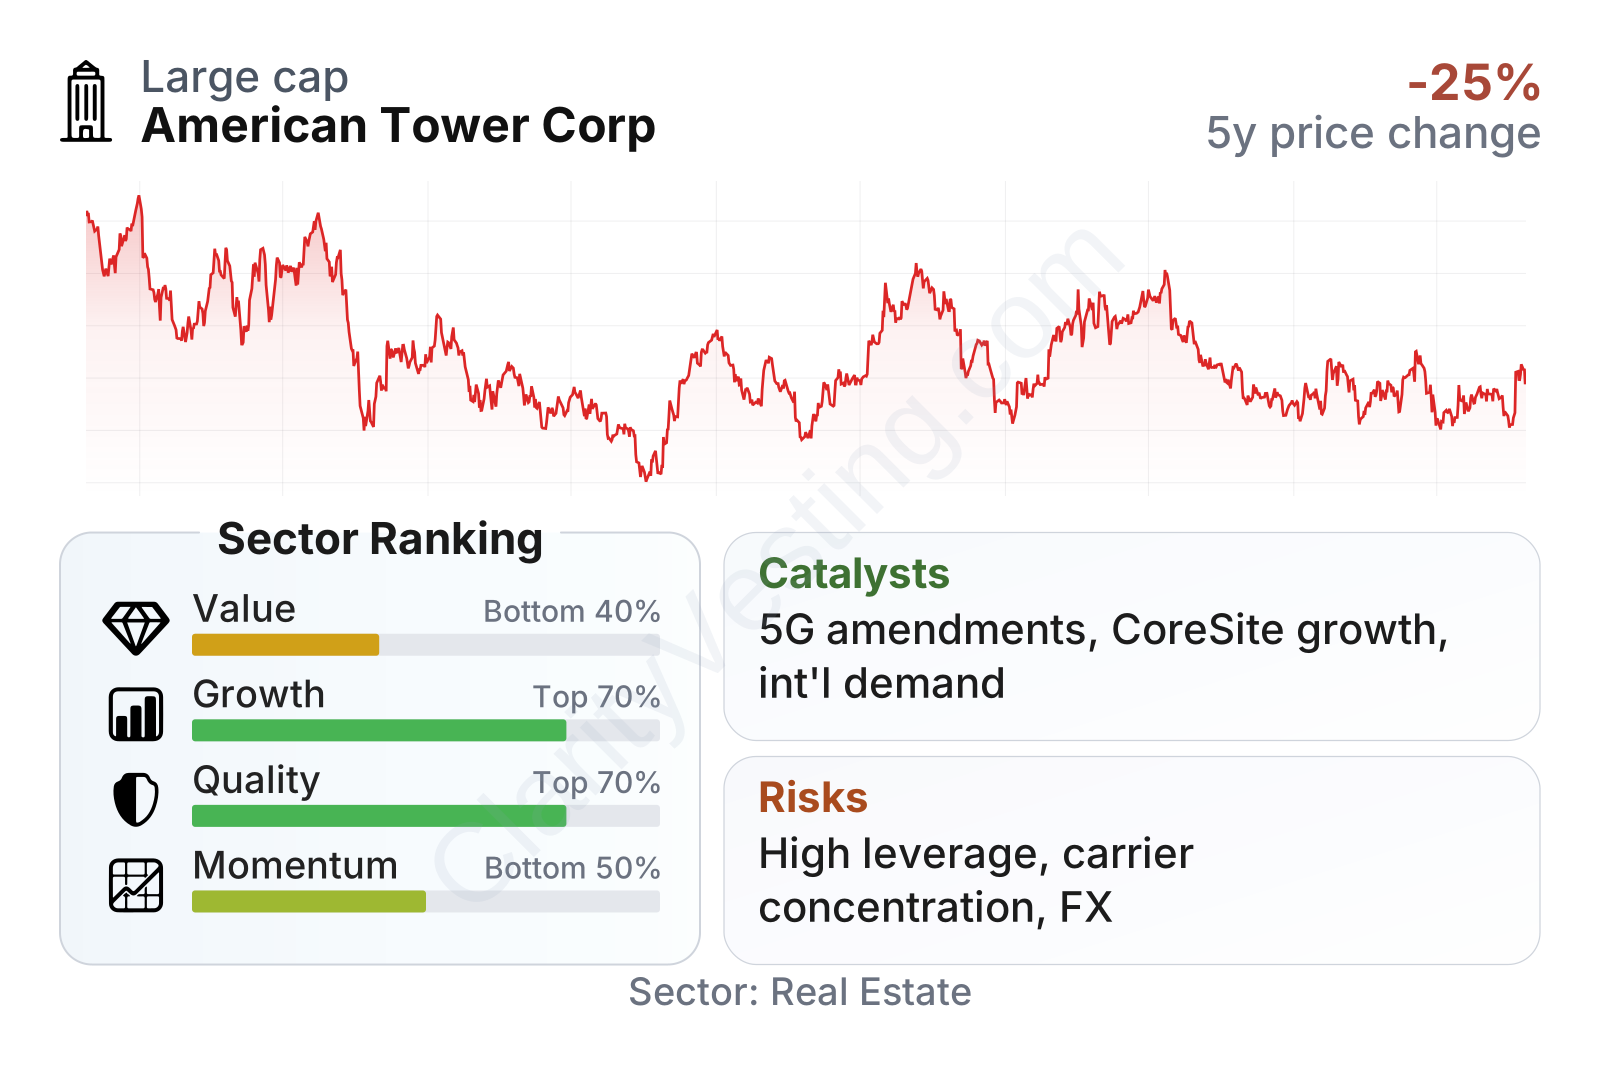
American Tower is a very large company with below-market share price volatility for its sector, but the stock has lagged much of real estate over the last 12 months and over the last three years. On fundamentals, quality remains the strongest area: returns on capital and asset profitability are comfortably above sector medians, and operating margins are strong. Growth is more mixed. Revenue and free cash flow have expanded, but generally at a moderate pace rather than a rapid one. Valuation metrics place the stock in a less attractive part of the sector on simple screens, especially on price-to-book, which is not unusual for asset-heavy infrastructure platforms but still signals that the market is assigning a premium.
Growth
American Tower operates in a sector with clear long-term demand drivers. Mobile data traffic continues to grow, 5G networks still require ongoing equipment deployment, and carriers need dense, reliable coverage. Even when consumer telecom spending looks mature, network operators still need infrastructure upgrades to handle video, cloud applications, and connected devices. That gives tower owners a durable role in the digital economy.
The company’s strategy broadly fits those trends. Its core tower portfolio benefits from recurring leasing revenue, annual contractual escalators in many markets, and the ability to add extra tenants or amendments to existing sites. On top of that, the company has expanded into data centers through CoreSite, which adds exposure to cloud connectivity and enterprise interconnection. That combination gives it two infrastructure themes under one roof: wireless network growth and digital traffic growth.
Revenue per share has moved upward over the last five years, but the slope has been steady rather than steep. That supports the view of American Tower as a compounding infrastructure business with moderate growth characteristics, not a fast-expanding platform.
Dividend per share has also risen consistently, with five-year growth stronger than the sector median. For a REIT, that matters because it suggests operating cash flow has been resilient enough to support regular increases even through a period of higher interest rates and uneven carrier spending.
A meaningful catalyst is the continued buildout of 5G and the broader need for network densification. Carriers may moderate capital spending in some periods, but traffic demand keeps building, and tower amendments can continue even without a dramatic surge in new sites. International markets also remain important because smartphone adoption and data usage still have room to grow in several of American Tower’s regions.
Another favorable point is that the company has recently shown improving profitability after the pressure seen in 2022 and 2023. Lower interest expense in 2025 compared with prior peaks and a rebound in net income suggest that the earnings profile can improve when financing conditions become less hostile and operating leverage reasserts itself.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


