Stock Analysis · Ameriprise Financial Inc (AMP)
Overview
Ameriprise Financial is a diversified financial services company focused on helping individuals and institutions manage money, plan for retirement, protect assets, and invest for the long run. Its business mixes wealth management, asset management, retirement-related services, and insurance-like products. That combination matters because it gives the company several revenue streams tied to client assets, advice, and protection products rather than relying on only one activity.
The largest profit engine is typically its Advice & Wealth Management segment, which serves clients through financial advisors and earns fees from advisory accounts, brokerage activity, cash management, and spread-based income on client cash and banking-related balances. A second major contributor is Asset Management, mainly through Columbia Threadneedle, where Ameriprise earns management and performance fees on investment products used by institutions, advisers, and retail clients. The company also has a meaningful Retirement & Protection Solutions business, which includes annuities, life and disability income insurance, and retirement-related products.
Based on recent company reporting patterns, revenue is best understood through the following broad mix, recognizing that accounting presentation in financial companies can be more complex than in industrial businesses:
- Advice & Wealth Management: approximately 45% to 55% of total operating revenue. This includes advisory fees, brokerage-related revenue, and net investment income connected to client cash and banking activities.
- Asset Management: approximately 20% to 30%. This includes fees earned on mutual funds, separate accounts, institutional mandates, and other managed products.
- Retirement & Protection Solutions: approximately 20% to 30%. This includes annuities, insurance premiums, spread income, and other protection-oriented product revenue.
Ameriprise’s model is built around long-lasting client relationships. That can make revenue more resilient than purely transaction-driven businesses, especially when advisory fees are based on assets under management or administration. At the same time, earnings still move with stock and bond markets because falling asset values can reduce fee income.
The broader operating picture has improved over the last several years, with total revenue rising from roughly $13 billion to nearly $19 billion between 2021 and 2025, while net income has also trended higher despite a dip in 2023. That suggests a business that has been able to grow client assets and recover profitability after more difficult market conditions.
The long-term pattern points to expanding revenue and solid earnings generation, although some yearly line items appear more volatile because financial companies can show accounting movements that do not reflect the underlying client franchise in a simple way. The key takeaway is that Ameriprise has recently combined higher revenue with strong bottom-line performance.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 21, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Asset Management | |
| Market Cap ⓘ | $43.53B | |
| Beta ⓘ | 1.12 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.29 | 12.01 |
| P/B Ratio ⓘ | 8.81 | 1.48 |
| FCF Yield ⓘ | 16.96% | 8.77% |
| Dividend Yield ⓘ | 1.30% | 3.01% |
| EBIT / EV ⓘ | 12.19% | 8.31% |
| PEG ⓘ | 1.42 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 6.10% | 6.70% |
| RPS Growth (5Y CAGR) ⓘ | 15.21% | 12.35% |
| EPS Growth (5Y CAGR) ⓘ | 10.12% | -0.27% |
| BVPS Growth (5Y CAGR) ⓘ | 8.26% | 4.83% |
| Margin Growth (5Y Trend) ⓘ | -7.17% | -4.16% |
| FCF Growth (5Y CAGR) ⓘ | 26.32% | 4.69% |
| DPS Growth (5Y CAGR) ⓘ | 9.80% | 8.82% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 32.12% | 9.49% |
| ROE (Latest) ⓘ | 71.40% | 14.02% |
| ROA (Latest) ⓘ | 2.18% | 1.53% |
| ROIC (5Y Median) ⓘ | 33.08% | 7.80% |
| ROE (5Y Median) ⓘ | 59.92% | 12.09% |
| ROA (5Y Median) ⓘ | 1.91% | 1.28% |
| Net Debt / EBIT (Latest) ⓘ | -0.66 | 0.88 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.51 | 0.73 |
| Net Debt / EBITDA (Latest) ⓘ | -0.57 | 0.71 |
| Operating Margin (Latest) ⓘ | 24.69% | 23.37% |
| Operating Margin (5Y Median) ⓘ | 26.62% | 24.29% |
| Debt to Equity (Latest) ⓘ | 117.26% | 59.34% |
| Profit Margin (Latest) ⓘ | 20.67% | 26.65% |
| Free Cash Flow (Latest) ⓘ | $7.38B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +42.96% | +73.29% |
| 12M Return (excl. last month) ⓘ | +3.68% | +18.35% |
| 6M Return ⓘ | +7.29% | +3.24% |
| Price vs. 200-Day MA ⓘ | -1.86% | +2.17% |
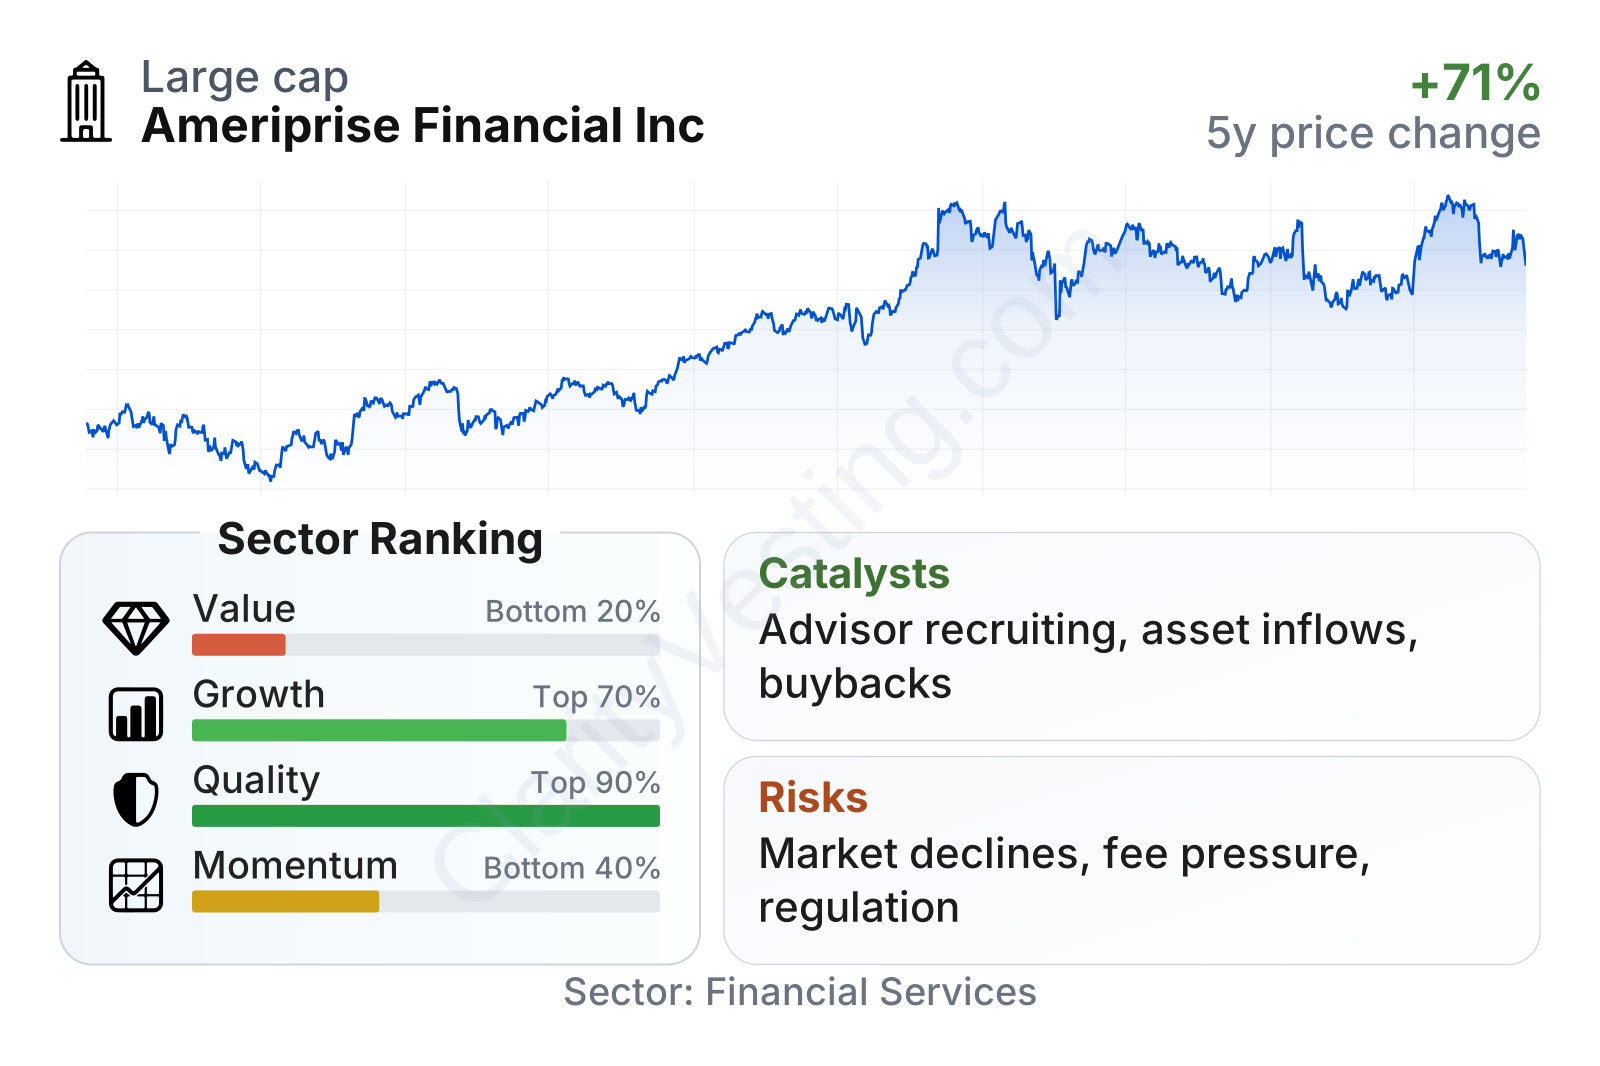
Ameriprise stands out for quality and long-term compounding more than for conventional cheapness. The business ranks well above much of the financial sector on profitability and capital efficiency, with very strong returns on equity and returns on invested capital. Growth metrics are also healthy over a five-year period, especially for revenue per share, earnings per share, free cash flow, and book value per share. By contrast, the recent share-price trend has been softer than the sector, and the valuation profile looks mixed: earnings-based multiples are not demanding, but book-value-based valuation is unusually high for a financial stock.
Ameriprise is also a large company by market value, with moderate share-price sensitivity to the broader market. Its dividend yield is modest, so the main attraction is not income alone but the combination of profitability, buybacks, and long-term earnings growth.
Growth
Ameriprise operates in parts of financial services that benefit from durable structural trends. An aging population, the shift from employer-managed pensions toward self-directed retirement savings, and the growing need for personal financial advice all support demand for wealth management and retirement planning. In addition, asset management tends to grow over time as household financial assets rise, although this does not happen in a straight line.
The company’s strategy is coherent for this environment. Ameriprise has built a large advisor network, which helps it gather assets and cross-sell investment and protection products. That advisory relationship can be particularly valuable because clients with long-term plans often keep multiple products with the same provider. This creates a flywheel: advice leads to asset gathering, assets generate recurring fees, and scale helps support technology, compliance, and brand strength.
Earnings have shown a strong multi-year climb, moving from the low $20s per share in 2021 to around $39 in 2025, with 2026 continuing at a high level on a trailing basis. That progression matters because it suggests growth has not depended only on market appreciation; it also reflects business expansion, margin discipline, and share repurchases.
Book value per share has also trended upward over time, despite some volatility earlier in the period. That is a useful sign for a financial company because it indicates that shareholder value has continued to build while the firm also returns capital through dividends and buybacks.
A visible catalyst is the company’s ability to keep attracting client assets into advisory and managed accounts. Higher asset levels can lift fee revenue without requiring cost growth at the same pace. Another positive factor is Ameriprise’s strong cash generation, which gives it room for continued capital returns and reinvestment. Recent operating momentum has also been helped by favorable market levels, which generally support fee-based businesses like wealth and asset management.
Recent company updates have also highlighted ongoing advisor recruiting and productivity efforts, which are important because attracting experienced financial advisors can bring immediate client assets and recurring revenue. In this industry, distribution strength is often one of the most powerful growth levers, and Ameriprise remains well positioned on that front.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


