Stock Analysis · Antero Midstream Partners LP (AM)
Overview
Antero Midstream Partners LP, now operating as Antero Midstream, is a midstream energy company. In simple terms, it owns and runs the infrastructure that helps move and handle natural gas and water for energy production. Its assets are concentrated in the Appalachian Basin, especially in West Virginia and Ohio, and they are built primarily to serve Antero Resources, one of the largest natural gas producers in that region.
This business model is different from an oil and gas producer. Antero Midstream does not mainly make money by selling the gas itself. Instead, it earns fees for gathering, compressing, processing support, and handling water used in drilling and production. That usually makes revenue more stable than directly producing commodities, although it also creates a strong dependence on the activity level of its main customer.
Based on the company’s recent annual reporting, revenue is mainly generated from the following sources:
- Gathering and compression: approximately 65% to 75% of revenue. This includes moving natural gas from wells through gathering pipelines and boosting pressure through compression systems.
- Water handling and treatment: approximately 20% to 30% of revenue. This includes fresh water delivery, wastewater handling, treatment, recycling, and related services tied to drilling and completion activity.
- Other midstream services: approximately 5% to 10% of revenue. This can include ancillary fees and infrastructure-related services connected to its core systems.
The financial flow is notable for one reason: revenue has trended upward steadily over the last several years, while operating profitability has remained exceptionally strong for the sector. Interest expense is meaningful, but the underlying business still converts a large share of sales into operating income and net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Midstream | |
| Market Cap ⓘ | $10.01B | |
| Beta ⓘ | 0.69 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 25.40 | 15.44 |
| P/B Ratio ⓘ | 5.09 | 1.73 |
| FCF Yield ⓘ | 9.79% | 8.20% |
| Dividend Yield ⓘ | 4.26% | 3.59% |
| EBIT / EV ⓘ | 5.47% | 7.46% |
| PEG ⓘ | 1.17 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.30% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | 6.66% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | -9.17% | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | -3.73% | 6.07% |
| Margin Growth (5Y Trend) ⓘ | -6.25% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | 12.73% | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | -1.88% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 10.23% | 11.40% |
| ROA (Latest) ⓘ | 6.62% | 6.06% |
| ROIC (5Y Median) ⓘ | 9.73% | 10.30% |
| ROA (5Y Median) ⓘ | 6.45% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | 4.79 | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.48 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 3.71 | 1.08 |
| Net Debt / Assets ⓘ | 56.72% | 17.29% |
| EBITDA / Interest ⓘ | 4.77 | 9.64 |
| Operating Margin (Latest) ⓘ | 57.37% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 64.21% | 20.39% |
| Debt to Equity (Latest) ⓘ | 185.55% | 54.76% |
| Profit Margin (Latest) ⓘ | 30.45% | 8.82% |
| Free Cash Flow (Latest) ⓘ | $979.66M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +97.15% | +67.38% |
| 12M Return (excl. last month) ⓘ | +21.48% | +49.19% |
| 6M Return ⓘ | -0.26% | +7.07% |
| Price vs. 200-Day MA ⓘ | -1.73% | +9.56% |
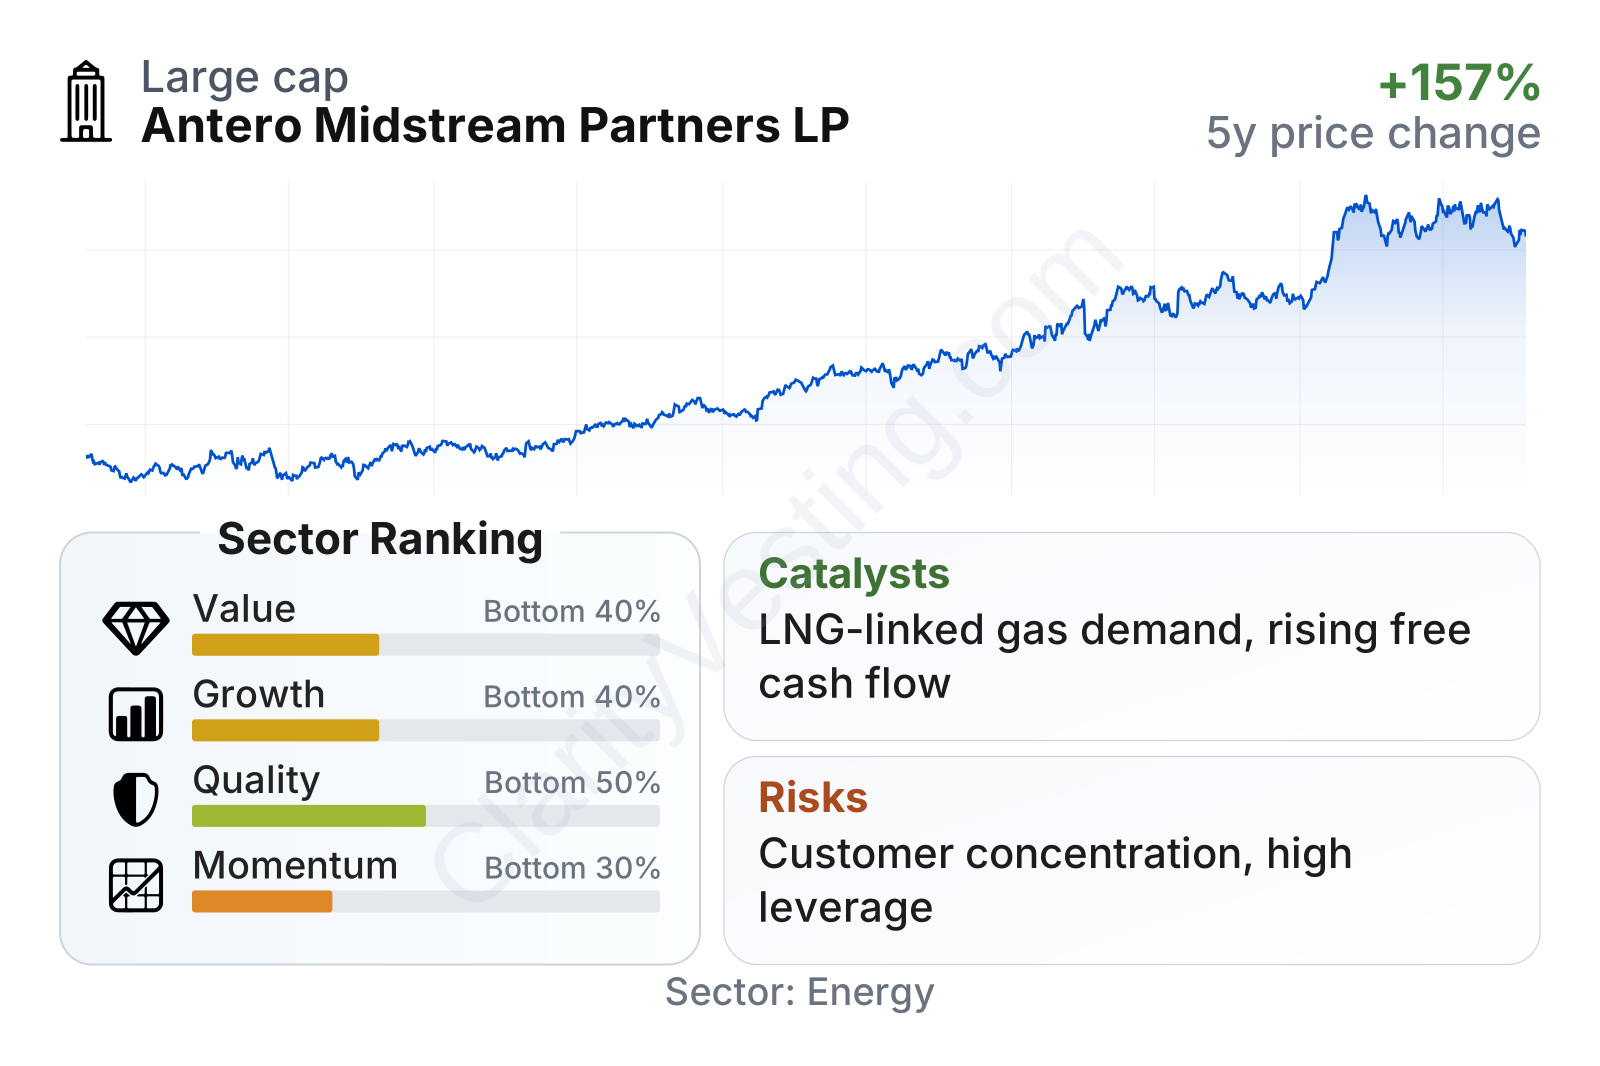
Antero Midstream is a large midstream operator with a market value near the $10 billion range and a below-market beta, which points to lower share-price volatility than many energy names. The overall profile is mixed: cash generation and profitability are strong, but growth ranks in the lower part of the sector and valuation multiples are not especially cheap. The company stands out for high margins and solid free cash flow yield, while leverage remains materially above industry norms.
Growth
Antero Midstream operates in a part of the energy market that still has long-lived demand drivers. Natural gas remains important for power generation, industrial use, LNG exports, and as a balancing fuel for renewable-heavy electricity systems. That does not make the sector fast-growing every year, but it does support continued need for gathering systems, compression, and water infrastructure in productive basins.
The company’s strategy is straightforward and relatively logical: expand and optimize infrastructure around one of the most active natural gas development areas in the United States, while keeping capital spending disciplined and turning more of its earnings into free cash flow. Because its assets are closely integrated with Antero Resources’ drilling program, growth is tied less to broad geographic expansion and more to throughput growth, efficiency gains, and continued development by its anchor customer.
Revenue growth has been positive in recent periods, but not especially fast compared with the broader energy sector. Recent year-over-year growth has generally stayed in the high-single-digit range, which suggests a steady utility-like expansion pattern rather than a rapid growth phase. For a midstream company, that can still be attractive when paired with durable contracts and visible volumes.
Free cash flow has improved sharply over the last few years and is now running close to the $1 billion level on a trailing basis. That matters because it gives the company more room to support distributions, fund projects internally, and reduce reliance on external financing. In a capital-intensive business, improving free cash flow is one of the clearest signs that the asset base is maturing well.
A meaningful catalyst is the broader rise of U.S. natural gas demand from LNG export capacity and power generation. If Appalachian production remains competitive, Antero Midstream’s systems can benefit from higher throughput over time. Company updates in 2026 have also continued to emphasize disciplined capital allocation, steady operational execution, and support from development activity at Antero Resources, which reinforces the visibility of its near- to medium-term volume base.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


