Stock Analysis · Alkermes Plc (ALKS)
Overview
Alkermes Plc is a biopharmaceutical company focused on medicines for neuroscience and oncology. In simple terms, it develops and sells prescription drugs for serious conditions such as schizophrenia, bipolar I disorder, and certain cancers. The business has become more centered on commercial-stage products after reshaping its portfolio in recent years.
The company’s revenue is mainly driven by product sales, with a smaller contribution from manufacturing and royalty-related activities tied to partnered medicines. Based on Alkermes’ recent annual reporting, the revenue mix is concentrated in a few key products and services.
- LYBALVI product sales: approximately 45% to 50% of total revenue. This is Alkermes’ branded treatment for schizophrenia and bipolar I disorder and is currently the company’s largest growth engine.
- VIVITROL product sales: approximately 20% to 25%. This medicine is used for alcohol dependence and opioid dependence in certain settings, and it remains an important cash-generating product.
- ARISTADA product sales: approximately 15% to 20%. This long-acting injectable antipsychotic for schizophrenia is another core neuroscience product.
- Manufacturing and royalty revenue: approximately 10% to 15%. This includes manufacturing revenue and royalties or milestone-related revenue associated with partnered products and legacy arrangements.
- Other product revenue: a low-single-digit share overall, including smaller commercial or collaboration-related contributions.
What stands out is that Alkermes is no longer primarily a royalty platform. It now depends much more on the commercial execution of its own branded medicines, especially LYBALVI. That makes the business easier to understand, but it also means performance is more directly tied to prescription growth, pricing, market access, and sales-force execution.
The long-term financial pattern has improved meaningfully from the loss-making period seen earlier in the decade. Revenue expanded strongly in 2023 and stayed at a high level afterward, while gross profit remained robust because the cost of producing its medicines is modest relative to selling prices. More recently, operating profit has come under some pressure as selling and administrative costs rose sharply, showing that growth is increasingly tied to commercial spending rather than just portfolio cleanup.
The broad takeaway from the financial flow is positive but mixed: Alkermes has built a business with strong gross margins and solid profitability, yet the latest period shows heavier operating costs and lower net income than the previous peak year.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Drug Manufacturers - Specialty & Generic | |
| Market Cap ⓘ | $7.29B | |
| Beta ⓘ | 0.27 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 117.51 | 25.42 |
| P/B Ratio ⓘ | 4.07 | 3.08 |
| FCF Yield ⓘ | 3.04% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | 1.96% | 0.56% |
| PEG ⓘ | 1.96 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 27.00% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 4.65% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | 29.66% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 11.75% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 12.15% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | 60.33% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.17% |
| ROA (Latest) ⓘ | 1.97% | 2.98% |
| ROIC (5Y Median) ⓘ | 15.34% | 4.56% |
| ROA (5Y Median) ⓘ | 10.54% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 6.78 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.33 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 4.87 | 1.00 |
| Net Debt / Assets ⓘ | 24.15% | 5.06% |
| EBITDA / Interest ⓘ | 3.69 | 9.55 |
| Operating Margin (Latest) ⓘ | 9.38% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 20.58% | 7.33% |
| Debt to Equity (Latest) ⓘ | 86.95% | 26.68% |
| Profit Margin (Latest) ⓘ | 3.97% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $221.65M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +80.84% | +51.61% |
| 12M Return (excl. last month) ⓘ | +56.68% | +19.90% |
| 6M Return ⓘ | +30.94% | +10.10% |
| Price vs. 200-Day MA ⓘ | +10.38% | +6.44% |
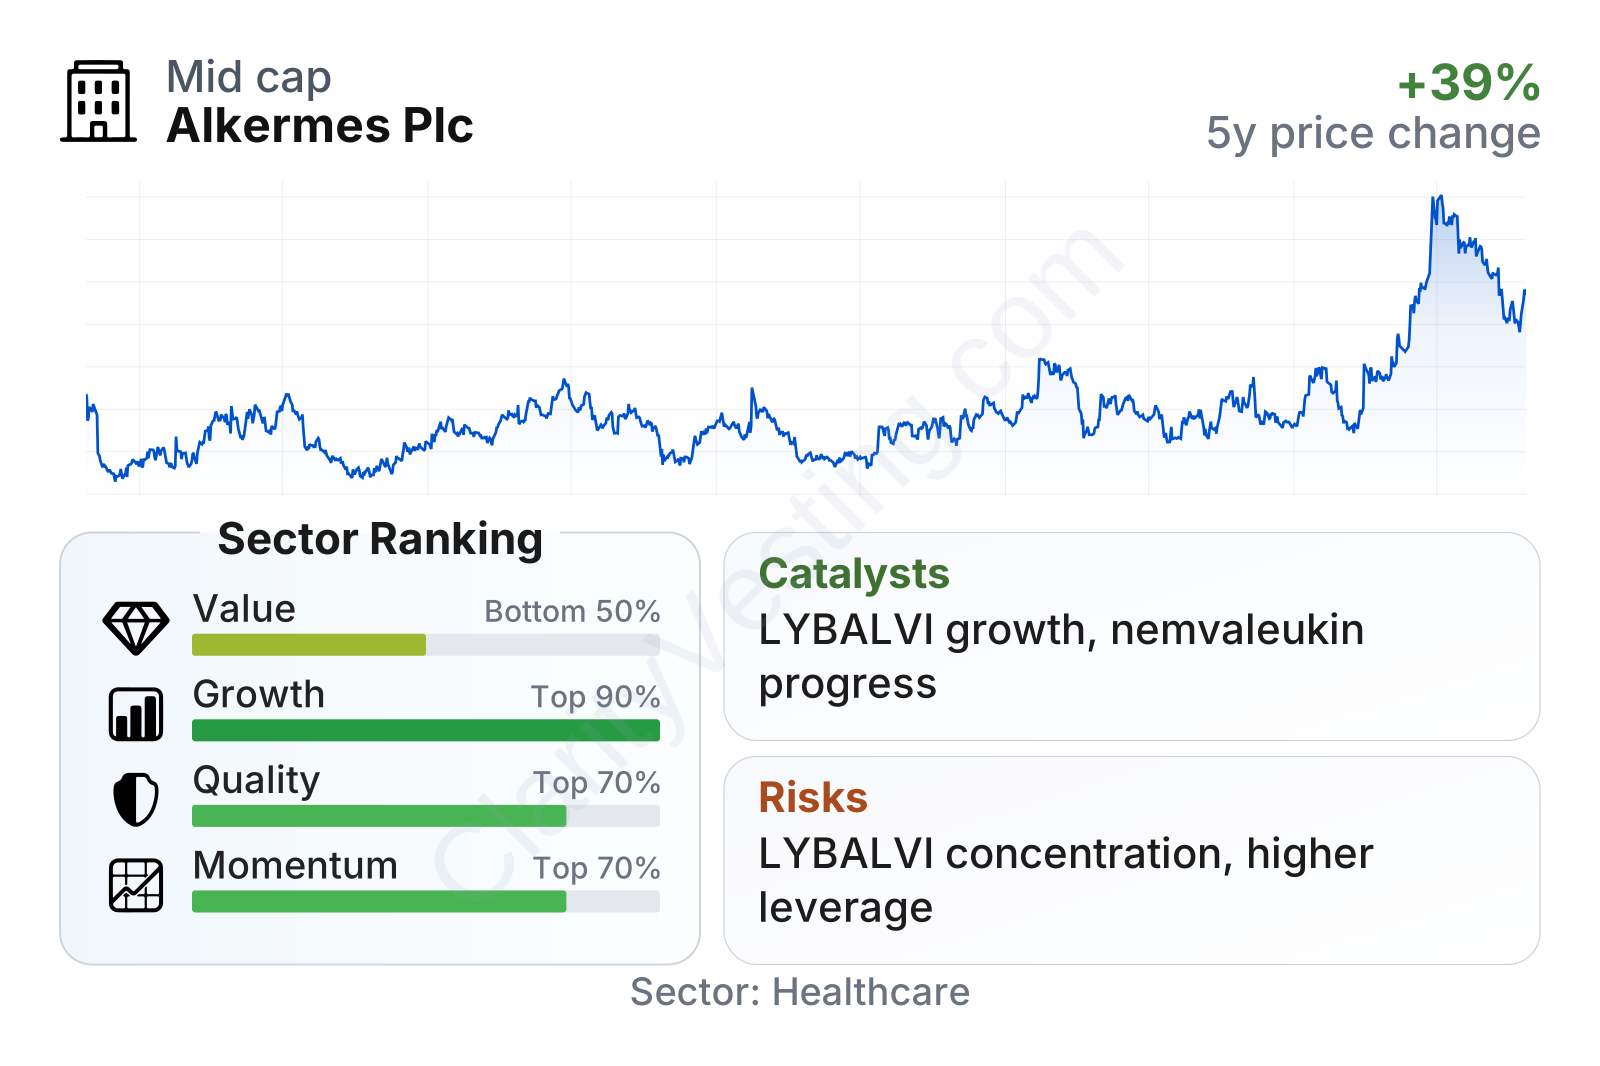
Alkermes is a mid-sized healthcare company with unusually low share-price volatility for a biotech-related name, as shown by its low beta. The quality and growth profile looks better than much of the sector, especially on long-term margin improvement, earnings growth, and cash generation. Value metrics are more mixed: free cash flow yield is competitive, but the earnings multiple is now far above the sector median, which reflects how much market expectations have risen after the sharp stock move.
The share-price history also shows a major re-rating. For several years the stock mostly traded in a moderate range, then surged strongly in 2026. That kind of move usually means the market is assigning much more value to future earnings potential than it did before.
Growth
Alkermes operates in a part of healthcare that has durable long-term demand. Serious mental health disorders and cancer are large treatment markets, and the need for better therapies does not depend much on the economic cycle. In that sense, the sector backdrop is supportive. The more important question is whether Alkermes has products with enough differentiation to keep expanding inside those markets.
The core growth case rests on LYBALVI. The product addresses a common problem in antipsychotic treatment: balancing efficacy with side effects, especially weight gain. If prescription growth continues and payer access remains favorable, LYBALVI can keep taking a larger place in the company’s revenue mix. ARISTADA and VIVITROL add diversification, but LYBALVI is the most visible commercial catalyst.
Revenue growth has not been smooth quarter to quarter, which is common in specialty pharmaceuticals, but the recent pace is clearly stronger than the industry median. The latest year-over-year growth rate is around the high-20% range, far above the sector’s typical level. That suggests the company is still in an expansion phase rather than a mature flat-growth phase.
Strategy also matters here. Alkermes has spent the last few years simplifying the business, reducing dependence on older economics, and emphasizing wholly owned products. That is a sensible direction for future growth because owned products usually provide more control over pricing, promotion, and margin capture than royalty streams do. The tradeoff is that Alkermes must now fund more of its own commercial infrastructure.
A separate catalyst is the oncology pipeline, particularly nemvaleukin alfa. Pipeline assets are important because the current commercial portfolio is still relatively concentrated. A successful late-stage oncology program could materially expand Alkermes beyond neuroscience and give the company a second major growth pillar. Recent company updates have kept attention on clinical progress and regulatory discussions in this area, which is why the market has treated pipeline developments as potentially significant.
Cash generation has improved a lot versus earlier years, even though it has pulled back from a recent high. Trailing free cash flow remains solidly positive, which matters because it gives Alkermes more room to fund research, support commercialization, and manage balance-sheet obligations without depending on new equity issuance.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


