Stock Analysis · Alliance Laundry Holdings Inc (ALH)
Overview
Alliance Laundry Holdings Inc is a manufacturer of commercial laundry equipment. In simple terms, it makes washers, dryers, and related systems used by laundromats, apartment buildings, hotels, hospitals, and other institutional customers. The company operates in a niche of the appliance market that is more industrial and service-oriented than the household washer and dryer business. Its brands and installed base give it exposure to recurring replacement demand, because laundry machines wear out and need servicing over time.
The business is generally organized around commercial laundry solutions sold through distributors and direct channels across North America, Europe, and other international markets. Public company materials describe revenue coming primarily from equipment sales, with support from parts, aftermarket needs, and related services. Detailed percentage splits can vary by filing period, and the most recent public materials do not appear to provide a simple published breakdown by revenue source with exact percentages in a single summary table. At a high level, the company’s revenue streams can be understood as follows:
- Commercial laundry equipment sales – the main source of revenue, including hard-mount and soft-mount washers, dryers, stack systems, and specialty machines for on-premises and vended laundry locations.
- Replacement parts and aftermarket support – recurring revenue tied to the installed base of machines already in the field.
- Services and other related revenue – support activities connected to equipment operation, customer relationships, and distribution.
- Geographic mix – revenue is spread across North America, Europe, and the rest of the world, which helps reduce dependence on a single regional economy.
What stands out financially is that revenue has been moving higher in recent years while operating income has also improved. Gross profit expanded meaningfully between 2022 and 2025, suggesting the company has had some pricing power, mix improvement, or manufacturing efficiency gains. However, interest expense also climbed, which matters because it reduces how much of that operating progress reaches net income.
The profit flow shows a business that has been strengthening at the operating level: revenue, gross profit, and operating income all improved over the last few years. The main offset is financing cost, with interest expense rising materially and limiting the conversion of operating gains into bottom-line growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Furnishings, Fixtures & Appliances | |
| Market Cap ⓘ | $4.35B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 23.52 | 17.04 |
| P/B Ratio ⓘ | 8.80 | 1.61 |
| FCF Yield ⓘ | 5.89% | 9.02% |
| Dividend Yield ⓘ | N/A | 2.75% |
| EBIT / EV ⓘ | 5.70% | 6.69% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 6.60% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | -7.81% | 9.04% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.44% |
| BVPS Growth (5Y CAGR) ⓘ | -33.60% | 5.73% |
| Margin Growth (5Y Trend) ⓘ | 2.34% | -0.26% |
| FCF Growth (5Y CAGR) ⓘ | 25.66% | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 10.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 10.96% | 12.38% |
| ROA (Latest) ⓘ | 6.12% | 5.54% |
| ROIC (5Y Median) ⓘ | N/A | 10.63% |
| ROA (5Y Median) ⓘ | N/A | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 5.00 | 2.16 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.85 | 2.31 |
| Net Debt / EBITDA (Latest) ⓘ | 3.94 | 1.52 |
| Net Debt / Assets ⓘ | 58.40% | 21.74% |
| EBITDA / Interest ⓘ | 3.98 | 9.06 |
| Operating Margin (Latest) ⓘ | 19.37% | 9.12% |
| Operating Margin (5Y Median) ⓘ | 16.91% | 9.56% |
| Debt to Equity (Latest) ⓘ | 378.92% | 76.18% |
| Profit Margin (Latest) ⓘ | 10.08% | 5.30% |
| Free Cash Flow (Latest) ⓘ | $256.18M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +11.77% |
| 12M Return (excl. last month) ⓘ | N/A | +0.61% |
| 6M Return ⓘ | +11.44% | +1.32% |
| Price vs. 200-Day MA ⓘ | -7.62% | -3.47% |
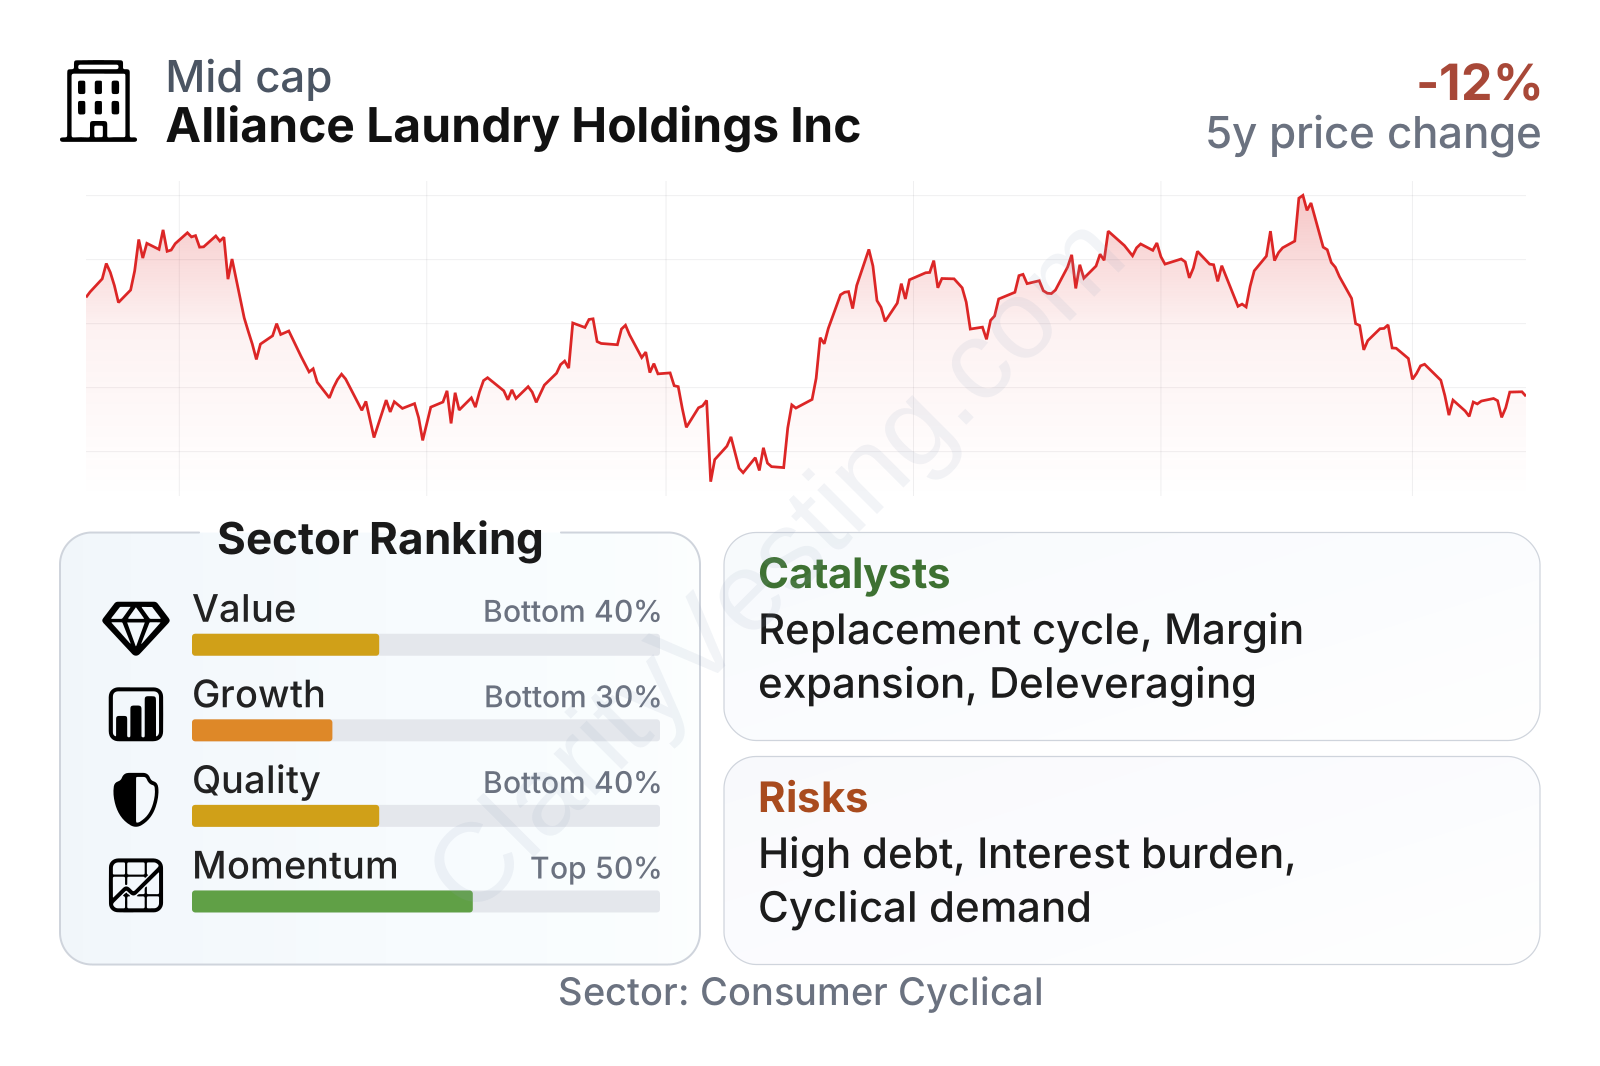
Alliance Laundry is a mid-sized public company within the consumer cyclical universe. The overall picture from the latest metrics is mixed. Profitability looks stronger than many industry peers, with operating margin around 19% and profit margin around 10%, both above sector medians. Free cash flow generation has also been solid, and the multi-year growth in free cash flow has been notably strong.
At the same time, the broader scorecard is held back by leverage and valuation. Revenue growth over the last year has been positive and slightly above the sector median, but the longer-term per-share growth record is less impressive. The share price has also recovered from early-2026 weakness and has shown decent medium-term momentum, though it still trades below its 200-day average, which suggests sentiment has improved but is not fully strong.
Growth
The company operates in a sector that is not usually seen as a high-growth technology market, but it can still produce durable growth because commercial laundry equipment benefits from several steady demand drivers. Apartment buildings, hospitality properties, healthcare facilities, universities, and laundromats all need reliable washing equipment regardless of short-term consumer trends. That makes the market more replacement-driven and infrastructure-like than many other consumer cyclical categories.
Alliance Laundry’s strategy appears logical for long-term expansion. A large installed base can support recurring parts demand, while product innovation and premium commercial brands can support pricing and upgrades. The business also benefits from exposure to both vended laundry and on-premises laundry, which diversifies end markets. In addition, global operations offer room for expansion outside its more established regions.
Recent financial progress points to some real operating momentum. Revenue increased from about $1.38 billion in 2022 to roughly $1.71 billion in 2025, while operating income rose from about $200 million to nearly $289 million over the same period. Gross profit improved even faster than sales, which is often a sign that management has been executing effectively on pricing, product mix, or costs. Free cash flow growth over the last five years has also been very strong relative to the sector.
A practical catalyst is the replacement cycle. Commercial machines are essential equipment, not optional purchases, and older fleets eventually need to be replaced with newer, more efficient models. Another catalyst is margin expansion: if Alliance Laundry can keep improving manufacturing efficiency and product mix, earnings growth could outpace revenue growth. International distribution and penetration into underserved markets could also support future gains, especially if the company continues to strengthen channel relationships and brand positioning.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


