Stock Analysis · Alcon AG (ALC)
Overview
Alcon AG is a large eye-care company focused on products used in surgery and vision correction. Its business is centered on two broad needs: helping ophthalmologists treat eye diseases and conditions in the operating room, and helping consumers manage eyesight through contact lenses and related products. That makes Alcon more specialized than many broader healthcare companies, with nearly all of its activity tied to the long-term demand for eye health.
The company reports revenue in two main segments. Based on recent annual reporting, the revenue mix is approximately as follows:
- Surgical: about 56% of revenue. This includes equipment, consumables, and implants used in cataract surgery, vitreoretinal procedures, and other ophthalmic operations. A large part of this segment comes from recurring procedure-driven products such as intraocular lenses, surgical packs, and fluids, supported by installed equipment in clinics and hospitals.
- Vision Care: about 44% of revenue. This includes contact lenses and ocular health products, especially daily replacement lenses and products sold through eye-care professionals and retail channels.
Within those segments, Alcon has been emphasizing higher-value categories such as premium intraocular lenses in Surgical and daily silicone hydrogel contact lenses in Vision Care. That matters because those categories can support better pricing, stronger brand loyalty, and recurring demand.
The business model also has a useful balance: Surgical is tied to medical procedures and aging populations, while Vision Care is linked to ongoing consumer use. Over the last several years, revenue has grown steadily, while gross profit has expanded faster than cost of revenue, showing some operating leverage even though selling expenses remain high, which is common for a company with a large global commercial footprint.
The overall revenue path has been positive, and profitability improved meaningfully from 2021 to 2024 before softening in 2025. Even with that moderation, the company remains much more profitable than it was earlier in the period.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $30.45B | |
| Beta ⓘ | 0.73 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 47.73 | 24.79 |
| P/B Ratio ⓘ | 1.43 | 2.97 |
| FCF Yield ⓘ | 5.53% | 3.11% |
| Dividend Yield ⓘ | 0.57% | 2.04% |
| EBIT / EV ⓘ | 2.50% | 0.57% |
| PEG ⓘ | 1.16 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.70% | 7.35% |
| RPS Growth (5Y CAGR) ⓘ | 5.68% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -7.13% | -18.43% |
| BVPS Growth (5Y CAGR) ⓘ | 3.28% | 3.94% |
| Margin Growth (5Y Trend) ⓘ | 4.65% | -0.61% |
| FCF Growth (5Y CAGR) ⓘ | 76.69% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | 32.23% | 6.74% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.34% |
| ROA (Latest) ⓘ | 2.04% | 2.95% |
| ROIC (5Y Median) ⓘ | 3.70% | 4.60% |
| ROA (5Y Median) ⓘ | 3.17% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | 4.42 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.96 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 1.42 | 1.02 |
| Net Debt / Assets ⓘ | 12.68% | 5.85% |
| EBITDA / Interest ⓘ | 13.31 | 9.60 |
| Operating Margin (Latest) ⓘ | 8.25% | 9.19% |
| Operating Margin (5Y Median) ⓘ | 10.80% | 7.53% |
| Debt to Equity (Latest) ⓘ | 24.54% | 29.44% |
| Profit Margin (Latest) ⓘ | 5.92% | 3.52% |
| Free Cash Flow (Latest) ⓘ | $1.68B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -15.49% | +34.80% |
| 12M Return (excl. last month) ⓘ | -13.15% | +19.33% |
| 6M Return ⓘ | -17.95% | +7.18% |
| Price vs. 200-Day MA ⓘ | -13.25% | +3.20% |
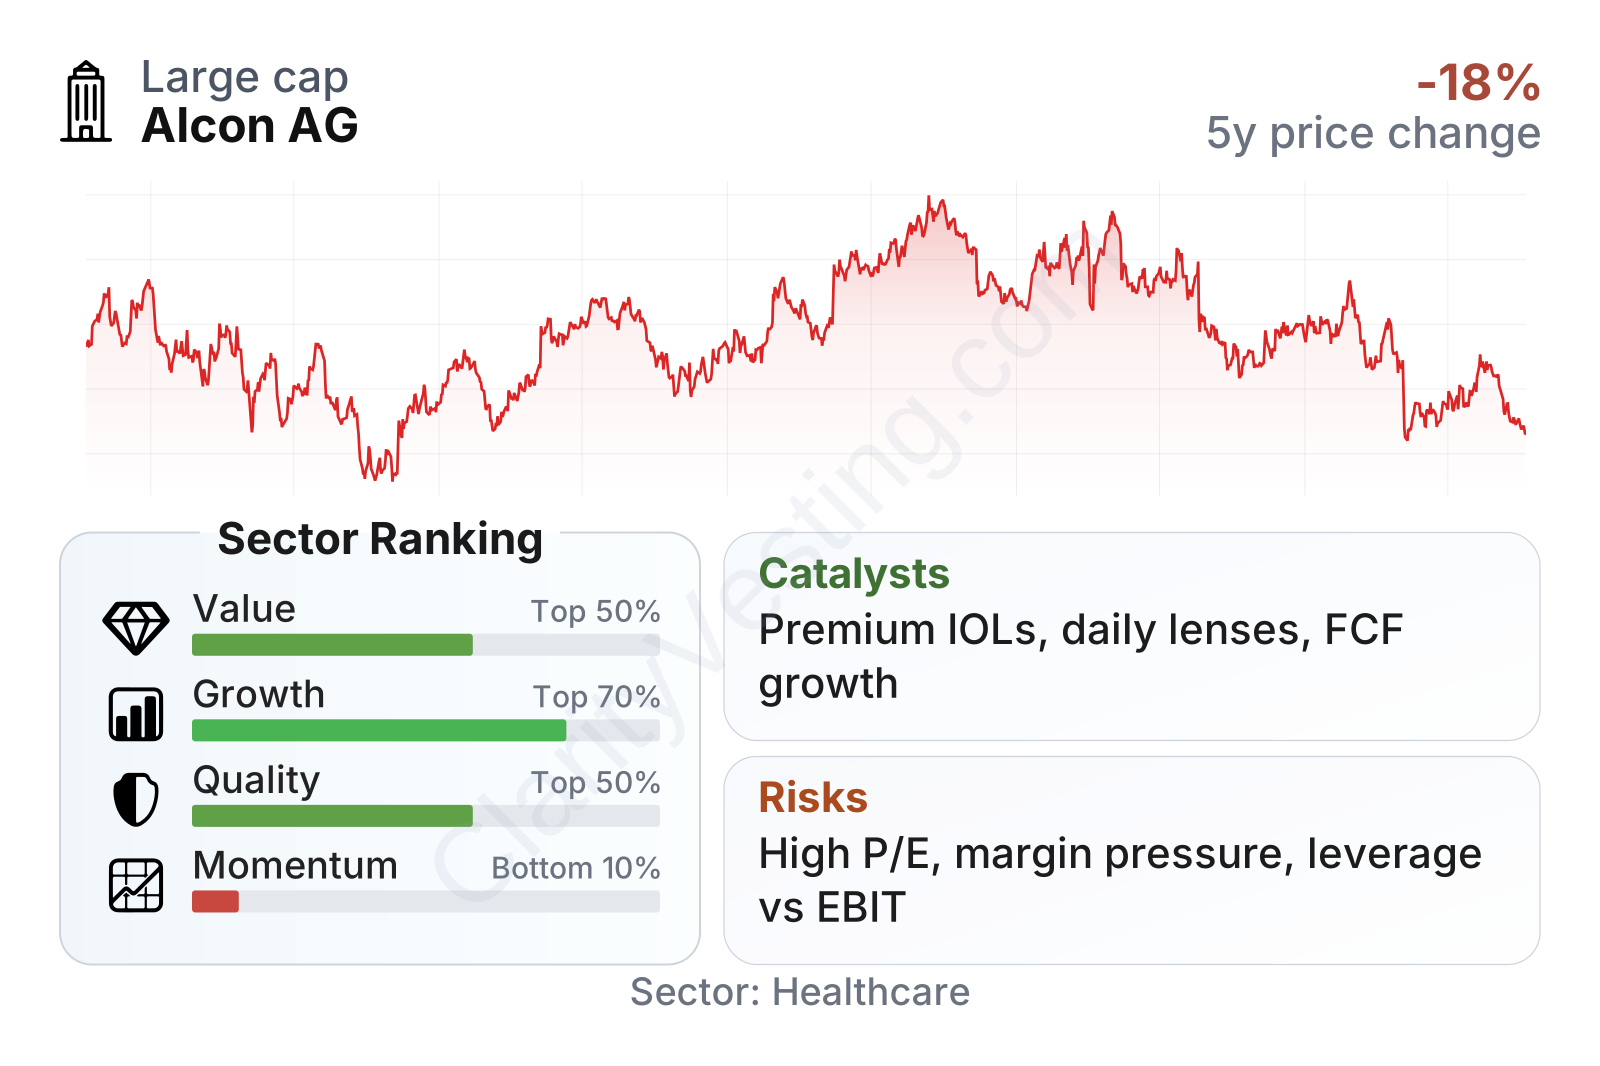
Alcon is a large healthcare equipment company with relatively low share-price volatility, as reflected by a beta below 1. In the broader sector comparison, the company ranks around the middle on valuation and quality, above average on growth, and weak on recent market momentum. The main contrast in the current profile is that cash generation looks solid relative to the sector, while the earnings multiple remains elevated. That combination usually means the market still expects durable growth and margin improvement despite recent share-price weakness.
Growth
Alcon operates in an attractive part of healthcare. Eye care benefits from several long-term demand drivers: populations are aging, cataract procedures rise with age, myopia remains widespread, and contact lens adoption continues to expand in many markets. These are not short-lived trends. They create a backdrop where procedure volumes and recurring vision products can both grow over time.
The company’s strategy is aligned with those trends. In Surgical, Alcon has been pushing premium intraocular lenses, digital and advanced visualization systems, and procedure-related consumables. In Vision Care, it has been focusing on innovation in daily contact lenses and specialized offerings such as toric and multifocal lenses. This makes strategic sense because premium products can lift revenue per patient or per wearer without depending only on volume growth.
Recent revenue growth has been steady rather than explosive, generally running in the mid-single-digit to high-single-digit range, with the latest year-over-year pace ahead of the sector median. That suggests the company is still expanding in a disciplined way despite its already large scale.
Cash generation has improved sharply over the past few years. Free cash flow moved from a modest level to well above $1.5 billion on a trailing basis, which is one of the more encouraging signs in the financial profile. Stronger cash conversion gives Alcon more flexibility to fund research, commercial expansion, manufacturing capacity, debt service, and shareholder distributions without relying heavily on outside financing.
One of the strongest catalysts is the combination of recurring procedure demand and product refresh cycles. New premium lenses, upgrades in surgical platforms, and continued penetration of advanced daily contact lenses can each add growth, and together they create several ways for revenue to expand. Company communications in 2026 have also continued to emphasize product launches and pipeline execution in both Surgical and Vision Care, which supports the view that growth is not dependent on a single product.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


