Stock Analysis · Assured Guaranty Ltd (AGO)
Overview
Assured Guaranty Ltd is a specialty insurer focused mainly on financial guaranty insurance. In simple terms, it insures certain bonds and structured finance obligations so that investors continue to receive scheduled principal and interest even if the original borrower runs into trouble. The company is especially known for its presence in the U.S. municipal bond market, where states, cities, utilities, hospitals, transportation agencies, and other public entities borrow money.
The business model is different from a typical property and casualty insurer. Assured Guaranty generally earns premiums for taking long-duration credit risk, invests its insurance float, and manages existing insured portfolios over many years. It also operates an asset management business through Assured Investment Management, which adds a fee-based revenue stream alongside insurance-related earnings.
Based on recent company disclosures, revenue comes from a mix of insurance and investment-related activities. Exact proportions can move materially from year to year because this business is affected by mark-to-market movements, refundings, loss development, and the timing of insurance accounting. Still, the main sources can be organized as follows:
- Net earned premiums and installment premiums – typically a major source of insurance revenue, tied to municipal and structured finance guarantees already written.
- Net investment income – income from the company’s investment portfolio, an important contributor because insurers invest premium proceeds and capital over long periods.
- Financial gains or losses, including fair value changes – these can meaningfully affect reported revenue and earnings in certain years, but they are less predictable than recurring premiums or investment income.
- Asset management and related fees – a smaller but strategically useful revenue source coming from managing capital for third parties and affiliated vehicles.
For long-term readers, the key point is that Assured Guaranty is not a broad insurance conglomerate. It is a specialized credit insurer with a dominant niche in municipal bond insurance, plus a growing effort to broaden its earnings base through asset management and infrastructure-related opportunities.
The earnings profile has been volatile, but one pattern stands out: operating profitability has remained strong, with operating income and net income recovering well after the weaker 2022 period. Revenue has also swung sharply from year to year, which is normal for a company whose reported results can be influenced by credit markets, accounting marks, and deal timing.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Insurance - Specialty | |
| Market Cap ⓘ | $3.05B | |
| Beta ⓘ | 0.72 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 9.22 | 12.46 |
| P/B Ratio ⓘ | 0.57 | 1.25 |
| FCF Yield ⓘ | 10.64% | 9.82% |
| Dividend Yield ⓘ | 2.06% | 2.94% |
| EBIT / EV ⓘ | 11.33% | 8.11% |
| PEG ⓘ | 0.33 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -0.50% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 14.15% | 12.31% |
| EPS Growth (5Y CAGR) ⓘ | -2.68% | -6.97% |
| BVPS Growth (5Y CAGR) ⓘ | -15.52% | 5.02% |
| Margin Growth (5Y Trend) ⓘ | 34.27% | -4.00% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.71% |
| DPS Growth (5Y CAGR) ⓘ | 11.57% | 8.92% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 6.30% | 9.18% |
| ROE (Latest) ⓘ | 6.26% | 13.93% |
| ROA (Latest) ⓘ | 2.84% | 1.57% |
| ROIC (5Y Median) ⓘ | 5.98% | 7.80% |
| ROE (5Y Median) ⓘ | 6.78% | 12.15% |
| ROA (5Y Median) ⓘ | 3.08% | 1.28% |
| Net Debt / EBIT (Latest) ⓘ | 2.78 | 1.02 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.10 | 0.72 |
| Net Debt / EBITDA (Latest) ⓘ | 3.11 | 0.88 |
| Operating Margin (Latest) ⓘ | 57.70% | 22.30% |
| Operating Margin (5Y Median) ⓘ | 61.03% | 24.50% |
| Debt to Equity (Latest) ⓘ | 30.69% | 59.34% |
| Profit Margin (Latest) ⓘ | 43.17% | 26.42% |
| Free Cash Flow (Latest) ⓘ | $324.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +24.75% | +95.73% |
| 12M Return (excl. last month) ⓘ | -13.79% | +17.30% |
| 6M Return ⓘ | -14.67% | +6.07% |
| Price vs. 200-Day MA ⓘ | -10.96% | +5.36% |
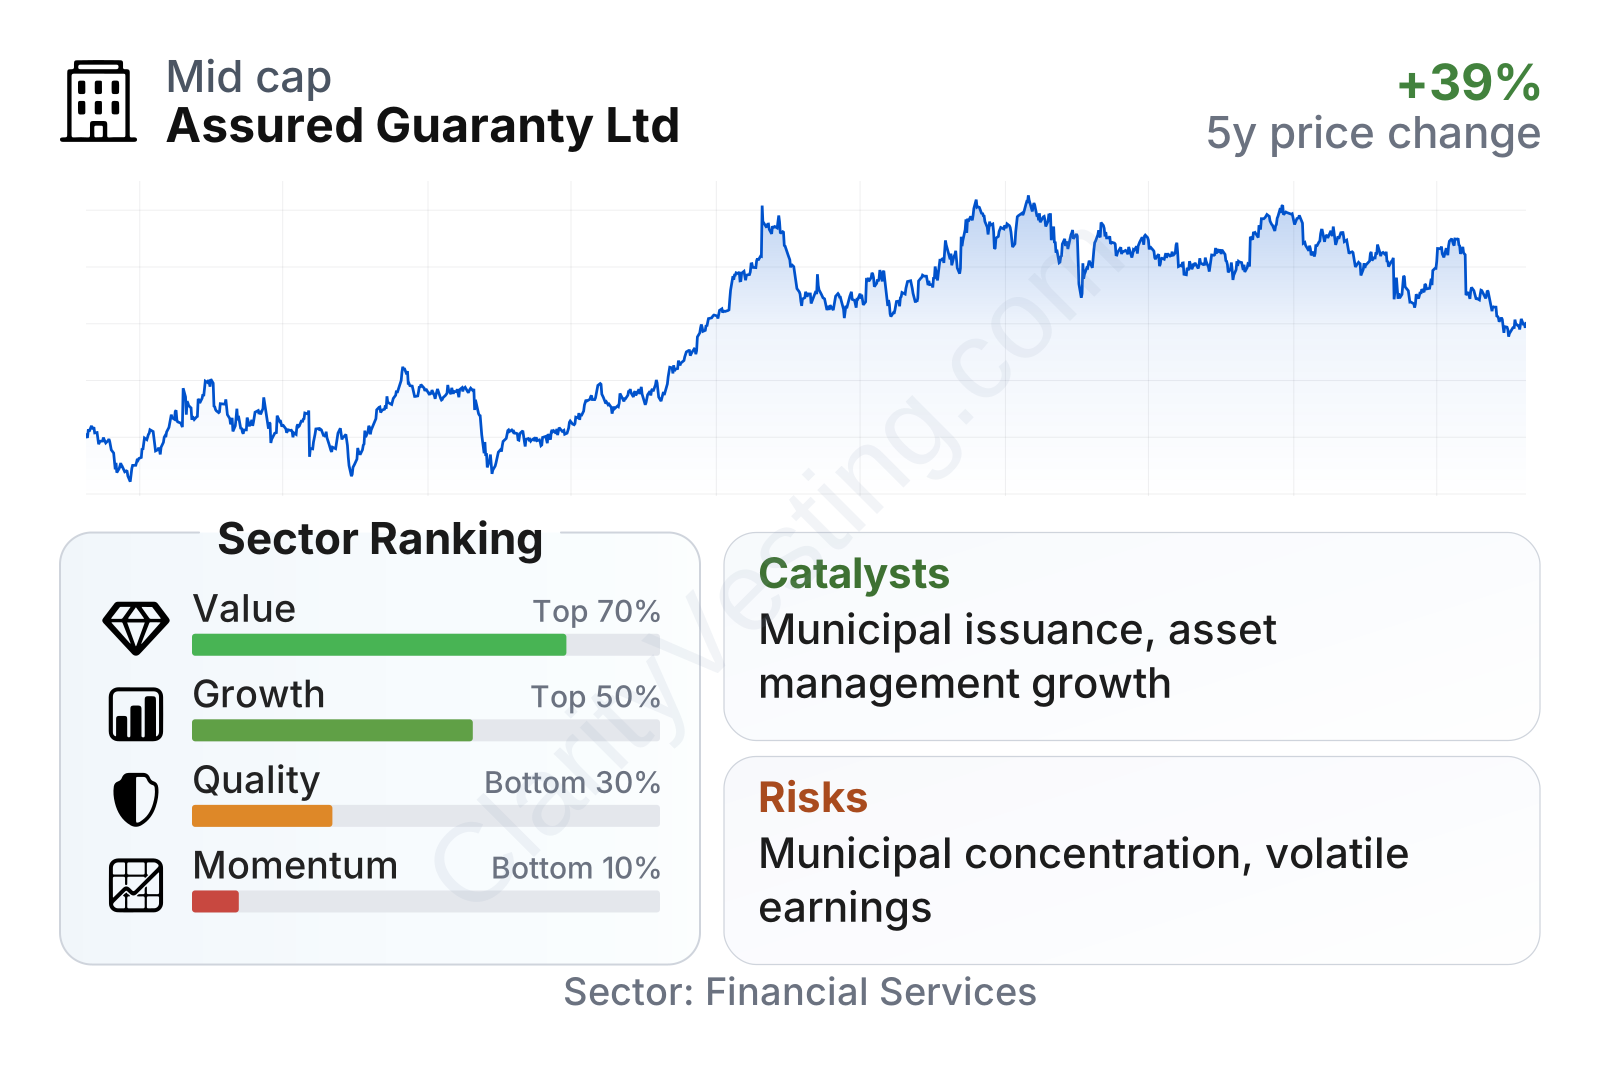
Assured Guaranty looks inexpensive on several traditional valuation measures. Its earnings multiple is below the sector median, and its price-to-book ratio is far below the typical financial services company. Cash generation also appears solid, with free cash flow yield slightly above the sector median. Where the picture is less favorable is quality and market momentum: returns on equity trail much of the sector, while the stock’s recent price performance has been notably weaker than peers. The company also carries more leverage than the sector median on earnings-based debt measures, even though debt-to-equity itself remains moderate for a financial business.
The share price history shows a stock that has advanced over the multi-year period but with noticeable swings. That fits the company’s profile: earnings are profitable over time, but sentiment can move sharply when municipal issuance, credit spreads, or fair value adjustments shift.
Growth
Assured Guaranty operates in a mature rather than fast-growing corner of finance, so the growth question is less about explosive industry expansion and more about whether the company can deepen its position in selected markets. The core municipal bond insurance market can benefit when borrowing activity rises, when issuers seek lower financing costs, or when investors value added credit protection more highly. Higher infrastructure needs in the United States can also support long-term demand for municipal financing, which is the company’s main domain.
Its strategy is reasonably coherent for this kind of business. Management has continued to focus on the municipal market, where Assured Guaranty has scale, brand recognition, and long experience, while also trying to diversify through asset management and selective structured or international opportunities. That matters because a pure bond insurer can face uneven issuance cycles, whereas fee income and new product lines can smooth results over time.
Earnings per share have been uneven from year to year, with a sharp rebound after 2022, a pullback in 2024, and another improvement in 2025. That volatility is typical for this business and means growth should not be judged by a single year. More useful is the company’s ability to stay profitable across cycles, keep underwriting discipline, and return capital while waiting for better issuance conditions.
Book value per share fell sharply earlier in the period, then recovered steadily through 2025. That recovery is important because book value is a closely watched measure for financial guaranty insurers. It suggests the balance sheet has been rebuilding, even if the five-year growth rate still looks weak because of the unusually large earlier decline.
Recent company communications have also highlighted continued municipal market activity, capital management, and the development of asset management capabilities. A meaningful opportunity for Assured Guaranty is that it remains one of the few scaled specialists in bond insurance at a time when many public borrowers continue to need efficient market access. If issuance expands and insured penetration improves even modestly, the company’s niche position could become more valuable.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


