Stock Analysis · Alamos Gold Inc (AGI)
Overview
Alamos Gold is a gold mining company focused on producing gold from long-life mines in North America. Its main operating assets are in Canada and Mexico, and the company also has development-stage projects that could support future production growth. In simple terms, Alamos spends money to explore for gold, build and operate mines, process ore, and then sell the produced gold into the market.
The business is fairly straightforward: revenue is driven mainly by how much gold the company produces and the market price it receives. Based on recent annual reporting, revenue is overwhelmingly tied to gold sales, with only a small contribution from by-products and other items.
- Gold sales: approximately 97% to 99% of revenue. This is the core business and comes from mines including Young-Davidson and Island Gold in Canada, and Mulatos in Mexico.
- Silver and other by-product sales: approximately 1% to 3% of revenue. These are secondary metals recovered during mining and processing.
- Other income: limited and irregular. This can include items such as foreign exchange effects or other non-core operating items, but it is not a major revenue source.
Geographically, the company is concentrated in a small number of mining districts rather than being broadly diversified across many countries. That can be a strength when operations run well, because management can focus capital and expertise, but it also means each major mine matters a lot.
One notable trend over the last several years is that revenue and profitability have improved sharply. Sales moved from a little over $800 million in 2021 and 2022 to above $1.8 billion in 2025, while operating income and net income expanded even faster. That suggests stronger production, stronger realized gold prices, and better operating leverage.
The operating picture has become much stronger: revenue has risen materially, costs have grown more slowly than sales, and interest expense remains very low. That combination points to a miner that has recently converted favorable market conditions into unusually strong earnings.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $13.32B | |
| Beta ⓘ | 1.40 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.45 | 16.92 |
| P/B Ratio ⓘ | 2.79 | 1.66 |
| FCF Yield ⓘ | 2.37% | 5.83% |
| Dividend Yield ⓘ | 0.41% | 2.07% |
| EBIT / EV ⓘ | 11.04% | 6.38% |
| PEG ⓘ | -2.50 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 35.60% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 19.57% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 45.44% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 10.79% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 53.10% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 1.99% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 24.16% | 9.59% |
| ROA (Latest) ⓘ | 18.41% | 4.92% |
| ROIC (5Y Median) ⓘ | 7.70% | 7.91% |
| ROA (5Y Median) ⓘ | 5.47% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.27 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.74 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.24 | 0.93 |
| Net Debt / Assets ⓘ | -6.27% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.38 |
| Operating Margin (Latest) ⓘ | 69.91% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 29.71% | 11.82% |
| Debt to Equity (Latest) ⓘ | 4.50% | 40.30% |
| Profit Margin (Latest) ⓘ | 52.64% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $315.52M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +153.34% | +73.47% |
| 12M Return (excl. last month) ⓘ | +9.29% | +27.59% |
| 6M Return ⓘ | -28.62% | -4.02% |
| Price vs. 200-Day MA ⓘ | -17.58% | -0.65% |
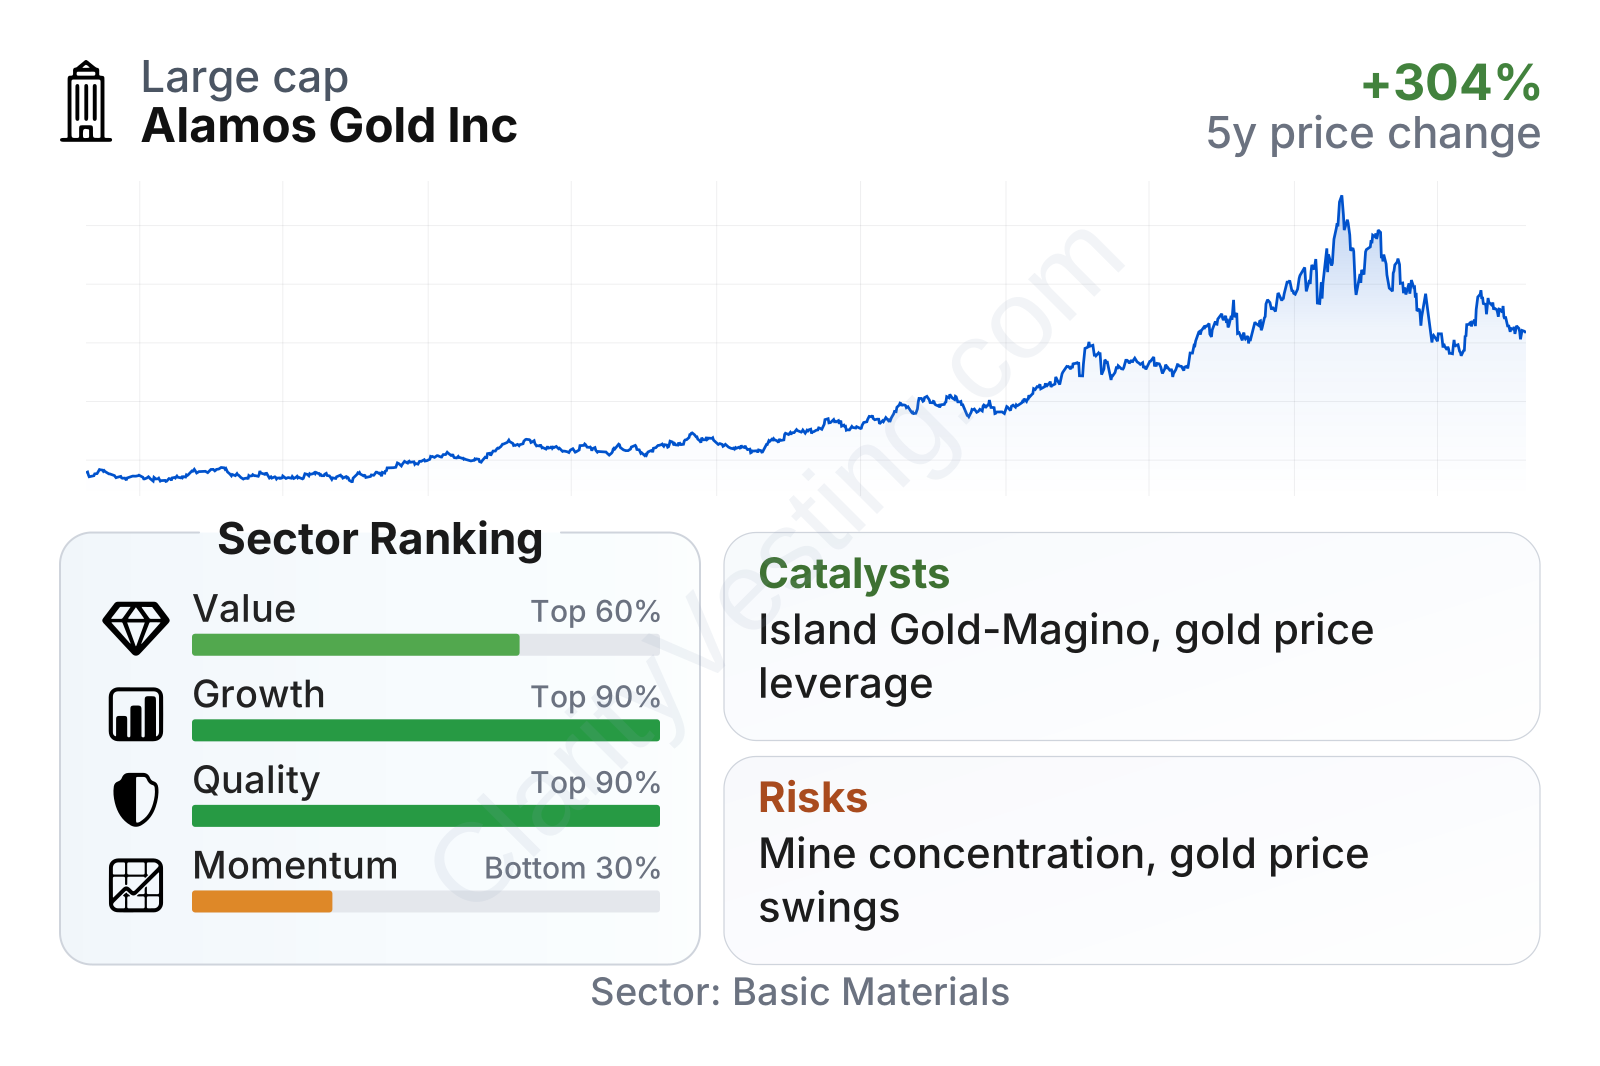
Alamos Gold stands out for business quality and growth more than for income generation or short-term price momentum. Relative to the broader gold and materials universe, profitability, returns on capital, and balance sheet strength are all strong. Growth measures are also near the top of the sector, while recent share-price momentum has cooled after a major multiyear run-up. On valuation, earnings-based measures look less demanding than many peers, although book value and cash flow yield make the stock look less obviously cheap.
The company is now a large gold producer by market value, but still much smaller than the biggest global names. Its beta above 1 also suggests the stock can move more sharply than the market, which is common for precious-metals producers.
Growth
Gold mining is not a classic high-growth industry, but it can enter strong upcycles when gold prices rise, costs stay under control, and companies bring new production online. Alamos Gold operates in a sector that benefits from demand for gold as a store of value, a central-bank reserve asset, and a hedge during periods of inflation, geopolitical stress, or financial uncertainty. That does not create steady linear growth, but it can create powerful earnings expansion when conditions are favorable.
Alamos appears well positioned within that context because its strategy is based on expanding production from owned assets in relatively established mining regions. The most important growth driver is the Island Gold district in Ontario, where the company has been advancing a major expansion. That project matters because it is expected to lift output and potentially improve unit economics over time. The acquisition of Argonaut Gold, completed in 2024, also added the Magino mine adjacent to Island Gold, creating a larger combined mining complex with possible operating synergies.
Revenue growth has been strong for an extended period, with most recent year-over-year readings well above the sector median. That is important because it suggests the company is not relying only on a higher gold price; operating progress has also contributed.
Cash generation has improved meaningfully as well. Free cash flow moved from negative territory in 2022 to solidly positive levels more recently, which gives Alamos more flexibility to fund expansions, maintain dividends, and preserve balance sheet strength without relying heavily on external financing.
A recent opportunity worth watching is the continuing development of the Island Gold-Magino complex. If execution remains on track, it could become the company’s clearest production and cost catalyst over the next several years. In addition, a supportive gold-price environment can have an outsized effect on miners with expanding output, because a large share of incremental revenue can flow through to profit once fixed costs are covered.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


