Stock Analysis · Allied Energy Inc (AGGI)
Overview
Allied Energy Inc is a very small public company that, despite its name, is currently classified in Internet Content & Information within the Communication Services sector. Based on recent public filings and company materials, the business appears to be centered on digital operations rather than traditional energy production. For long-term analysis, that matters because the key question is less about the legacy company name and more about whether the current operating model can scale into a durable online business.
The latest annual pattern suggests revenue has been coming from a narrow base and at a small absolute scale, although it improved sharply over the last reported full year. Public disclosures do not provide a detailed segment breakdown robust enough to assign precise percentages across multiple lines of business with confidence. The clearest takeaway is that the company’s revenue base is still concentrated, which can create both upside if demand expands and fragility if a customer, product, or channel weakens.
The income flow has improved notably over the last few reporting periods. Revenue rose from a very low level in 2023 to a higher, but still modest, level in 2024, and then expanded again in 2025. Gross profit also turned strongly positive after earlier pressure from cost of revenue. That said, the company’s path has not been smooth: it moved from losses to reported profitability only recently, so the current business model is still in an early proof stage rather than a mature, stable operation.
Main sources of revenue are not disclosed in enough detail in recent public materials to present a reliable percentage split by category. What can be said from available filings is:
- The company’s revenue appears to come primarily from its current internet and digital-information-related operations.
- No well-supported public breakdown is available that would allow a dependable ranking of several revenue streams with percentages.
- This limited disclosure itself is important: it suggests the business is still small and not yet reported with the level of segmentation usually seen in larger, more established companies.
The recent progression is encouraging at a high level: sales moved up materially, gross profit improved, and the company posted positive net income in the latest full-year view shown here. The main caution is that this improvement came from a very small starting point, so percentage gains look dramatic even though the company remains tiny by public-market standards.
Key Figures
Metric Value Sector ⓘ Date Oct 31, 2026 Context Sector Communication Services Industry Internet Content & Information Market Cap ⓘ $90.87M Beta ⓘ 3.37 P/E Ratio ⓘ 45.00 18.47 FCF Yield ⓘ 0.53% 14.23% Dividend Yield ⓘ N/A 2.78% EBIT / EV ⓘ N/A 4.73% PEG ⓘ N/A Revenue Growth ⓘ 18961.00% 6.10% RPS Growth (5Y CAGR) ⓘ 0.37% 4.57% EPS Growth (5Y CAGR) ⓘ N/A -17.96% Margin Growth (5Y Trend) ⓘ N/A 1.32% FCF Growth (5Y CAGR) ⓘ N/A 5.75% DPS Growth (5Y CAGR) ⓘ N/A 5.19% ROIC (Latest) ⓘ N/A 9.19% ROIC (5Y Median) ⓘ N/A 8.24% Net Debt / EBIT (Latest) ⓘ N/A 1.92 Net Debt / EBIT (5Y Median) ⓘ N/A 2.88 Net Debt / EBITDA (Latest) ⓘ -0.10 1.22 Net Debt / Assets ⓘ -8.70% 18.63% EBITDA / Interest ⓘ N/A 8.36 Operating Margin (Latest) ⓘ N/A 15.68% Operating Margin (5Y Median) ⓘ N/A 13.39% Debt to Equity (Latest) ⓘ 0.54% 59.65% Profit Margin (Latest) ⓘ 52.48% 8.74% Free Cash Flow (Latest) ⓘ $479.08K 3Y Return ⓘ +119900.00% +46.16% 12M Return (excl. last month) ⓘ +29900.00% +1.26% 6M Return ⓘ +37400.00% 0.00% Price vs. 200-Day MA ⓘ +231.92% +0.87%
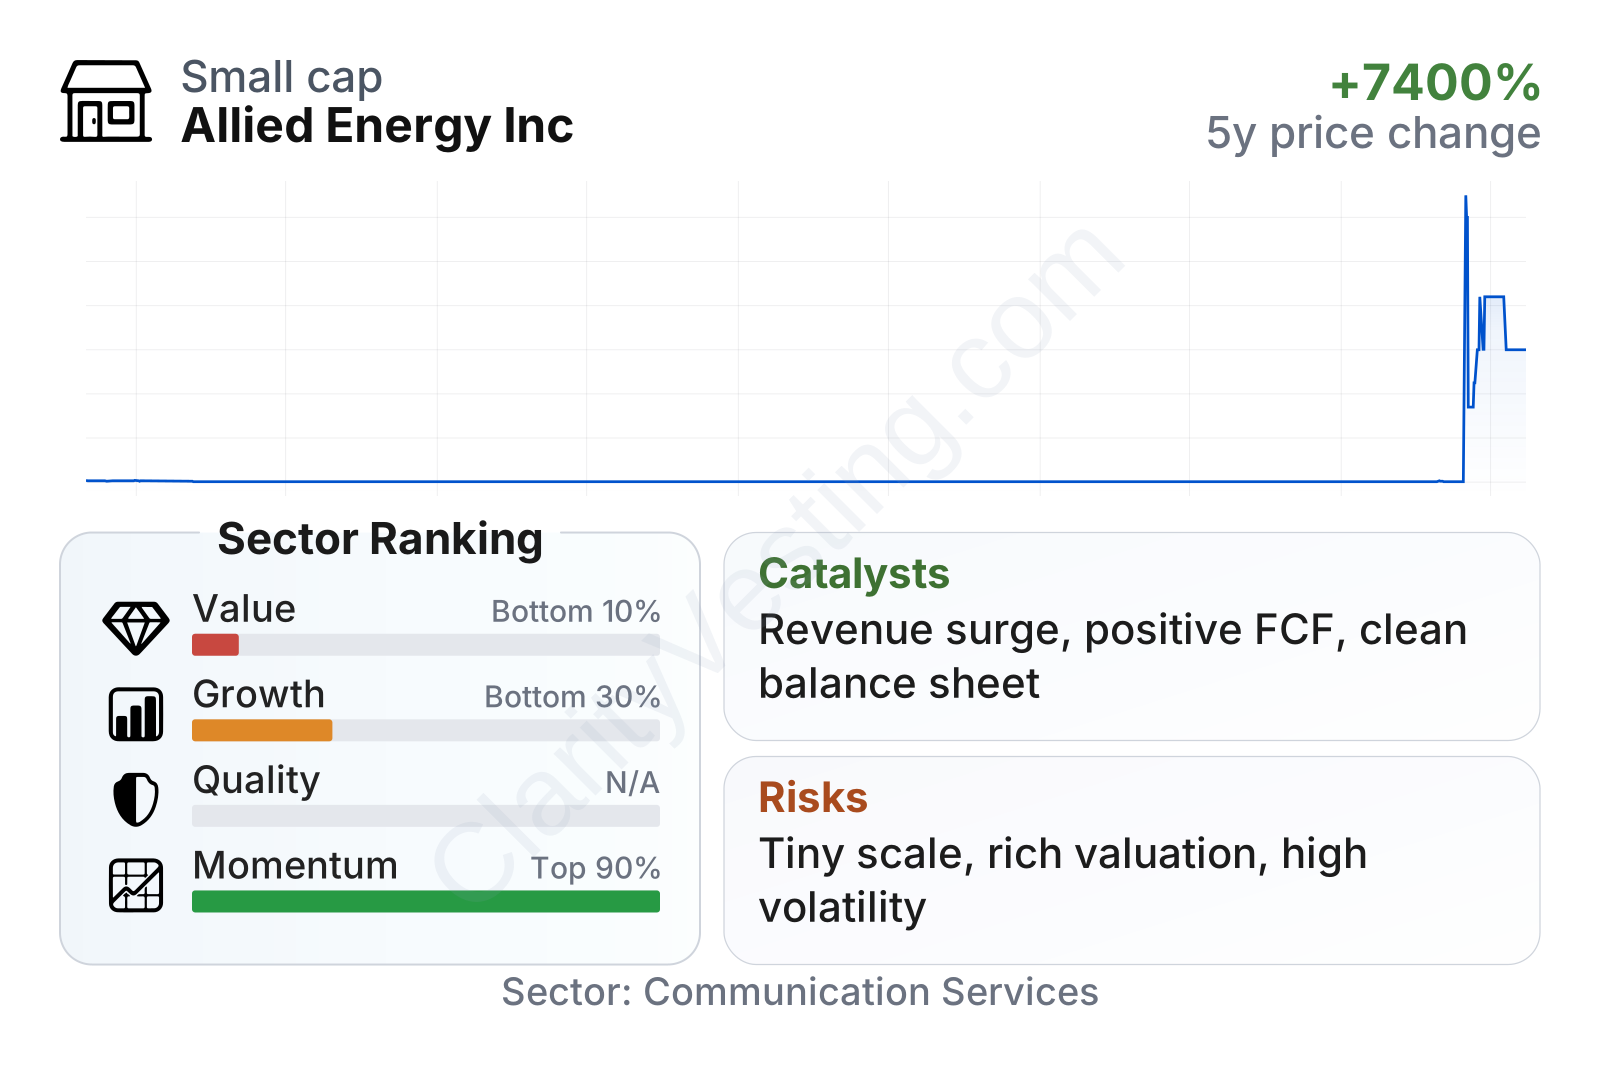
Allied Energy is a micro-cap company with a market value below $100 million, which usually means higher uncertainty and larger share-price swings. That volatility is visible in its beta of roughly 3.4, far above the market average. The stock’s momentum has been exceptionally strong versus most companies in its sector over the last 6 months, 12 months, and 3 years, but the valuation profile looks stretched, with a P/E ratio well above the sector median and a free-cash-flow yield that is much lower than typical peers.
On balance, the metrics show a business with strong recent market enthusiasm, light balance-sheet debt, and fresh profitability, but also one whose current share price already reflects a great deal of optimism relative to its size and operating history. Growth rankings remain weak on a multi-year basis even after the recent surge because the company’s longer record is still thin and uneven.
Growth
The company operates in a part of the market that can, in theory, scale quickly. Internet content and digital information businesses can grow faster than traditional industries when they find a repeatable customer acquisition model, a valuable niche, or a monetization engine with low incremental costs. That is the bullish angle around Allied Energy’s current positioning: small digital businesses can sometimes move from negligible revenue to meaningful revenue quickly if a product gains traction.
The recent revenue pattern points to that kind of acceleration. Year-over-year growth has been highly volatile, including one quarter with an extreme spike and another with still very strong double-digit growth. For a larger company, such volatility could be concerning, but for a company this small it usually means the business is still finding its footing and that even a handful of commercial wins can move the numbers sharply.
Cash generation also improved recently. Trailing free cash flow turned positive and increased meaningfully into the latest period. That matters because many tiny public companies can show revenue growth without producing cash. Allied Energy has at least begun to show that its recent expansion is not purely accounting-based. Even so, the absolute dollar amount remains modest, so it is too early to treat current cash generation as firmly established.
The company’s strategy appears sensible only if management can continue converting recent momentum into recurring revenue at a larger scale. The strongest potential catalyst is simple: if the business can sustain positive free cash flow and keep growing from its current base, the market may continue to view it as an early-stage digital platform rather than as a stagnant micro-cap. Another possible catalyst is that the company currently carries very little balance-sheet leverage, giving it more flexibility than many small-cap peers if it needs to invest in expansion.
Recent public information mainly points to operating improvement rather than a single transformational event. The key opportunity is therefore not one headline development but the combination of sharply higher revenue, positive earnings, and positive free cash flow emerging within a short period. For a company of this size, that cluster of changes is often what attracts market attention.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


