Stock Analysis · AGCO Corporation (AGCO)
Overview
AGCO Corporation is a global agricultural equipment manufacturer focused on helping farmers plant, protect, harvest, store, and manage crops more efficiently. Its best-known brands include Fendt, Massey Ferguson, PTx, and Valtra. The company sells machinery such as tractors, combines, sprayers, hay tools, seeding equipment, grain storage systems, and replacement parts, and it is also expanding in precision agriculture technologies that help farmers use inputs more accurately.
AGCO’s revenue mainly comes from equipment sales, with a smaller but important contribution from parts and service-related activity. Based on the company’s recent annual reporting structure, revenue is primarily split by geography rather than by product line, which is useful because farm machinery demand often follows regional crop economics and local dealer conditions.
- Europe/Middle East (around 50% to 55%): AGCO’s largest region, supported by strong positions in tractors and premium farming equipment, especially through the Fendt brand.
- North America (around 25% to 30%): Sales of large agricultural machinery, precision solutions, application equipment, and grain-related systems are important here.
- South America (around 10% to 15%): A meaningful market tied closely to Brazil and broader crop cycles in the region.
- Asia/Pacific/Africa (around 5% to 10%): Smaller than the core regions, but still relevant for diversification and long-term farm mechanization demand.
- Replacement parts, services, and technology-related offerings: Not separately dominant in headline reporting, but strategically important because these activities tend to be more recurring and can support margins across equipment cycles.
AGCO has also been reshaping its portfolio. In recent years it increased its focus on higher-margin machinery, smart farming tools, and digital agriculture, while reducing exposure to some less strategic operations. That matters for long-term analysis because AGCO is no longer just a classic machinery producer; it is trying to become a more technology-enabled farm productivity company.
The broad financial picture shows how cyclical the business can be. Revenue and operating profit climbed strongly through 2023, then fell sharply in 2024 as the agricultural equipment cycle weakened, before profitability recovered in 2025. Research and development spending has remained substantial throughout the cycle, which supports AGCO’s push into premium equipment and precision farming.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Farm & Heavy Construction Machinery | |
| Market Cap ⓘ | $8.13B | |
| Beta ⓘ | 1.09 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 16.27 | 22.45 |
| P/B Ratio ⓘ | 2.15 | 1.98 |
| FCF Yield ⓘ | 4.06% | 6.31% |
| Dividend Yield ⓘ | 0.99% | 1.96% |
| EBIT / EV ⓘ | 6.64% | 4.81% |
| PEG ⓘ | 0.96 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -1.00% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | -2.07% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | -35.72% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 4.49% | 6.22% |
| Margin Growth (5Y Trend) ⓘ | -2.08% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | 15.70% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | -29.63% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 7.76% | 10.92% |
| ROA (Latest) ⓘ | 4.38% | 5.41% |
| ROIC (5Y Median) ⓘ | 16.78% | 9.21% |
| ROA (5Y Median) ⓘ | 9.23% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | -0.64 | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.73 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | -0.44 | 1.43 |
| Net Debt / Assets ⓘ | -3.89% | 19.27% |
| EBITDA / Interest ⓘ | 17.05 | 9.53 |
| Operating Margin (Latest) ⓘ | 6.92% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 8.71% | 10.27% |
| Debt to Equity (Latest) ⓘ | 2.74% | 65.48% |
| Profit Margin (Latest) ⓘ | 5.15% | 6.62% |
| Free Cash Flow (Latest) ⓘ | $330.30M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +2.10% | +58.56% |
| 12M Return (excl. last month) ⓘ | +10.50% | +15.63% |
| 6M Return ⓘ | -0.86% | +4.19% |
| Price vs. 200-Day MA ⓘ | -1.41% | +0.93% |
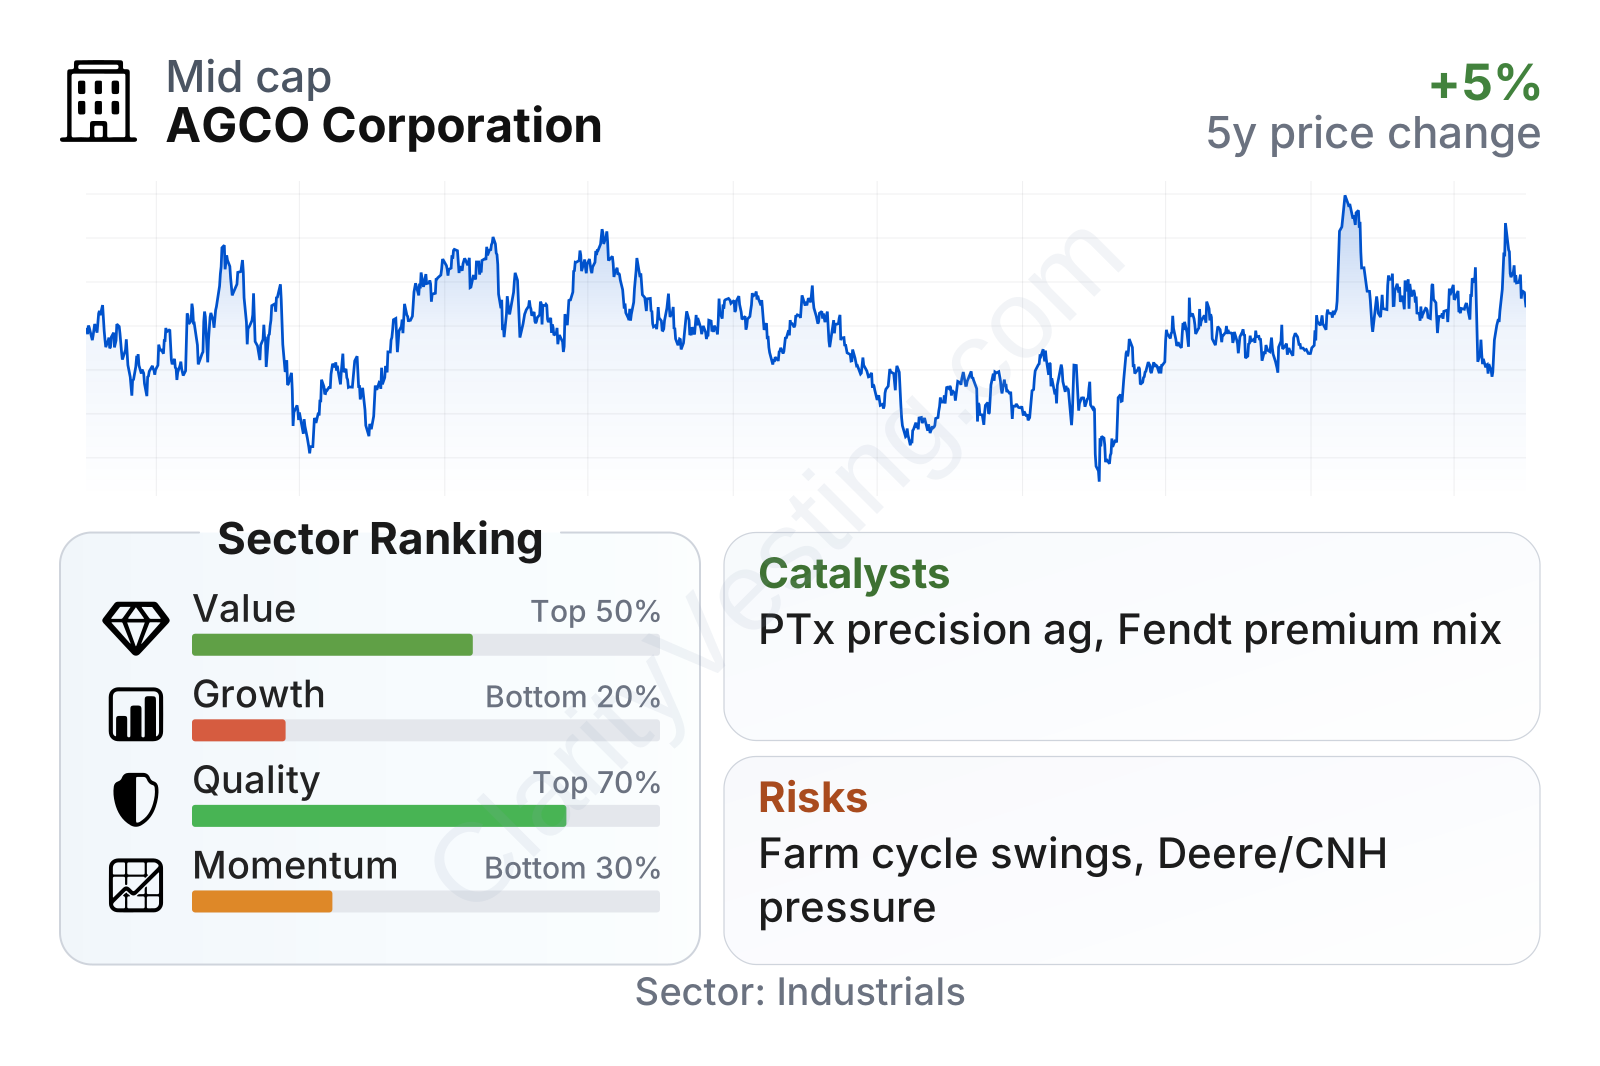
AGCO is a mid-to-large industrial company with a stock that has been noticeably cyclical rather than steadily trending upward. The latest factor summary points to a mixed profile: valuation looks somewhat less demanding than the sector on earnings multiples, balance-sheet leverage is unusually low at present, but growth and market momentum rank weakly versus peers. Quality is more balanced: recent profitability sits below sector medians, yet the company’s multi-year returns on capital have historically been stronger than many competitors.
Growth
Agricultural equipment is tied to a sector with durable long-term relevance. Farmers need to raise productivity, deal with labor shortages, reduce input waste, and adapt to more variable weather patterns. Those structural needs support demand for better machinery, automation, guidance systems, and precision spraying or planting. So while AGCO operates in a cyclical business, it also sits inside a market with long-term modernization tailwinds.
AGCO’s strategy for future growth is centered on three areas: premium equipment, precision agriculture, and a stronger recurring relationship with farmers through software, retrofit kits, and parts. The company has been building its precision agriculture capabilities through the PTx platform and partnerships around autonomy and smart farming tools. This direction makes strategic sense because technology can improve customer retention and may gradually make AGCO less dependent on pure unit volume growth.
The recent revenue trend shows why AGCO is not a simple growth case. Sales accelerated sharply in 2022 and 2023, then turned negative through much of 2024 and 2025 as the industry corrected. More recently, the pattern has become less uniformly weak, which suggests the downturn may be moderating, but growth remains uneven and still depends heavily on farm income, dealer inventories, and replacement cycles.
Cash generation has held up better than headline revenue growth. Free cash flow remains positive and has improved from the low levels seen earlier in the period, even if it is below peak levels. For a cyclical manufacturer, that matters because it shows AGCO can still produce cash during a softer demand environment. This gives the company flexibility to keep investing in product development, manufacturing upgrades, and precision technology.
A meaningful catalyst is the ongoing shift toward smarter equipment. Farmers increasingly want machines that can reduce seed, fertilizer, and chemical usage while improving yield and labor efficiency. AGCO is not the largest player in the industry, but it is pushing hard in exactly those categories. Another positive development is the continued strength of the Fendt brand, which gives AGCO an attractive premium position in several markets. If farm equipment demand stabilizes and precision adoption continues to expand, AGCO has a credible path to better growth than a simple rebound in tractor shipments alone would suggest.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


