Stock Analysis · First Majestic Silver Corp (AG)
Overview
First Majestic Silver Corp is a precious-metals mining company focused mainly on silver production, with additional revenue from gold and smaller by-product metals. The company operates producing mines in Mexico and also owns the Jerritt Canyon gold project in Nevada, which has been under review and repositioning rather than serving as a major current contributor. Its business is straightforward: explore for mineral deposits, mine ore, process it, and sell the recovered metals into global commodity markets.
Revenue is driven primarily by metal sales, so results depend heavily on production volumes and realized silver and gold prices. Based on the company’s recent reporting structure, the main revenue sources are approximately:
- Silver sales: about 50% to 60% of revenue. This is the company’s core product and the main reason it is followed as a silver-focused miner.
- Gold sales: about 35% to 45% of revenue. Gold has become a meaningful earnings support, especially when silver grades or prices are uneven.
- Lead and zinc and other by-products: generally less than 10% combined. These come from polymetallic ore and help offset mining costs.
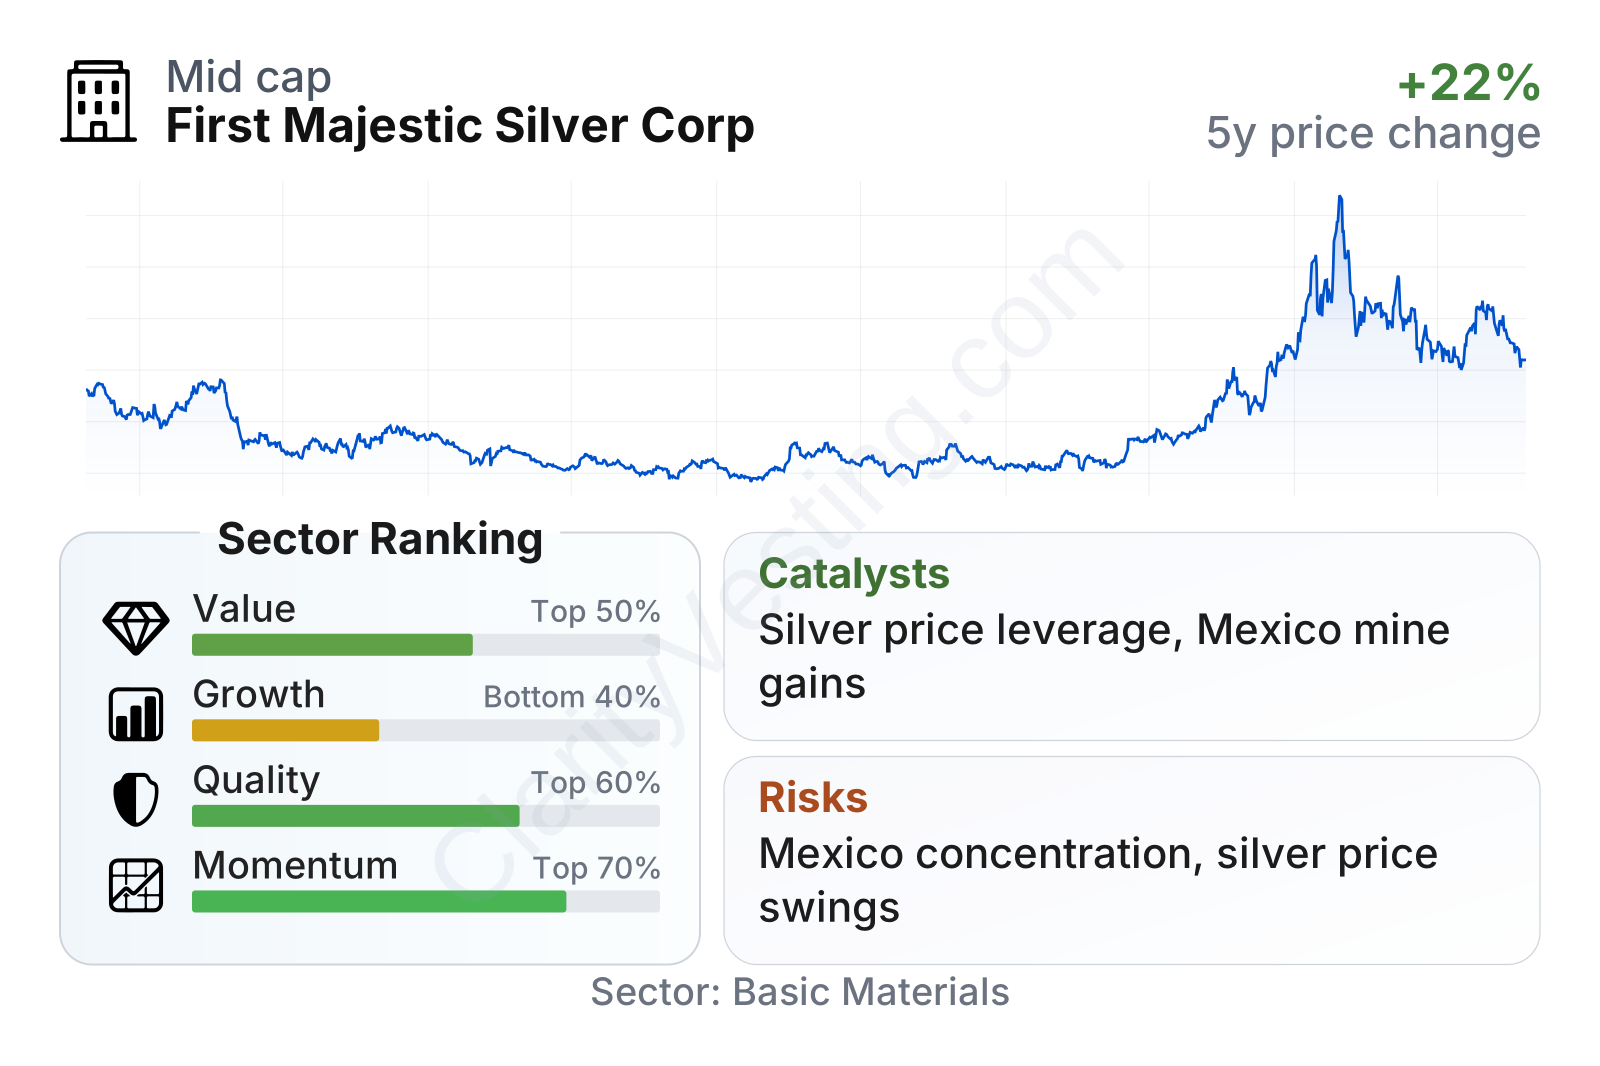
The operating base is concentrated in Mexico, especially around the San Dimas, Santa Elena, and La Encantada assets. That concentration gives the company technical familiarity and operational focus, but it also ties a large part of its future to one country’s tax, permitting, labor, and political environment.
Over the last few years, the business has looked cyclical rather than linear. Revenue was relatively flat to down through 2023 and 2024, then improved sharply in 2025 as metal prices and operating performance strengthened. The cost structure also improved materially: gross profit expanded from a very weak level in 2022-2023 to a much healthier level in 2025, showing how strongly earnings can react when production and pricing move in the right direction.
The visual breakdown highlights a major turnaround. Earlier years showed thin or negative operating income despite meaningful sales, while the latest full-year picture shows much wider gross profit and a return to positive net income. That shift matters because mining companies often look dramatically different when costs, grades, and metal prices align at the same time.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Silver | |
| Market Cap ⓘ | $7.88B | |
| Beta ⓘ | 2.19 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 22.84 | 16.92 |
| P/B Ratio ⓘ | 3.16 | 1.66 |
| FCF Yield ⓘ | 8.82% | 5.83% |
| Dividend Yield ⓘ | 0.29% | 2.07% |
| EBIT / EV ⓘ | 8.61% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 57.30% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 2.42% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | -4.29% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 6.51% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.08% | 9.59% |
| ROA (Latest) ⓘ | 7.57% | 4.92% |
| ROIC (5Y Median) ⓘ | -0.57% | 7.91% |
| ROA (5Y Median) ⓘ | -5.15% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.97 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.74 | 0.93 |
| Net Debt / Assets ⓘ | -15.43% | 13.69% |
| EBITDA / Interest ⓘ | 56.77 | 12.38 |
| Operating Margin (Latest) ⓘ | 47.80% | 13.24% |
| Operating Margin (5Y Median) ⓘ | -1.87% | 11.82% |
| Debt to Equity (Latest) ⓘ | 11.17% | 40.30% |
| Profit Margin (Latest) ⓘ | 21.18% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $695.50M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +191.53% | +73.47% |
| 12M Return (excl. last month) ⓘ | +82.26% | +27.59% |
| 6M Return ⓘ | -19.73% | -4.02% |
| Price vs. 200-Day MA ⓘ | -20.06% | -0.65% |
First Majestic is now a large precious-metals producer by public-market standards, with a market value in the multi-billion-dollar range, but the stock remains volatile, reflected in a beta above 2. On valuation metrics, the shares trade above sector medians on earnings and book value, which suggests the market is already assigning a premium. At the same time, cash generation and operating returns have recently improved enough to place the company in a stronger position on free cash flow and operating profitability than many peers.
The table also shows an unusual mix: near-term growth and quality metrics have improved sharply, while longer-term growth measures remain weaker. In plain language, the latest period looks much better than the company’s five-year record. That is encouraging, but it also means the market may be pricing a recovery that still needs to prove it can last.
Growth
First Majestic operates in a sector with long-term relevance. Silver is both a precious metal and an industrial input, used in solar panels, electronics, power systems, and other electrical applications. That gives silver demand a different profile from gold alone. Over time, clean-energy infrastructure and electrification can support the industry, although actual silver prices still move in cycles and often react to interest rates, currency trends, and investor sentiment.
The company’s strategy is reasonably easy to understand: keep a strong focus on silver-heavy assets, improve recoveries and costs at existing mines, and use its portfolio to benefit when silver prices rise. That approach makes strategic sense for a company trying to preserve leverage to silver rather than dilute its identity into a broad mining conglomerate. The key question is not whether the strategy is coherent, but whether operations can stay consistent enough to convert stronger metal prices into durable cash flow.
Revenue growth recently accelerated sharply after a difficult period. The company moved from declines and uneven quarterly comparisons in 2023 and parts of 2024 to very strong year-over-year gains through 2025 and into 2026. That pace is much stronger than the sector median in the latest reading, although part of the surge reflects recovery from a weak base rather than purely steady organic expansion.
Cash generation tells an equally important part of the picture. Free cash flow was negative in earlier periods, then turned strongly positive, reaching a very high trailing level. For a miner, this matters more than headline production alone because free cash flow is what allows debt reduction, reinvestment, balance-sheet flexibility, and shareholder returns without relying as much on outside financing.
A key catalyst is the company’s direct sensitivity to silver prices. If silver remains elevated or continues rising, First Majestic can benefit disproportionately because of its focused exposure. Another potential driver is operational optimization at its main mines, where better grades, throughput, or recoveries can have an outsized impact on margins. Recent company updates have also pointed to ongoing mine-plan refinement and exploration around existing operations, which can extend asset life and support future output without requiring an entirely new flagship mine.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


