Stock Analysis · Agnico Eagle Mines Limited (AEM)
Overview
Agnico Eagle Mines Limited is a large gold mining company that explores for, develops, and operates mines. Its business is straightforward to understand: it digs precious metals out of the ground, processes them, and sells them into global markets. The company’s mining operations are concentrated in countries generally viewed as mining-friendly, especially Canada, as well as Australia, Finland, and Mexico. That geographic mix matters because political stability and permitting rules can strongly affect mining businesses over long periods.
The company’s revenue comes mainly from selling gold, with smaller contributions from other metals produced alongside gold. Based on company reporting in recent annual filings, the mix is heavily centered on gold and only modestly supported by by-product metals.
- Gold: about 95% to 97% of revenue. This is the core business and includes production from the company’s main mines across Canada, Australia, Finland, and Mexico.
- Silver: about 2% to 4% of revenue. Silver is largely a by-product from certain mining operations rather than the main economic focus.
- Zinc and other metals: usually below 2% of revenue combined. These amounts can vary by mine and by year depending on grades and production mix.
For a long-term reader, the key point is simple: Agnico Eagle is not a diversified metals company in the broad sense. It is primarily a gold producer, so its results are closely tied to gold prices, production volumes, operating costs, and the quality of its mine portfolio.
The business has also become much larger over the last several years, helped by acquisitions and strong operating performance. Revenue has risen sharply since 2021, while costs have increased much more slowly than sales in recent periods, which has supported a major improvement in profitability.
The long-term trend shows a meaningful expansion in revenue and operating income, with net income rising even faster in the most recent periods. That suggests the company has recently benefited from both larger scale and a stronger gold price environment, not just from producing more ounces.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $94.31B | |
| Beta ⓘ | 0.64 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 15.93 | 16.92 |
| P/B Ratio ⓘ | 3.30 | 1.66 |
| FCF Yield ⓘ | 4.77% | 5.83% |
| Dividend Yield ⓘ | 0.91% | 2.07% |
| EBIT / EV ⓘ | 9.04% | 6.38% |
| PEG ⓘ | 28.15 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 35.00% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 10.59% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 31.67% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 18.99% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 30.51% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 80.86% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 6.50% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 22.35% | 9.59% |
| ROA (Latest) ⓘ | 16.57% | 4.92% |
| ROIC (5Y Median) ⓘ | 9.04% | 7.91% |
| ROA (5Y Median) ⓘ | 6.46% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.36 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.68 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.30 | 0.93 |
| Net Debt / Assets ⓘ | -8.32% | 13.69% |
| EBITDA / Interest ⓘ | 142.59 | 12.38 |
| Operating Margin (Latest) ⓘ | 60.13% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 35.10% | 11.82% |
| Debt to Equity (Latest) ⓘ | 1.12% | 40.30% |
| Profit Margin (Latest) ⓘ | 40.44% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $4.50B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +295.71% | +73.47% |
| 12M Return (excl. last month) ⓘ | +23.59% | +27.59% |
| 6M Return ⓘ | -7.31% | -4.02% |
| Price vs. 200-Day MA ⓘ | -0.96% | -0.65% |
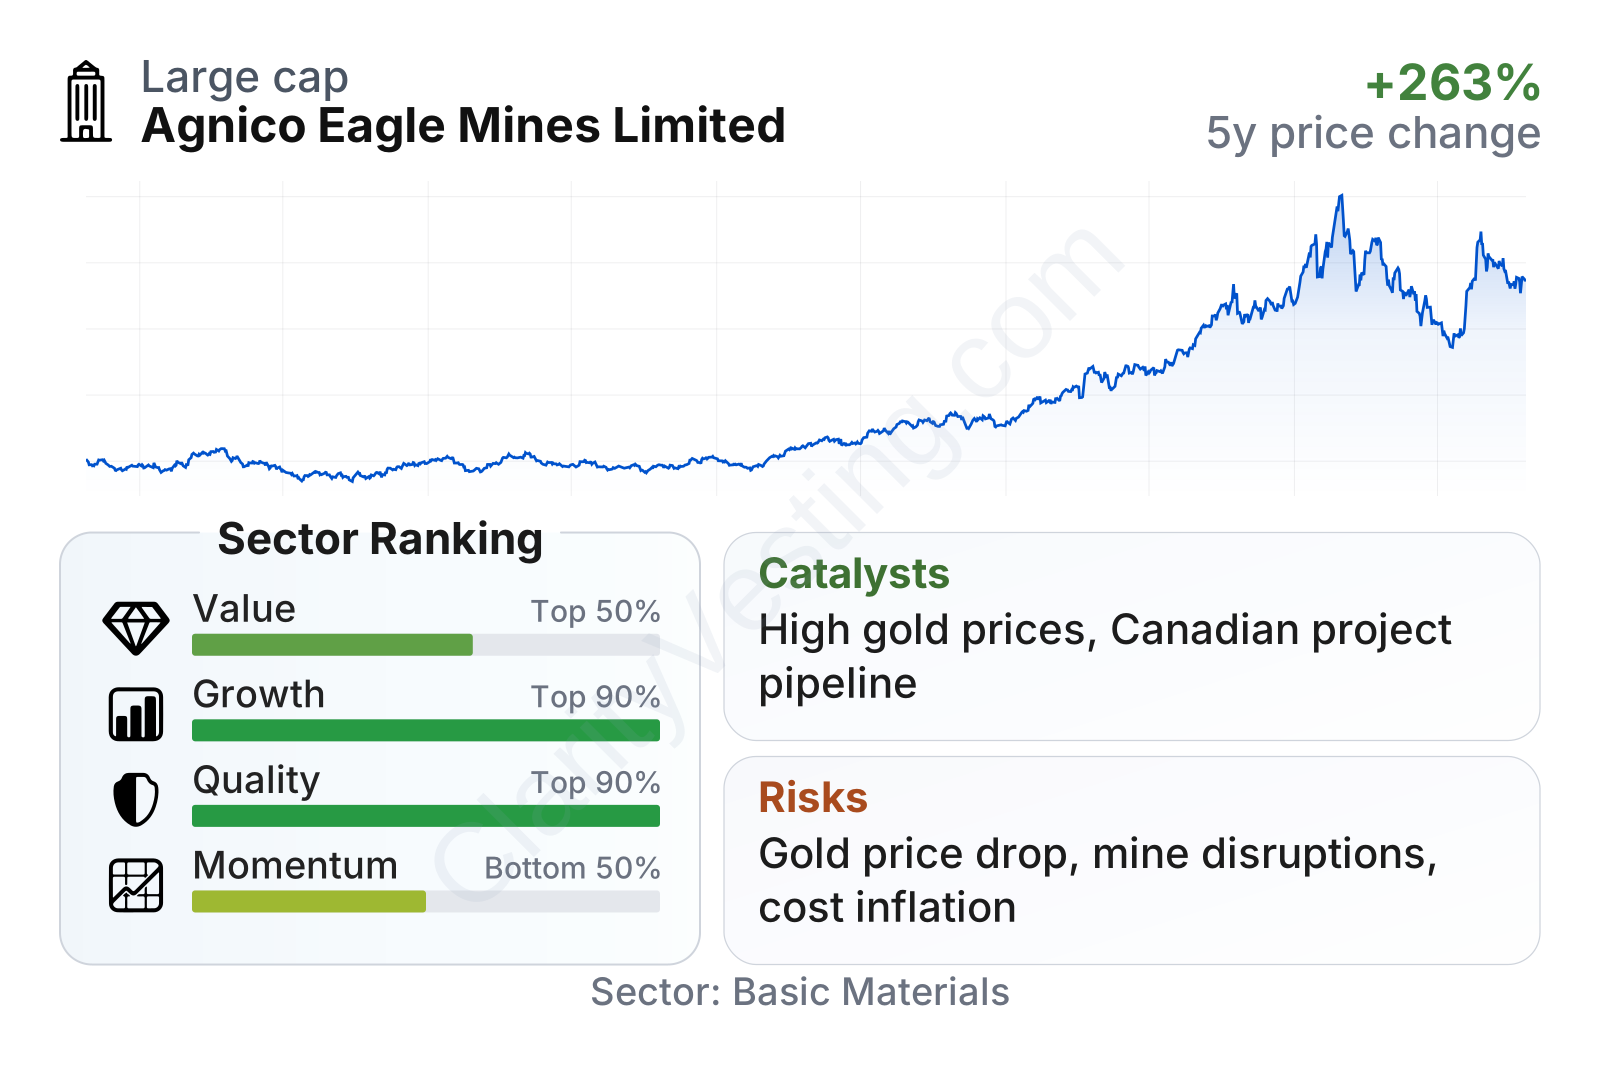
Agnico Eagle stands out on growth and quality relative to much of the gold sector. Revenue growth, earnings growth, returns on capital, and margins are all well above typical industry levels, while leverage is exceptionally low. On value, the picture is more mixed: the earnings multiple is close to the sector median, but the price-to-book ratio is notably richer, which reflects the market placing a premium on the company’s asset quality and execution.
The share price history shows a powerful multi-year re-rating, especially from 2024 into 2026, although with visible swings along the way. That pattern is common in gold equities: strong upside during favorable metal-price periods, but with volatility that can be sharp even when business fundamentals remain solid.
Growth
Gold mining is not a classic high-volume growth sector like software or semiconductors, but it can still be attractive over long periods when companies own long-life assets, replace reserves, and maintain cost discipline. The broader backdrop for gold remains supportive when inflation stays elevated, real interest rates are uncertain, central banks keep adding gold reserves, or markets seek defensive assets. Those forces do not guarantee higher prices, but they can create a constructive environment for major producers.
Agnico Eagle’s strategy appears coherent for long-term growth because it combines three important features: a concentration on lower-risk mining jurisdictions, continuous mine optimization, and disciplined balance sheet management. In mining, growth is not only about opening new projects. It is also about extending mine lives, improving recoveries, developing nearby deposits, and keeping costs under control while preserving future production.
Revenue growth has been consistently strong over the last several years and has remained well above the sector median. The recent pace suggests that Agnico Eagle has been benefiting from a combination of higher production value and favorable pricing, rather than relying on one-off gains.
Free cash flow has improved dramatically, climbing from well below $1 billion a few years ago to roughly $4.5 billion on a trailing basis. That is one of the most important signals in a mining company because free cash flow is what funds dividends, project development, exploration, acquisitions, and balance sheet strength without depending heavily on new borrowing.
Recent company updates have also pointed to continued progress at core assets and pipeline projects, including ongoing development work in northern Canada. For Agnico Eagle, one of the clearest catalysts is its ability to convert its large land position around existing mines into additional reserves and future production. That is often more valuable than building entirely new mines from scratch because surrounding infrastructure is already in place.
Another near-term opportunity is simple but powerful: if gold prices remain elevated, large low-leverage producers like Agnico Eagle can see an outsized benefit in margins and cash generation. The company has already shown that higher realized prices can flow through strongly to earnings and free cash flow.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


