Stock Analysis · Advanced Energy Industries Inc (AEIS)
Overview
Advanced Energy Industries, Inc. designs and manufactures highly engineered power conversion, measurement, and control solutions. In simpler terms, it builds the equipment that helps advanced manufacturing systems receive stable power, control critical processes, and measure performance accurately. Its products are used in demanding environments such as semiconductor manufacturing, industrial production, medical equipment, telecommunications, and data center infrastructure.
The company is especially tied to semiconductor equipment, where precise power delivery is essential for wafer fabrication tools. Over time, Advanced Energy has also expanded into industrial and mission-critical power markets through acquisitions and product development, which gives it exposure beyond one end market.
Based on recent company filings, revenue is primarily organized by end market rather than by individual product line. The main sources of revenue are approximately:
- Semiconductor equipment: about 60% to 70% of revenue. This includes power systems, RF power, controls, and matching networks used in wafer fabrication and related semiconductor tools.
- Industrial and medical: about 20% to 30% of revenue. This includes precision power and control products used in factory automation, analytical instruments, imaging, and medical applications.
- Data center computing, telecom, and networking: about 10% to 15% of revenue. This includes power conversion products supporting computing infrastructure and communications equipment.
That mix matters for long-term analysis. Semiconductor demand can be cyclical, but it also benefits from structural drivers such as AI computing, more advanced chips, and rising electronics content across industries. The broader industrial and critical-power businesses help reduce dependence on one market, even if semiconductors still dominate the picture.
The business profile shows a company that can scale revenue meaningfully in stronger years, but earnings have been more volatile than sales. Gross profit has remained sizable over time, while research, development, and operating costs have also stayed elevated, reflecting the technical nature of its markets and the need to keep investing in product capability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Electrical Equipment & Parts | |
| Market Cap ⓘ | $9.60B | |
| Beta ⓘ | 1.31 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 44.38 | 22.29 |
| P/B Ratio ⓘ | 7.19 | 1.98 |
| FCF Yield ⓘ | 0.90% | 6.26% |
| Dividend Yield ⓘ | 0.17% | 1.92% |
| EBIT / EV ⓘ | 2.30% | 4.83% |
| PEG ⓘ | 2.77 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 30.00% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 5.26% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -10.05% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 11.69% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -0.15% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 3.82% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 0.19% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.75% |
| ROA (Latest) ⓘ | 7.48% | 5.41% |
| ROIC (5Y Median) ⓘ | 8.87% | 9.37% |
| ROA (5Y Median) ⓘ | 6.17% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -0.08 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.27 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -0.06 | 1.39 |
| Net Debt / Assets ⓘ | -0.57% | 19.27% |
| EBITDA / Interest ⓘ | 22.07 | 9.58 |
| Operating Margin (Latest) ⓘ | 12.62% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 10.31% | 10.30% |
| Debt to Equity (Latest) ⓘ | 94.57% | 64.82% |
| Profit Margin (Latest) ⓘ | 10.77% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $86.70M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +174.71% | +67.77% |
| 12M Return (excl. last month) ⓘ | +50.92% | +12.05% |
| 6M Return ⓘ | -35.66% | 0.00% |
| Price vs. 200-Day MA ⓘ | -19.77% | +0.67% |
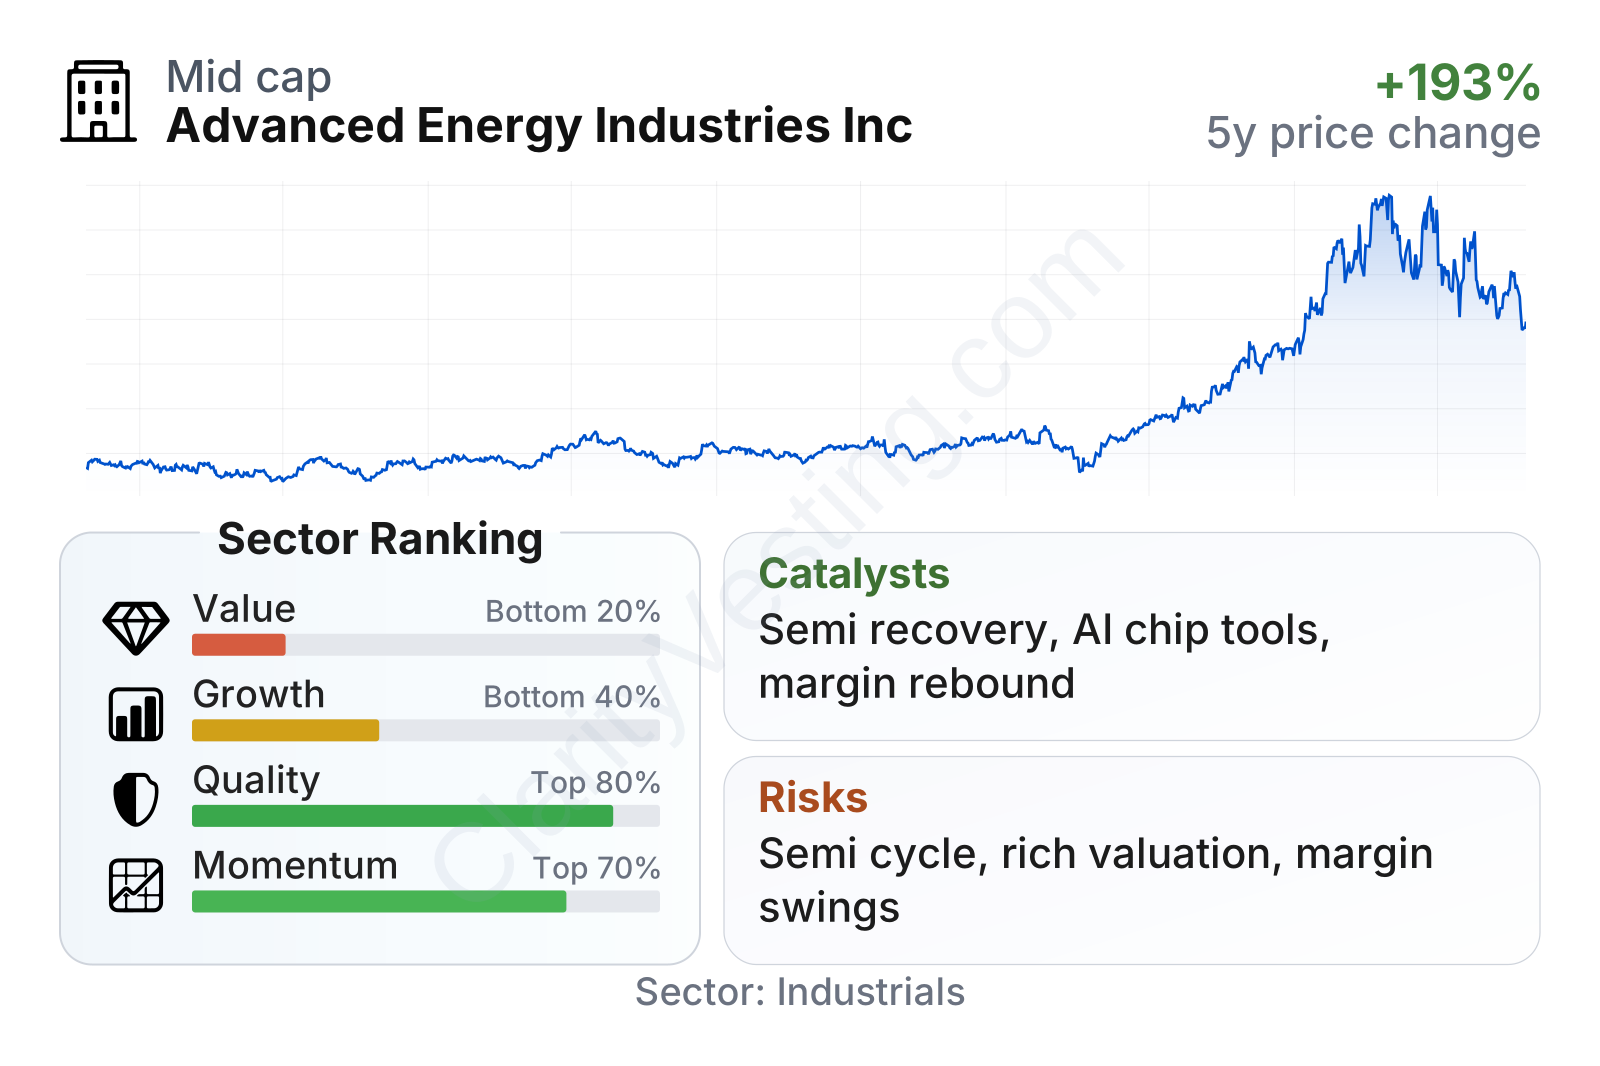
Advanced Energy is a large mid-cap to lower large-cap industrial technology company with above-average share-price volatility, as reflected by a beta around 1.3. The overall profile is mixed: profitability and balance-sheet quality look stronger than much of the sector, while valuation appears demanding. Quality metrics are supported by profit margins above sector norms, solid returns on assets, strong interest coverage, and a net cash position relative to earnings measures. By contrast, value metrics rank weakly, with earnings and book-value multiples well above sector medians and a low free-cash-flow yield. Growth is currently improving sharply, but the longer five-year record is less impressive than the recent rebound suggests.
Growth
Advanced Energy operates in markets that should continue growing over the long run, especially semiconductor manufacturing and high-performance power systems. Semiconductor equipment remains the most important driver. As chips become more complex, the tools used to manufacture them require tighter power control, more precision, and higher reliability. That plays directly into the company’s specialization.
The strategy also makes sense for future growth because the company is not just selling commodity electrical parts. It focuses on precision power and control systems that are deeply integrated into customer equipment. That makes the products harder to replace and can support recurring design wins as customers move to next-generation tools.
Recent revenue trends point to a meaningful rebound. After a downturn in 2023 and much of 2024, year-over-year growth turned positive again and accelerated into 2025 and 2026, recently reaching around 30%. That is well above the sector median and suggests the business is benefiting from a cyclical recovery as well as healthy demand in its core markets.
Cash generation is positive, but it has not followed the same strong upward pattern as revenue. Free cash flow over the trailing twelve months remains relatively modest compared with the company’s market value, and it has softened from earlier peaks. For long-term analysis, that means the recovery is real, but it still needs to convert more efficiently into cash on a sustained basis.
One of the clearest catalysts is the ongoing buildout of advanced semiconductor capacity, especially where power-intensive and precision-sensitive fabrication steps are required. The rise of AI-related infrastructure can also help indirectly, since more advanced chips and supporting electronics increase demand for sophisticated production tools. In addition, the company’s broader presence in industrial and critical-power markets may provide a second lane of expansion if factory automation and digital infrastructure spending remain healthy.
Recent company communications have also emphasized stronger demand trends and improving order patterns in parts of the semiconductor market. For a business like Advanced Energy, even moderate recovery in wafer-fab equipment can have a noticeable effect because of its high exposure to that segment.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


