Stock Analysis · Addus HomeCare Corporation (ADUS)
Overview
Addus HomeCare Corporation is a healthcare services company focused on care delivered in the home. Its goal is to help people, especially older adults and individuals with chronic conditions or disabilities, remain in their homes rather than move into more expensive institutional settings. The company operates across three main service lines: personal care, hospice, and home health.
The business is built around recurring care needs rather than one-time procedures. That makes demand more closely tied to aging demographics, long-term illness, disability support, and end-of-life care. A large share of reimbursement comes from government programs such as Medicaid and Medicare, which is important because it gives the company access to a large patient base but also exposes it to policy and payment-rate changes.
Based on the company’s recent filings, revenue is mainly generated from the following activities:
- Personal care: about 76% of revenue. This includes assistance with daily living activities such as bathing, grooming, meal preparation, medication reminders, and other non-medical support services, largely reimbursed by Medicaid and other government programs.
- Hospice: about 17% of revenue. Hospice provides end-of-life care, pain management, emotional support, and related services, primarily reimbursed by Medicare.
- Home health: about 7% of revenue. Home health includes skilled nursing, therapy, and clinical services provided at home, often after hospitalization or for chronic-care management.
The mix matters because personal care is the company’s economic foundation, while hospice and home health can add higher clinical complexity and, in some cases, better cross-selling opportunities. Over time, management has been building a broader home-based care platform instead of relying on only one service category.
The earnings flow has also improved in recent years. Revenue has risen steadily from 2021 through 2025, while operating income and net income have expanded faster than sales, suggesting that scale and execution have supported margins rather than growth coming only from added volume.
The business has become meaningfully larger over the past few years, and profit conversion has improved alongside that expansion. That is a positive sign for a care provider, since labor-heavy models do not always translate rising sales into stronger earnings.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Care Facilities | |
| Market Cap ⓘ | $2.20B | |
| Beta ⓘ | 0.83 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.69 | 25.42 |
| P/B Ratio ⓘ | 1.97 | 3.08 |
| FCF Yield ⓘ | 6.95% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | 6.98% | 0.56% |
| PEG ⓘ | 1.01 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.00% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 9.41% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -4.17% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 13.26% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 1.97% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | 31.37% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.35% | 3.17% |
| ROA (Latest) ⓘ | 7.31% | 2.98% |
| ROIC (5Y Median) ⓘ | 8.61% | 4.56% |
| ROA (5Y Median) ⓘ | 6.04% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 0.06 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.42 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 0.06 | 1.00 |
| Net Debt / Assets ⓘ | 0.64% | 5.06% |
| EBITDA / Interest ⓘ | 16.83 | 9.55 |
| Operating Margin (Latest) ⓘ | 10.20% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 8.73% | 7.33% |
| Debt to Equity (Latest) ⓘ | 9.48% | 26.68% |
| Profit Margin (Latest) ⓘ | 7.13% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $153.06M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +53.55% | +51.61% |
| 12M Return (excl. last month) ⓘ | +0.04% | +19.90% |
| 6M Return ⓘ | +29.44% | +10.10% |
| Price vs. 200-Day MA ⓘ | +15.72% | +6.44% |
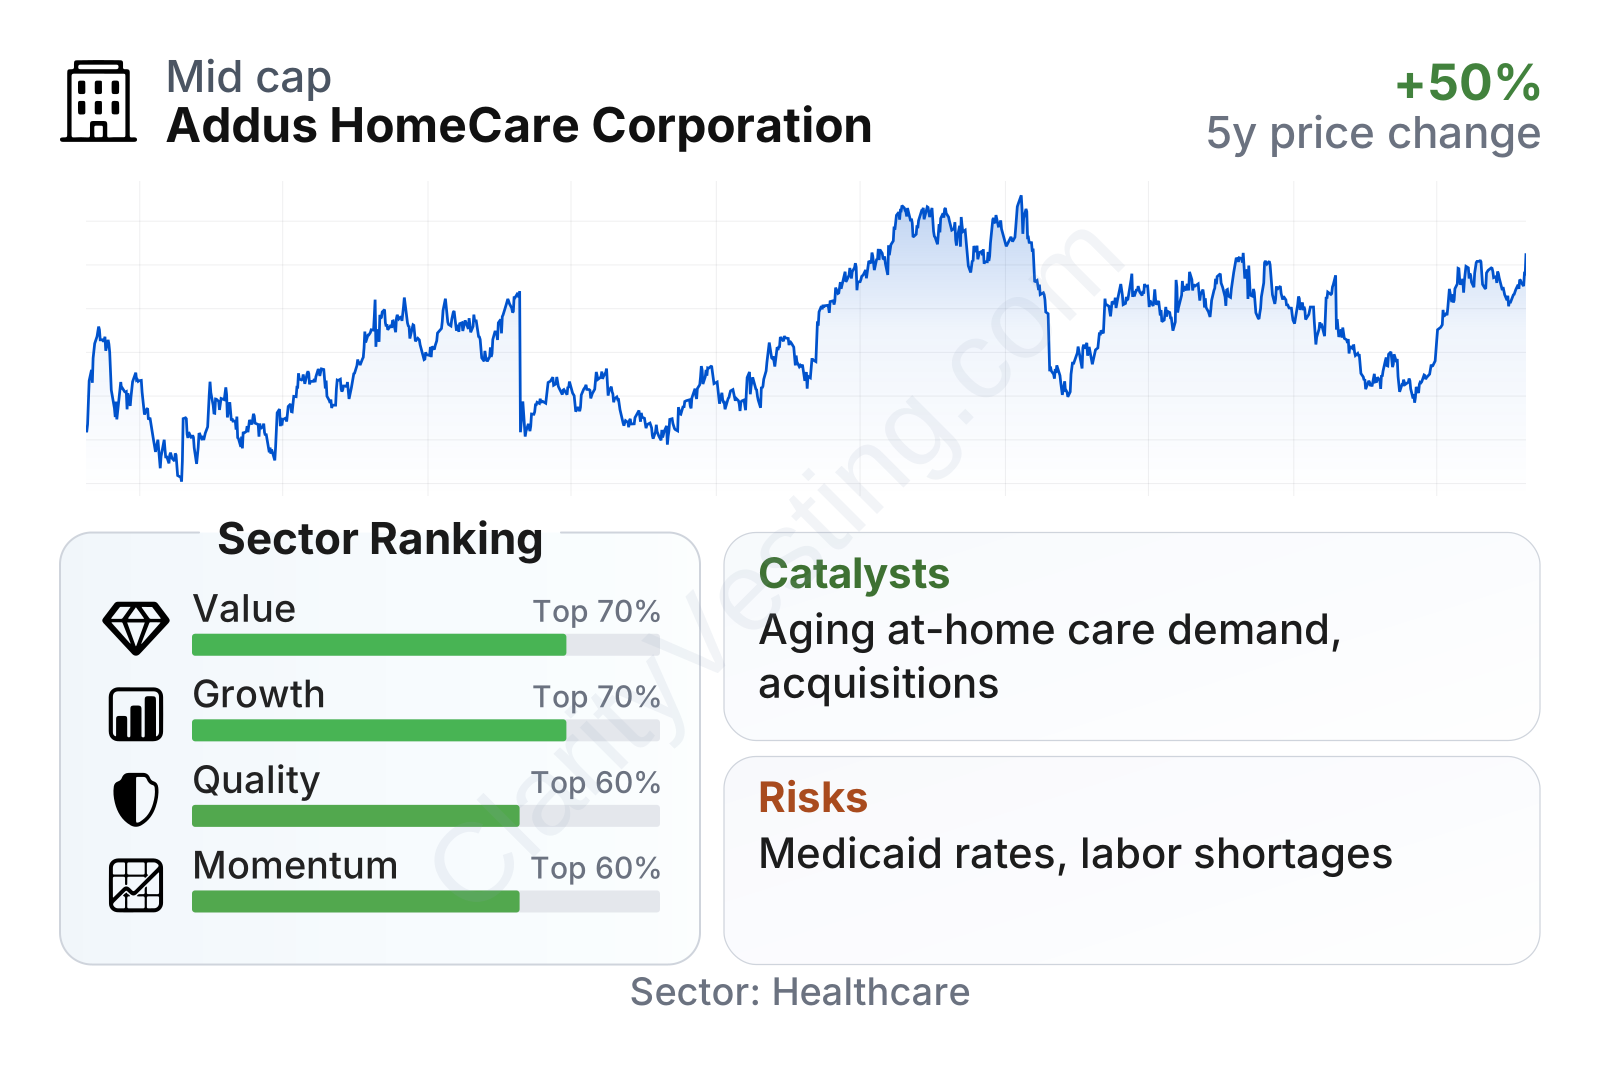
Addus is a mid-sized healthcare company with relatively low share-price volatility for the sector, reflected in a beta below 1. On fundamentals, the company stands out more for balance-sheet strength, cash generation, and profitability than for market momentum. Value metrics look moderate rather than stretched, growth is above the sector median in several areas, and quality measures are solid, especially returns on capital, margins, and low leverage. The weaker area is recent stock performance compared with much of the healthcare sector, even though the underlying business metrics remain healthy.
Growth
Home-based care is part of a growing segment of healthcare. The long-term demand driver is straightforward: the U.S. population is aging, and many patients, families, and payers prefer care at home when it is clinically appropriate. Home care is often less expensive than facility-based care, which aligns with the interests of Medicaid managed care plans, state agencies, and Medicare reimbursement systems. That creates a structural tailwind for providers that can operate at scale and manage workforce availability.
Addus’s strategy is consistent with that trend. The company has expanded both organically and through acquisitions, while keeping its center of gravity in personal care. This approach makes sense because personal care can create local relationships with patients earlier in the care journey, while hospice and home health broaden the services offered as needs become more complex. In simple terms, Addus is trying to become a larger home-based care network around the patient rather than a single-service operator.
Revenue growth has been consistently positive for years. Growth ran around high single digits to low double digits for much of 2022 through 2024, accelerated sharply during 2025, and then normalized back to around 8% in the first half of 2026. That pattern suggests the company benefited from acquisition support and integration gains, with a still-positive underlying demand backdrop after the tougher comparison period.
Cash generation supports the growth case. Free cash flow has trended upward over the past several years, despite some interim fluctuations, and remains strong enough to give the company flexibility for acquisitions, debt reduction, and internal investment. For a healthcare services provider, that matters because growth by acquisition only works well if the underlying business also converts earnings into cash.
A notable catalyst in recent years has been Addus’s continued consolidation of fragmented local markets. Home care remains highly fragmented, and scale can matter in recruiting caregivers, dealing with managed care organizations, spreading administrative costs, and extending services across neighboring geographies. The company has repeatedly used acquisitions to widen its footprint and strengthen its home-based care platform. Recent company communications have also emphasized demand for personal care services and the role of cost-effective in-home support within state and payer budgets, which reinforces the long-term opportunity.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


