Stock Analysis · Aecom Technology Corporation (ACM)
Overview
AECOM is a global professional services company focused on infrastructure. In simple terms, it helps governments, transportation agencies, utilities, and private clients plan, design, manage, and deliver large projects such as highways, bridges, rail systems, water networks, environmental remediation, energy facilities, and buildings. The company has moved away from more volatile, lower-margin construction exposure over time and is now centered on consulting, engineering, program management, and technical advisory work.
Its revenue base is broad, but it is concentrated in advisory and project delivery services tied to public and regulated infrastructure spending. Based on recent company reporting, the business is largely organized around its Americas and International operations, with most activity coming from design, consulting, and program management rather than self-performed construction.
The main revenue sources can be summarized as follows:
- Americas segment: approximately 65% to 70% of revenue. This includes transportation, water, environmental, buildings, program management, and advisory work across the U.S., Canada, and Latin America.
- International segment: approximately 30% to 35% of revenue. This covers similar services in regions such as Europe, the Middle East, Asia, and Australia.
- By end market, transportation is the largest category, followed by water, environment, buildings and places, and energy-related work. Exact percentages by end market are not always disclosed in a way that allows a precise current split, but transportation and public-sector infrastructure are clearly the core of the business.
- Public-sector clients represent the large majority of activity, with national, state, and local agencies forming the backbone of demand. Private-sector work is meaningful but smaller.
A notable feature of AECOM’s model is that it earns fees from expertise and project oversight rather than from taking large amounts of direct construction risk. That generally supports steadier margins, lower capital intensity, and better visibility through a backlog of signed work.
The longer-term financial pattern shows a business that has expanded revenue and gross profit over several years, while net income has been more uneven. That mix fits a project-based engineering firm: top-line demand can be healthy, but bottom-line results still depend on execution, utilization, contract mix, and financing costs.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $7.57B | |
| Beta ⓘ | 0.91 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.94 | 22.45 |
| P/B Ratio ⓘ | 3.81 | 1.98 |
| FCF Yield ⓘ | 2.69% | 6.31% |
| Dividend Yield ⓘ | 2.00% | 1.96% |
| EBIT / EV ⓘ | 3.91% | 4.81% |
| PEG ⓘ | 0.65 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -14.20% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 7.96% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | -9.00% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | -0.25% | 6.22% |
| Margin Growth (5Y Trend) ⓘ | 1.96% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | 4.77% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | -54.96% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 6.40% | 10.92% |
| ROA (Latest) ⓘ | 2.38% | 5.41% |
| ROIC (5Y Median) ⓘ | 10.36% | 9.21% |
| ROA (5Y Median) ⓘ | 2.72% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | -1,922.18 | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.46 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | -906.32 | 1.43 |
| Net Debt / Assets ⓘ | -6308.24% | 19.27% |
| EBITDA / Interest ⓘ | 4.14 | 9.53 |
| Operating Margin (Latest) ⓘ | 2.56% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 5.03% | 10.27% |
| Debt to Equity (Latest) ⓘ | 151.92% | 65.48% |
| Profit Margin (Latest) ⓘ | 1.87% | 6.62% |
| Free Cash Flow (Latest) ⓘ | $203.45M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -26.67% | +58.56% |
| 12M Return (excl. last month) ⓘ | -45.29% | +15.63% |
| 6M Return ⓘ | -29.93% | +4.19% |
| Price vs. 200-Day MA ⓘ | -26.21% | +0.93% |
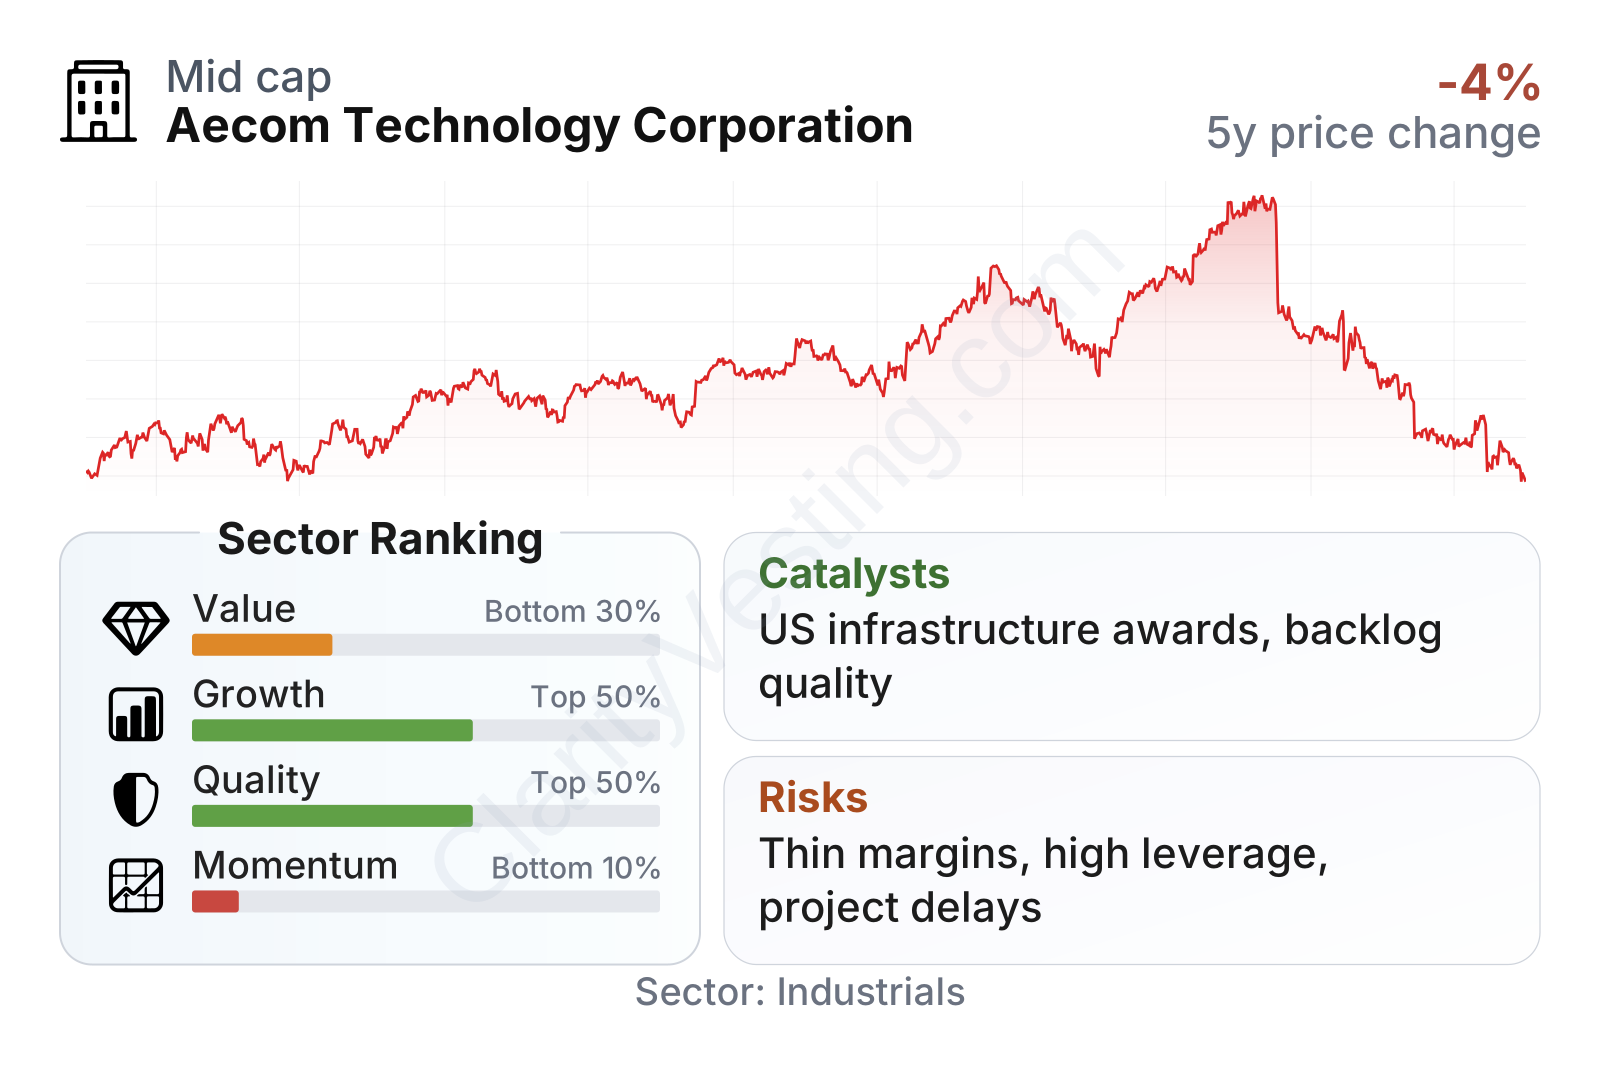
AECOM is a mid-sized infrastructure services company with a stock that has been notably weaker than much of its industrial peer group in recent months. On the factor breakdown, growth and quality sit around the sector middle, while value looks less compelling and momentum is clearly weak. The balance sheet shows a high debt-to-equity ratio relative to peers, but cash generation remains positive. The current earnings multiple is close to the sector median, which suggests the market is not giving the company a major premium despite its exposure to attractive infrastructure themes.
Growth
Infrastructure is a favorable long-term market. Aging transport systems, water stress, grid modernization, environmental cleanup, resilience spending, and urban development all support multi-year demand for engineering and program management. This is especially relevant for AECOM because much of its work is tied to essential assets that governments and utilities cannot easily postpone forever.
AECOM’s strategy also makes sense for this environment. The company has spent years reshaping itself toward higher-value consulting and program management, where client relationships, technical credentials, and regulatory knowledge matter more than pure construction scale. That shift can improve resilience because advisory work usually requires less capital and avoids some of the fixed-price construction risks that have hurt many contractors.
Recent growth has been less smooth than the long-term demand backdrop would suggest. Revenue growth was strong through much of 2023 and 2024, then slowed sharply and recently turned negative on a year-over-year basis. That does not automatically mean the underlying market is deteriorating; for project firms, timing, portfolio mix, and comparisons against prior periods can create swings. Still, it shows that AECOM is not delivering a straight-line growth pattern.
Cash generation is an important positive. Free cash flow has remained positive over time, although the latest level is well below the stronger period seen around 2025. For a professional services firm, this matters because cash conversion helps fund share repurchases, debt service, selective acquisitions, and dividends without relying too heavily on external financing.
One of the strongest catalysts is the company’s position in large public infrastructure programs, particularly in the United States. Federal support for transportation, water, environmental remediation, and energy-transition related upgrades creates a multi-year pipeline of opportunities. AECOM is also active in program management for complex projects, a niche that can benefit when governments choose outside specialists to coordinate multi-contractor developments. In recent company communications, management has emphasized backlog quality, margin discipline, and demand tied to resilience, water, transit, and environmental services. Those are areas with durable spending logic rather than short-lived trends.
Another opportunity is geographic and technical breadth. AECOM can cross-sell services across planning, design, environmental review, permitting, engineering, and project oversight. Once a firm is embedded early in a project lifecycle, it can often win follow-on work in later stages. That does not guarantee rapid growth, but it can strengthen visibility and client retention.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


