Stock Analysis · ABB Turbo Systems AG (ACLLY)
Overview
ABB Turbo Systems AG, now operating under the Accelleron name, supplies turbochargers, fuel injection systems, digital monitoring tools, and service solutions for large engines used mainly in marine vessels, power generation, rail, and heavy industrial applications. In simple terms, it helps very large engines run more efficiently, with better fuel use, lower emissions, and higher reliability. That makes the company closely tied to global shipping, energy infrastructure, and the gradual upgrade of existing engine fleets rather than to short consumer cycles.
The business model is especially attractive because a large installed base of equipment creates recurring service demand over many years. New equipment matters, but long-term economics are supported by maintenance, spare parts, upgrades, and digital services once a turbocharger is already operating in the field.
Based on company reporting, revenue is mainly organized around two broad sources:
- Service revenue: about 70% of sales. This includes spare parts, maintenance, repairs, overhauls, service agreements, and digital or lifecycle support for equipment already installed.
- Original equipment revenue: about 30% of sales. This includes turbochargers and related systems sold for new ships, power generation assets, rail applications, and industrial engines.
By end market, marine is the dominant exposure, with energy and other industrial uses making up the rest. The exact mix can move from year to year, but the core pattern is clear: a service-heavy industrial company with a strong position in critical engine components.
The business has also shown improving scale. Over the last several years, revenue has moved from the mid-hundreds of millions of dollars to well above $1 billion, while operating profit and net income have expanded faster than sales. That suggests pricing, mix, and cost discipline have all contributed to stronger profitability, not just volume growth.
The financial flow highlights an encouraging trend: sales have risen steadily since 2021, while gross profit and operating income have grown even faster in the most recent periods. Research and development spending has also increased, but not so aggressively that it has prevented margin expansion. This points to a business that is scaling efficiently rather than simply growing for growth’s sake.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Industrial Machinery | |
| Market Cap ⓘ | $7.58B | |
| Beta ⓘ | 0.39 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 28.37 | 22.29 |
| P/B Ratio ⓘ | 18.84 | 1.98 |
| FCF Yield ⓘ | 5.92% | 6.26% |
| Dividend Yield ⓘ | 2.39% | 1.92% |
| EBIT / EV ⓘ | 6.78% | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 21.30% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 13.73% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 12.01% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -0.80% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 12.45% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 37.39% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 54.20% | 10.75% |
| ROA (Latest) ⓘ | 33.82% | 5.41% |
| ROIC (5Y Median) ⓘ | 23.99% | 9.37% |
| ROA (5Y Median) ⓘ | 14.73% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 0.52 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.03 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.46 | 1.39 |
| Net Debt / Assets ⓘ | 21.57% | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | 24.63% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 23.26% | 10.30% |
| Debt to Equity (Latest) ⓘ | 134.54% | 64.82% |
| Profit Margin (Latest) ⓘ | 19.18% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $448.61M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +237.76% | +67.77% |
| 12M Return (excl. last month) ⓘ | +1.35% | +12.05% |
| 6M Return ⓘ | -21.86% | 0.00% |
| Price vs. 200-Day MA ⓘ | -14.43% | +0.67% |
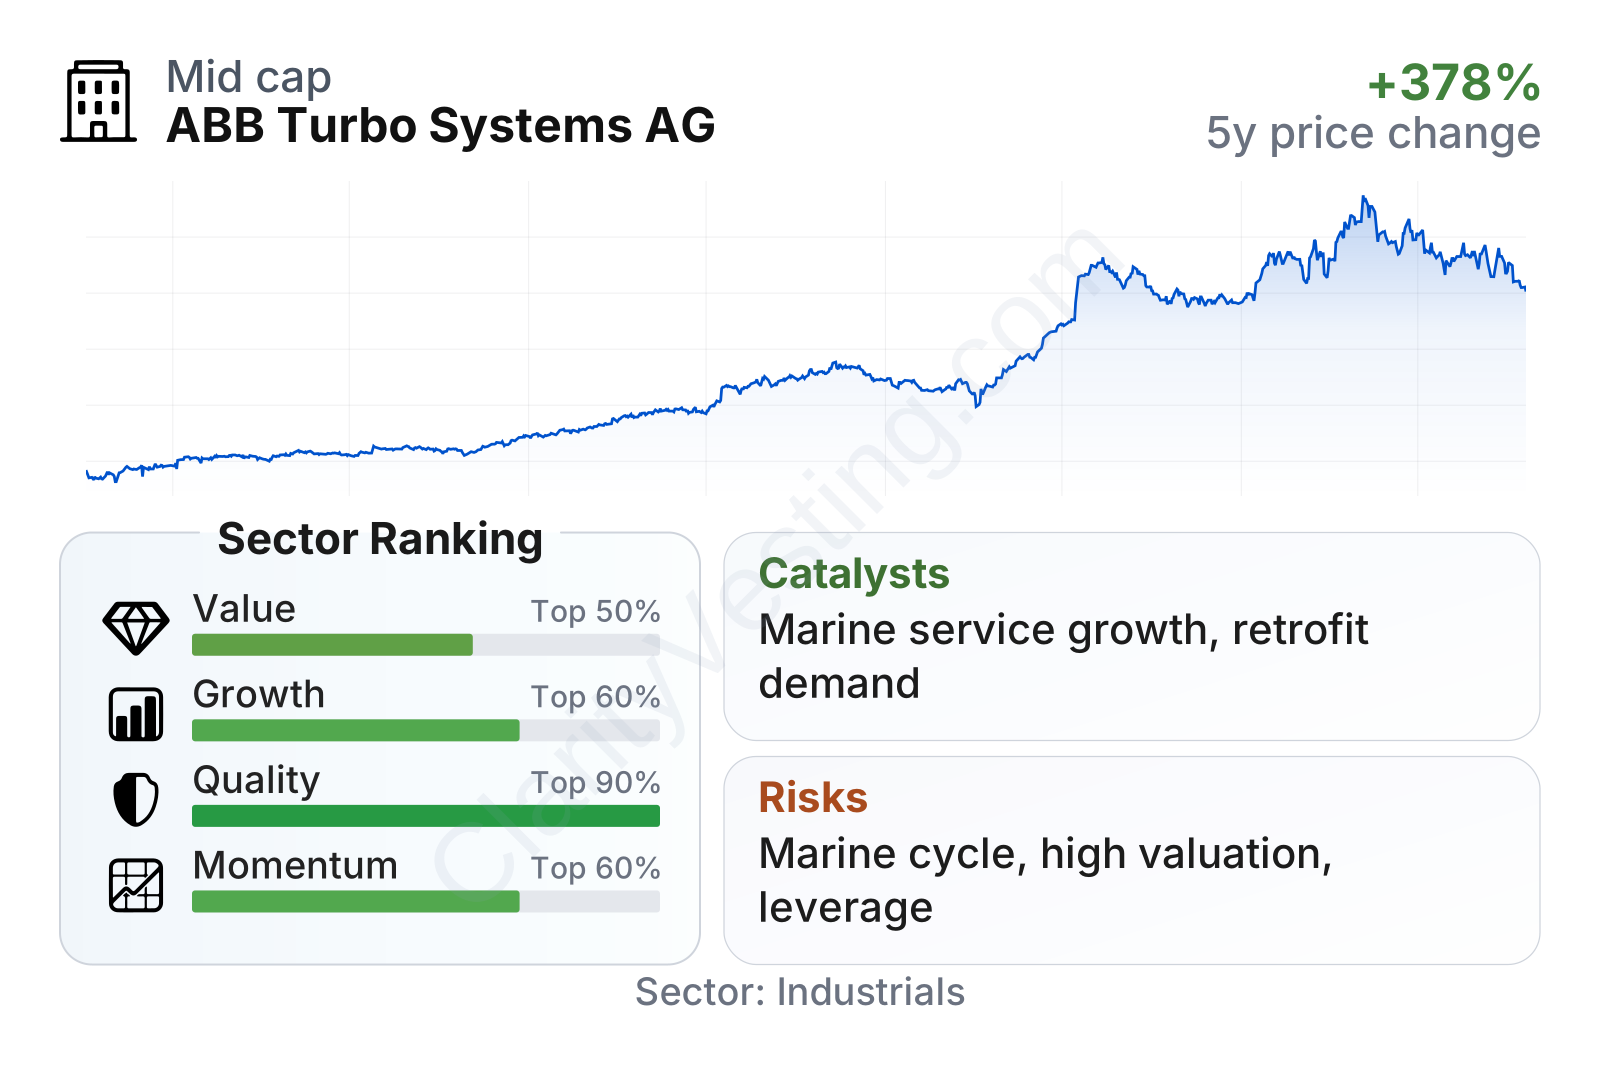
The broad picture is that Accelleron combines unusually high profitability with above-average growth for its industry, while its valuation already reflects part of that strength. Revenue growth over the last year and over a five-year view has been stronger than the sector median, and free cash flow generation remains solid. Quality stands out the most: operating margins, returns on capital, and returns on assets are all well ahead of typical industrial peers. At the same time, the shares trade on a higher earnings multiple than the sector median, and the price-to-book ratio is exceptionally elevated, which often happens when a business produces strong returns with a relatively light equity base.
The share price trend has also been powerful over the last three years, even though recent momentum has cooled somewhat compared with the sector. That usually means the market has already recognized the company’s strengths, so future returns are likely to depend more on continued execution than on simple rerating.
Growth
Accelleron operates in a niche that benefits from several durable industry trends. Shipping and power generation customers are under pressure to cut fuel consumption, reduce emissions, improve uptime, and extend the life of existing assets. Turbocharging and related optimization technologies directly address those needs. This is not a speculative market dependent on a single breakthrough; it is a practical efficiency market with clear economic value for customers.
The strategy also makes sense for long-term growth because it is built around a large installed base and aftermarket depth. Service revenue tends to be steadier than equipment sales, often carrying higher margins and better visibility. As more equipment enters the field, the future service opportunity expands. This creates a compounding effect that can support growth even when new equipment orders are uneven.
Another favorable element is the company’s focus on decarbonization-enabling technologies for marine and energy customers. The shift toward lower-emission fuels, engine optimization, and digital performance monitoring can create additional retrofit demand. In industries where replacing entire fleets is costly and slow, efficiency upgrades on existing assets can be one of the most realistic paths forward.
Recent company communications have also emphasized strong demand in marine service, continued operational progress, and a healthy pipeline tied to efficiency and emissions solutions. For a company with already high margins, incremental growth in premium service and digital offerings can have an outsized effect on earnings.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


