Stock Analysis · Anglo American plc (AAUKF)
Overview
Anglo American plc is a global mining company that produces and sells raw materials used in construction, steelmaking, manufacturing, fertilizers, and the energy transition. Its portfolio is concentrated in copper, iron ore, and crop nutrients, with additional exposure to diamonds, platinum group metals, steelmaking coal, nickel, and manganese through various operations and partnerships. The group has been reshaping itself in recent years by focusing more heavily on copper and iron ore while reducing exposure to businesses seen as less central to its future direction.
Revenue comes primarily from selling mined commodities into global industrial supply chains. Based on the company’s recent portfolio structure and segment disclosures, the business is centered on the following major sources:
- Copper: approximately 30% to 35% of revenue. This includes copper concentrate and cathode from operations in Chile and Peru. Copper is increasingly important because of demand from electric grids, electric vehicles, renewable power equipment, and data infrastructure.
- Iron ore: approximately 25% to 30% of revenue. This mainly comes from Kumba in South Africa and the Minas-Rio operation in Brazil. Iron ore is used primarily in steel production.
- Platinum group metals: approximately 15% to 20% of revenue. This segment includes platinum, palladium, rhodium, and related by-products used in automotive catalysts, jewelry, chemicals, and industrial applications.
- Diamonds: approximately 10% to 15% of revenue. This is largely through De Beers, which sells rough diamonds and also has downstream branding activities.
- Steelmaking coal: approximately 5% to 10% of revenue. This product is used in blast furnace steelmaking.
- Other businesses: generally less than 10% combined. This includes manganese, nickel, and crop nutrients development, especially the Woodsmith polyhalite project in the United Kingdom.
The broad picture is that Anglo American is no longer just a diversified miner in the traditional sense. It is becoming a more focused producer of materials tied to electrification and industrial infrastructure, while still carrying meaningful exposure to cyclical and more volatile commodity markets.
The long-term revenue path has been uneven. Sales and operating profit were much stronger in 2021 and 2022, then dropped sharply as commodity prices weakened and several operations faced pressure. More recently, revenue appears to have stabilized somewhat, but earnings remain far below the earlier peak, showing how heavily results depend on the commodity cycle as well as on execution at major mines.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 22, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $56.56B | |
| Beta ⓘ | 0.95 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.92 |
| P/B Ratio ⓘ | 5.18 | 1.66 |
| FCF Yield ⓘ | N/A | 5.83% |
| Dividend Yield ⓘ | 0.74% | 2.07% |
| EBIT / EV ⓘ | 16.16% | 6.38% |
| PEG ⓘ | 3.02 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.90% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -13.54% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -4.61% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | -10.30% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -32.26% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -33.53% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -38.68% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | N/A | 4.92% |
| ROIC (5Y Median) ⓘ | 8.80% | 7.91% |
| ROA (5Y Median) ⓘ | 0.42% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 0.68 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.25 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.93 |
| Net Debt / Assets ⓘ | 12.81% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.38 |
| Operating Margin (Latest) ⓘ | N/A | 13.24% |
| Operating Margin (5Y Median) ⓘ | 14.96% | 11.82% |
| Debt to Equity (Latest) ⓘ | N/A | 40.30% |
| Profit Margin (Latest) ⓘ | -13.94% | 6.38% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +94.24% | +73.47% |
| 12M Return (excl. last month) ⓘ | +61.37% | +27.59% |
| 6M Return ⓘ | +6.53% | -4.02% |
| Price vs. 200-Day MA ⓘ | +14.22% | -0.65% |
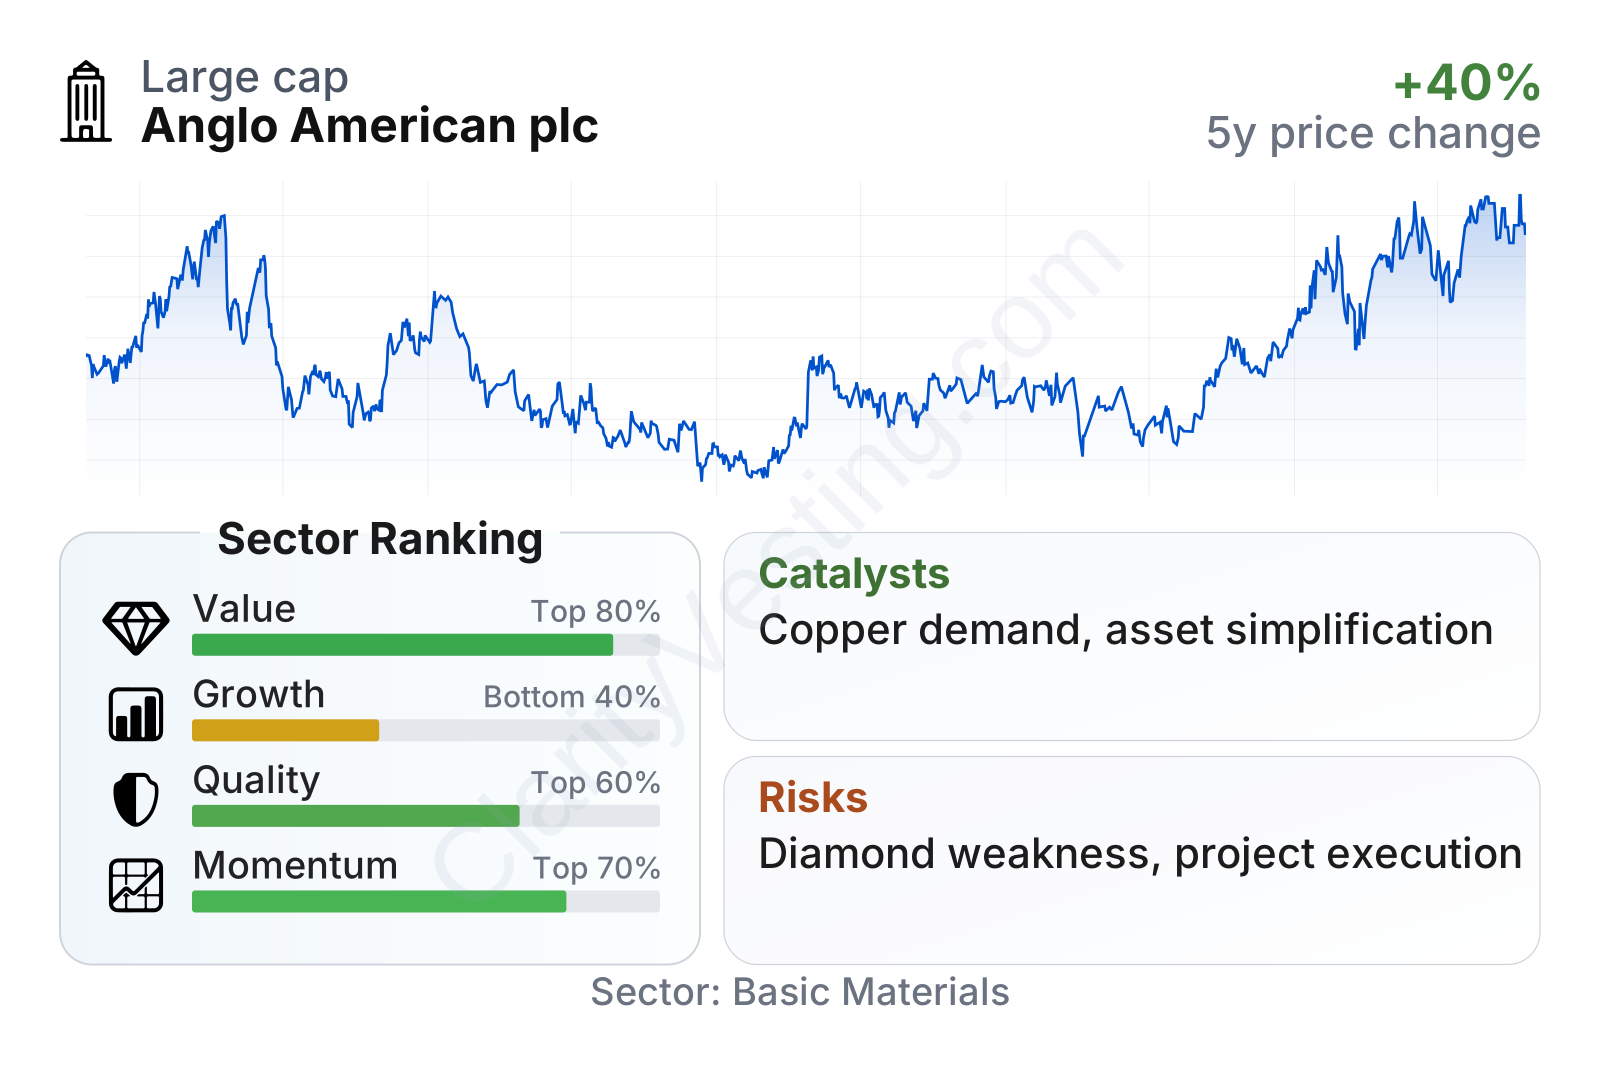
Anglo American is a very large mining group, and its share price has recovered strongly over the past year after a volatile multiyear stretch. The stock’s recent momentum stands above much of the sector, with gains over one year and three years beating the industry median. That strength suggests the market has become more constructive on the company’s restructuring and asset base.
On valuation, the picture is mixed. Some operating-based measures look relatively attractive compared with the sector, especially earnings before interest relative to enterprise value, which points to stronger operating earning power than the average peer. At the same time, the price-to-book ratio is high for a mining company, which usually means the market is assigning a premium to certain assets or expecting an improvement in profitability.
Quality measures are generally solid but not spotless. Balance-sheet leverage looks moderate, with net debt running below sector norms on an earnings basis, which gives the group more flexibility than many miners. However, recent profitability has been distorted by losses and impairments, and trailing net margin is negative. Growth metrics are the weakest area: five-year trends in revenue per share, free cash flow, margins, and dividends all lag the sector, reflecting the drop from peak-cycle conditions and operational setbacks.
Growth
Anglo American operates in several sectors that matter for long-term global industrial demand, but not all of them are moving in the same direction. Copper is the clearest structural growth area in the portfolio. Electrification requires far more copper than traditional energy systems, and demand is supported by grid upgrades, renewable installations, electric vehicles, industrial automation, and data centers. This gives Anglo American exposure to one of the most attractive large-scale mining markets.
The company’s strategy also broadly fits that theme. Management has been simplifying the portfolio, placing more emphasis on copper, premium iron ore, and the Woodsmith crop nutrients project. That direction makes strategic sense because it shifts the company toward products with either stronger long-term demand fundamentals or distinctive asset quality. In copper, Anglo American has a pipeline that includes major South American operations and longer-duration optionality if execution improves. In iron ore, Minas-Rio and Kumba remain important cash-generating assets when markets are supportive.
A notable catalyst has been the company’s restructuring push following takeover interest and market pressure to unlock value. The company has outlined plans to streamline the business and separate or reduce exposure to non-core assets, including diamonds, platinum group metals, and steelmaking coal. If completed on acceptable terms, that could leave Anglo American more focused and easier for the market to value.
Another growth driver is Woodsmith, a large fertilizer-related project centered on polyhalite. This is not yet a major revenue source, and it still requires time and capital, but it offers long-duration optionality in agricultural inputs if developed successfully. Unlike copper, this is more of a future platform than a near-term earnings engine.
Recent company updates have also pointed to operating improvement efforts across the portfolio, including productivity, cost control, and mine-plan optimization. For a miner, these initiatives can be highly significant because even modest changes in volumes, grades, or unit costs can produce large swings in earnings and cash flow when commodity prices cooperate.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


