Stock Analysis · AAON Inc (AAON)
Overview
AAON Inc designs and manufactures heating, ventilation, and air conditioning equipment, usually called HVAC equipment. Its products are mainly used in commercial buildings such as schools, offices, data centers, health care facilities, manufacturing sites, and other non-residential properties. The company focuses on more specialized and higher-performance systems rather than the most commoditized parts of the HVAC market, with an emphasis on energy efficiency, indoor air quality, and custom configurations.
AAON operates through three main brands and platforms: AAON, BASX, and Gordon. AAON is the core rooftop and commercial HVAC business, BASX is focused on custom air-handling systems, cleanroom systems, and data center cooling, and Gordon serves the architectural and specialty air distribution market. This mix gives the company exposure to both traditional commercial HVAC replacement demand and faster-growing niches such as hyperscale and colocation data centers.
Based on recent annual filings, revenue is primarily generated from equipment sales in North America, with the United States representing the vast majority of business. Exact category percentages can shift from year to year, but the revenue mix is broadly concentrated as follows:
- AAON Oklahoma segment: approximately 65% to 75% of revenue. This includes semi-custom rooftop units, chillers, air-source heat pumps, and related commercial HVAC equipment.
- AAON Coil Products segment: approximately 10% to 15% of revenue. This business supplies condenser and evaporator coils used in HVAC systems, both internally and to outside customers.
- BASX segment: approximately 15% to 25% of revenue. This includes custom air handlers, cleanroom systems, and cooling solutions for data centers and other mission-critical environments.
Over the last several years, AAON’s business model has shifted toward more customized and technically demanding equipment. That matters because specialized systems can support better pricing and stronger margins than standard commodity HVAC products, although they can also create lumpier order patterns and higher working-capital needs.
The long-term financial picture shows a business that expanded revenue sharply from 2021 through 2025, but with more pressure on profitability after a 2023 peak. Sales kept rising, yet costs and operating expenses absorbed a larger share of revenue in 2024 and 2025, which helps explain why earnings did not keep pace with top-line growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Building Products & Equipment | |
| Market Cap ⓘ | $6.09B | |
| Beta ⓘ | 1.41 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 38.91 | 22.29 |
| P/B Ratio ⓘ | 6.23 | 1.98 |
| FCF Yield ⓘ | -1.95% | 6.26% |
| Dividend Yield ⓘ | 0.53% | 1.92% |
| EBIT / EV ⓘ | 2.95% | 4.83% |
| PEG ⓘ | 0.95 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 101.20% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 27.18% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -5.91% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 16.81% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -2.81% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 12.21% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 13.31% | 10.75% |
| ROA (Latest) ⓘ | 9.38% | 5.41% |
| ROIC (5Y Median) ⓘ | 18.01% | 9.37% |
| ROA (5Y Median) ⓘ | 13.71% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 2.17 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.57 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 1.55 | 1.39 |
| Net Debt / Assets ⓘ | 24.89% | 19.27% |
| EBITDA / Interest ⓘ | 13.49 | 9.58 |
| Operating Margin (Latest) ⓘ | 11.06% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 14.31% | 10.30% |
| Debt to Equity (Latest) ⓘ | 45.91% | 64.82% |
| Profit Margin (Latest) ⓘ | 8.24% | 6.67% |
| Free Cash Flow (Latest) ⓘ | -$118.79M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +43.29% | +67.77% |
| 12M Return (excl. last month) ⓘ | -16.20% | +12.05% |
| 6M Return ⓘ | -21.27% | 0.00% |
| Price vs. 200-Day MA ⓘ | -23.20% | +0.67% |
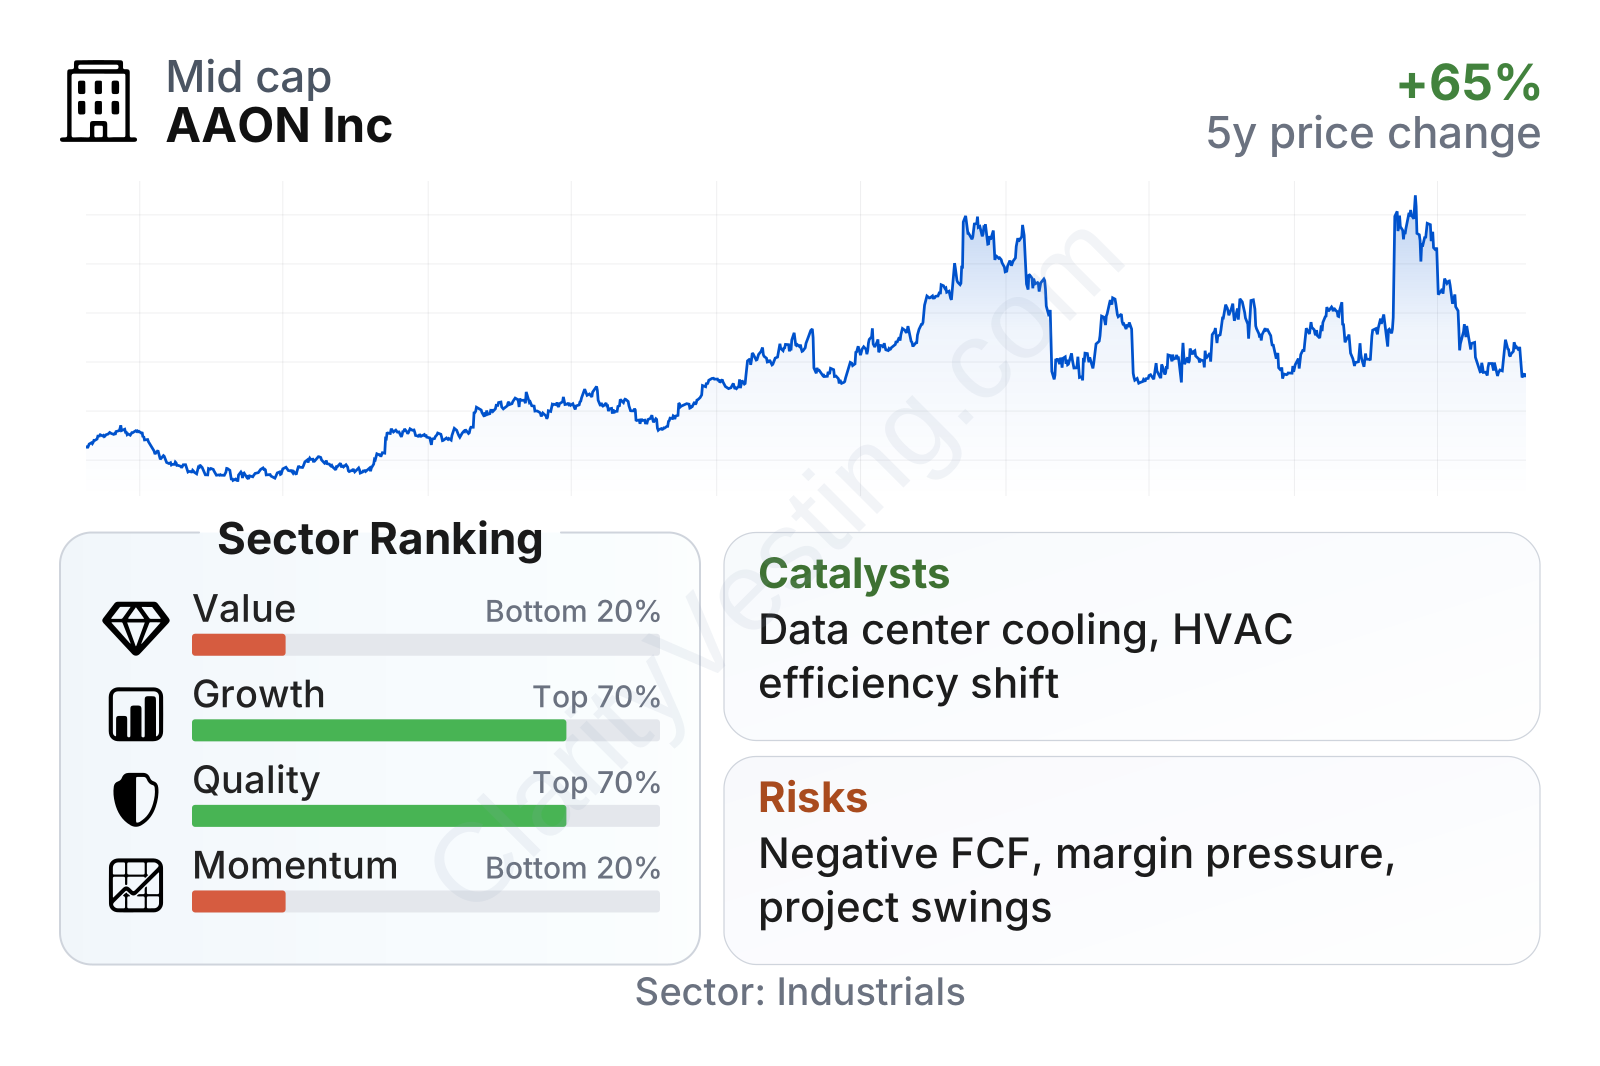
AAON is now a mid-cap industrial company with above-average share price volatility. The most striking takeaway from the latest metrics is the contrast between strong business quality and a demanding valuation. Profitability remains better than the sector median on several measures, and long-term revenue growth has been strong, but the stock trades at materially higher earnings and book multiples than most peers. Recent cash generation has also been weaker than the income statement suggests, which is an important point for long-term analysis.
Growth
AAON operates in a part of the market with favorable long-term drivers. Commercial buildings increasingly need better energy efficiency, tighter ventilation standards, electrification-ready systems, and more advanced cooling. Replacement demand is also important because HVAC equipment wears out over time and building owners often upgrade to improve operating costs. On top of that, data center construction has become a major growth engine for specialized cooling suppliers, and that is especially relevant because BASX gives AAON direct exposure to that opportunity.
The company’s strategy is coherent. Rather than competing mainly on scale in basic HVAC boxes, it has leaned into semi-custom and custom systems where engineering capability, reliability, and application-specific design matter more. That positioning can be attractive in markets such as health care, cleanrooms, manufacturing, and data centers, where performance requirements are stricter and price is not the only deciding factor.
Revenue growth has been highly uneven but clearly strong over the full cycle. AAON posted exceptional gains in 2022 and 2023, then growth cooled, and more recently accelerated again. The latest year-over-year reading is far above the sector median, which suggests either a major project ramp, easier comparison period, or both. For long-term readers, the main point is that the company still has meaningful demand momentum, even if quarter-to-quarter patterns can be volatile.
Free cash flow is the main caution inside the growth case. It moved from solidly positive to negative, which usually reflects some combination of inventory build, receivables growth, capacity expansion, or project timing. For a manufacturer pursuing larger and more complex opportunities, that does not automatically signal a structural problem, but it does mean growth is currently consuming cash rather than producing it.
A notable catalyst is the buildout of data center cooling infrastructure. BASX has become increasingly relevant as artificial intelligence and cloud computing drive demand for high-performance thermal management. AAON has also invested in manufacturing capacity in recent years, which can support larger order volumes if demand remains strong. The broader trend toward stricter building standards and more efficient HVAC systems also supports the company’s product roadmap.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


