Stock Analysis · Clear Secure Inc (YOU)
Overview
Clear Secure is a digital identity company best known for the CLEAR Plus subscription used in U.S. airports. The service lets members confirm their identity quickly and move to the front of the document-check step before security screening. Over time, the company has expanded beyond airport lanes into identity verification for travel, healthcare, financial services, and other use cases where confirming a person’s identity matters.
The business is still heavily centered on consumer travel. Based on recent company reporting, revenue is primarily generated from subscriptions and related services, with partnerships also playing an important role. The mix can shift from quarter to quarter, but the broad structure is fairly clear.
- CLEAR Plus consumer memberships: approximately 75% to 85% of revenue. This is the core airport subscription product, typically sold directly to travelers and also through partner channels.
- Partner and third-party arrangements: approximately 10% to 20% of revenue. This includes commercial relationships tied to member acquisition, distribution, promotions, and service integrations, especially with airlines, credit card issuers, and travel ecosystem partners.
- Other identity and platform services: generally a small but growing share. This includes enterprise and digital identity offerings outside the main airport membership product.
What stands out in the economics is how much of each dollar of revenue remains after direct service costs. Over the last several years, revenue has grown sharply while operating expenses have become more efficient relative to sales, helping the company move from losses into solid profitability and cash generation.
The business mix shows a company that still depends mainly on one flagship service, but with improving scale. Revenue has expanded several times since the early public-company period, and a much larger portion now reaches operating income and free cash flow than it did a few years ago.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Software - Application | |
| Market Cap ⓘ | $5.80B | |
| Beta ⓘ | 1.02 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 29.07 | 29.51 |
| FCF Yield ⓘ | 8.76% | 4.25% |
| EBIT / EV ⓘ | 7.31% | 2.85% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 26.60% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | 29.63% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | 110.53% | -11.88% |
| Margin Growth (5Y Trend) ⓘ | 68.00% | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | 70.36% | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 115.38% | 9.44% |
| ROIC (5Y Median) ⓘ | 19.03% | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | -0.07 | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.82 | 0.44 |
| Operating Margin (Latest) ⓘ | 26.29% | 9.58% |
| Operating Margin (5Y Median) ⓘ | 8.25% | 8.25% |
| Debt to Equity (Latest) ⓘ | 53.22% | 33.33% |
| Profit Margin (Latest) ⓘ | 14.78% | 7.14% |
| Free Cash Flow (Latest) ⓘ | $508.39M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +118.12% | +45.48% |
| 12M Return (excl. last month) ⓘ | +41.09% | +23.48% |
| 6M Return ⓘ | -5.16% | +20.93% |
| Price vs. 200-Day MA ⓘ | -8.53% | +7.43% |
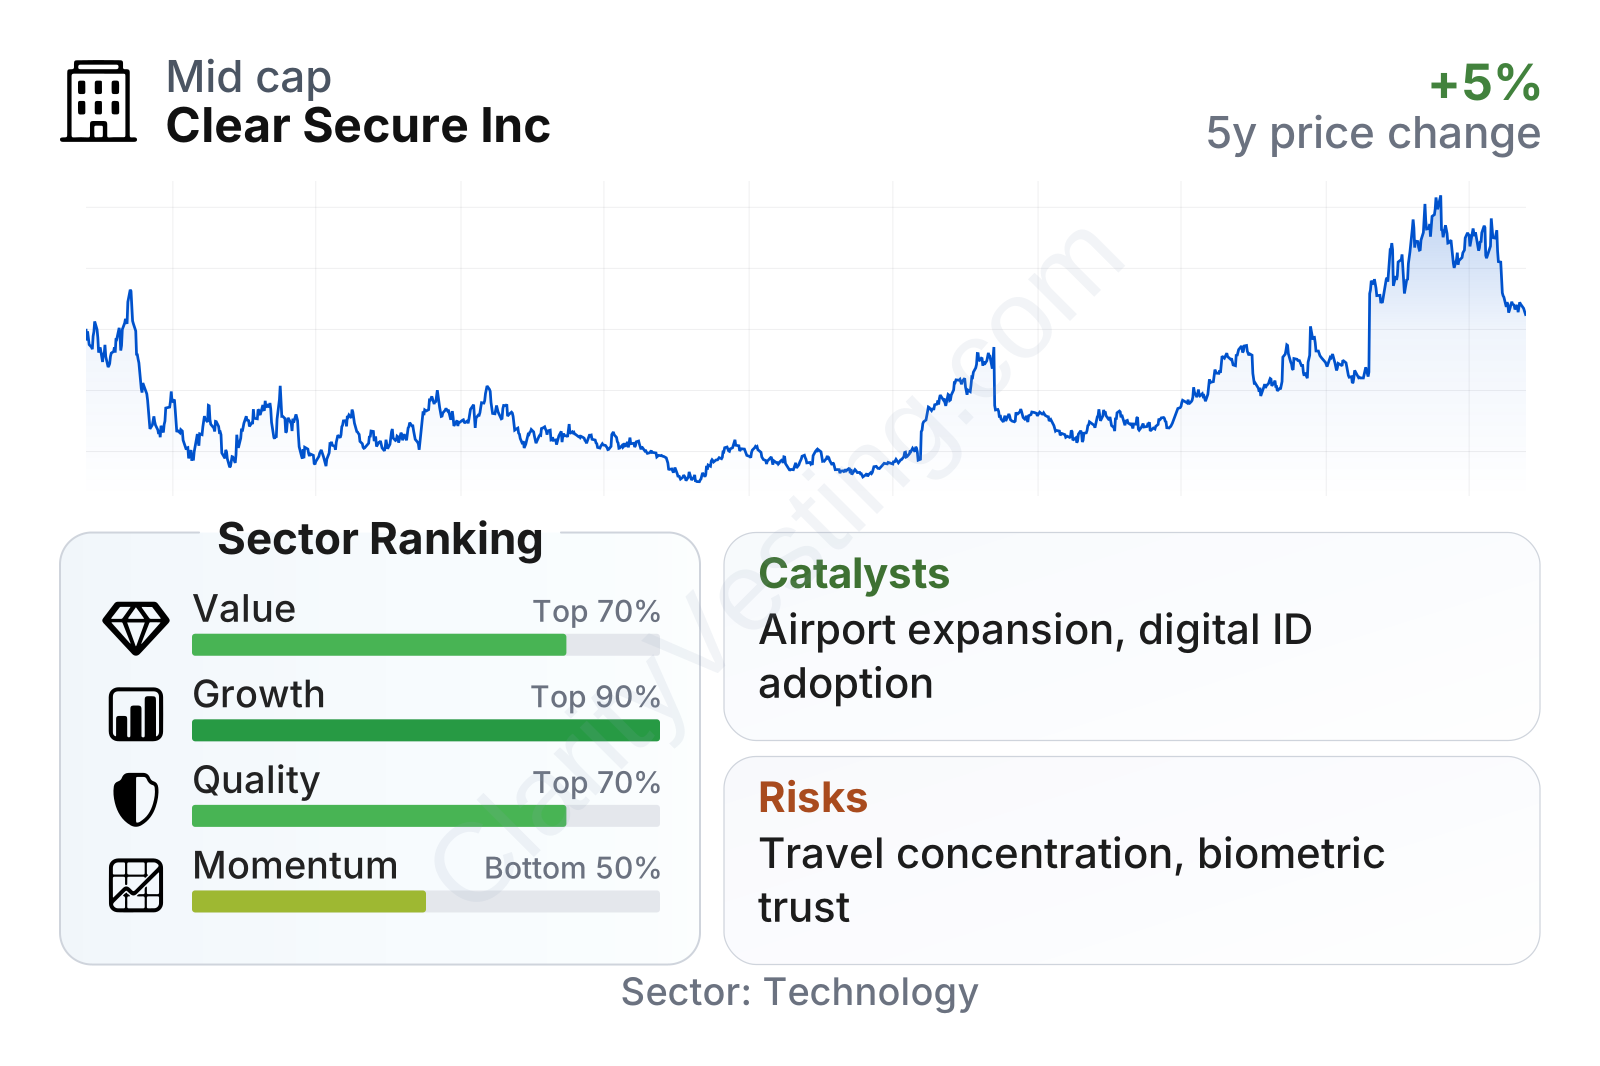
Clear Secure sits in the mid-cap range, with share-price volatility close to the broader market rather than extreme software-style swings. The most notable feature in the latest profile is balance: growth ranks very high against the sector, profitability is clearly above typical software peers, and cash generation is particularly strong. Value measures are not deeply discounted, but they are supported by better free cash flow yield and stronger operating earnings relative to enterprise value than the sector median. Momentum is more mixed, reflecting a strong multi-year rise but a softer shorter-term pattern.
Growth
Clear Secure operates where several long-term trends overlap: rising air travel volumes, increasing demand for faster passenger processing, and broader use of digital identity tools. That gives the company exposure to a sector with room to expand, especially if identity verification becomes more common outside airport checkpoints.
The current strategy is logical. CLEAR Plus remains the scale engine because it is the brand most consumers recognize and the product with the deepest installed footprint. From there, management has been trying to use that installed base, trusted identity network, and partner relationships to widen the platform into adjacent services. That approach makes sense because the company does not need to create awareness from zero; it can build around an identity product already used by millions of members.
Growth has naturally slowed from the very high post-pandemic rebound period, but it remains strong. Recent year-over-year revenue growth is still running in the mid-20% range, which is well ahead of the sector median. Just as important, the longer trend shows that Clear Secure has maintained expansion even after the initial travel recovery faded, suggesting the business is no longer driven only by reopening effects.
Cash generation strengthens the growth case. Free cash flow has climbed rapidly over the last few years and recently moved above the half-billion-dollar area on a trailing basis. That matters because it gives the company flexibility to invest in technology, expand distribution, pursue new identity use cases, and return capital without depending heavily on outside financing.
A major catalyst is the effort to deepen airport penetration while also broadening into identity-linked products beyond the checkpoint. The company has continued adding locations, partner programs, and product features designed to improve conversion and retention. Another meaningful opportunity is the intersection between CLEAR’s identity platform and the push for more secure, reusable digital credentials across travel and other industries. If that broader identity layer gains traction, the company’s addressable market could become much larger than airport memberships alone.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


