Stock Analysis · NCR Voyix Corporation (VYX)
Overview
NCR Voyix Corporation is a commerce technology company focused on software, services, and hardware used by retailers and restaurants. Its products help stores and restaurant operators run point-of-sale systems, self-checkout, payment acceptance, order management, inventory workflows, and related back-office operations. The company became more focused after separating its ATM-oriented business, leaving NCR Voyix centered on digital commerce tools for merchants rather than banking infrastructure.
Its revenue mix is mainly built around retail customers, followed by restaurants, with additional contribution from payments, software subscriptions, professional services, and hardware support. Based on recent company reporting, the business is broadly organized around these sources:
- Retail solutions: approximately 55% to 65% of revenue. This includes point-of-sale software, self-checkout, store systems, implementation, maintenance, and related services for grocers, mass merchants, and specialty retailers.
- Restaurant solutions: approximately 25% to 35% of revenue. This covers restaurant point-of-sale platforms, kitchen and order software, digital ordering, drive-thru technology, and field services.
- Payments and transaction-related services: a smaller but strategically important share, generally embedded across both main segments through payment processing, recurring platform fees, and software-linked transaction activity.
- Professional services, maintenance, and hardware lifecycle support: an additional layer of revenue attached to installations, upgrades, managed services, and customer support contracts.
The business model is in transition. Management has been trying to reduce dependence on lower-margin hardware and emphasize recurring software and services. That shift matters because software revenue is typically more predictable and usually carries better economics than selling equipment alone. Even so, NCR Voyix still has meaningful exposure to physical retail and restaurant deployments, so it remains a hybrid of software, services, and hardware rather than a pure software company.
The longer-term picture is clear: NCR Voyix wants to become a more focused enterprise software and commerce platform provider for large retailers and restaurant chains. The challenge is that this transformation has been happening while total revenue has been shrinking and profitability has been uneven.
The operating profile shows a business that has cut costs and interest expense meaningfully over the past few years, but revenue has also moved lower. Gross profit has narrowed from earlier levels, while operating income only recently turned slightly positive after several weak years. That points to a company still in the middle of a restructuring rather than one already operating at full strength.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Information Technology Services | |
| Market Cap ⓘ | $1.18B | |
| Beta ⓘ | 1.50 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 30.54 | 29.51 |
| FCF Yield ⓘ | -9.06% | 4.25% |
| EBIT / EV ⓘ | 0.50% | 2.85% |
| PEG ⓘ | 2.68 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -20.80% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | -7.98% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | -51.47% | -11.88% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.69% | 9.44% |
| ROIC (5Y Median) ⓘ | -2.19% | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | 72.00 | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.44 |
| Operating Margin (Latest) ⓘ | 0.47% | 9.58% |
| Operating Margin (5Y Median) ⓘ | -1.01% | 8.25% |
| Debt to Equity (Latest) ⓘ | 97.18% | 33.33% |
| Profit Margin (Latest) ⓘ | 2.99% | 7.14% |
| Free Cash Flow (Latest) ⓘ | -$107.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -49.43% | +45.48% |
| 12M Return (excl. last month) ⓘ | -34.09% | +23.48% |
| 6M Return ⓘ | +27.42% | +20.93% |
| Price vs. 200-Day MA ⓘ | +2.90% | +7.43% |
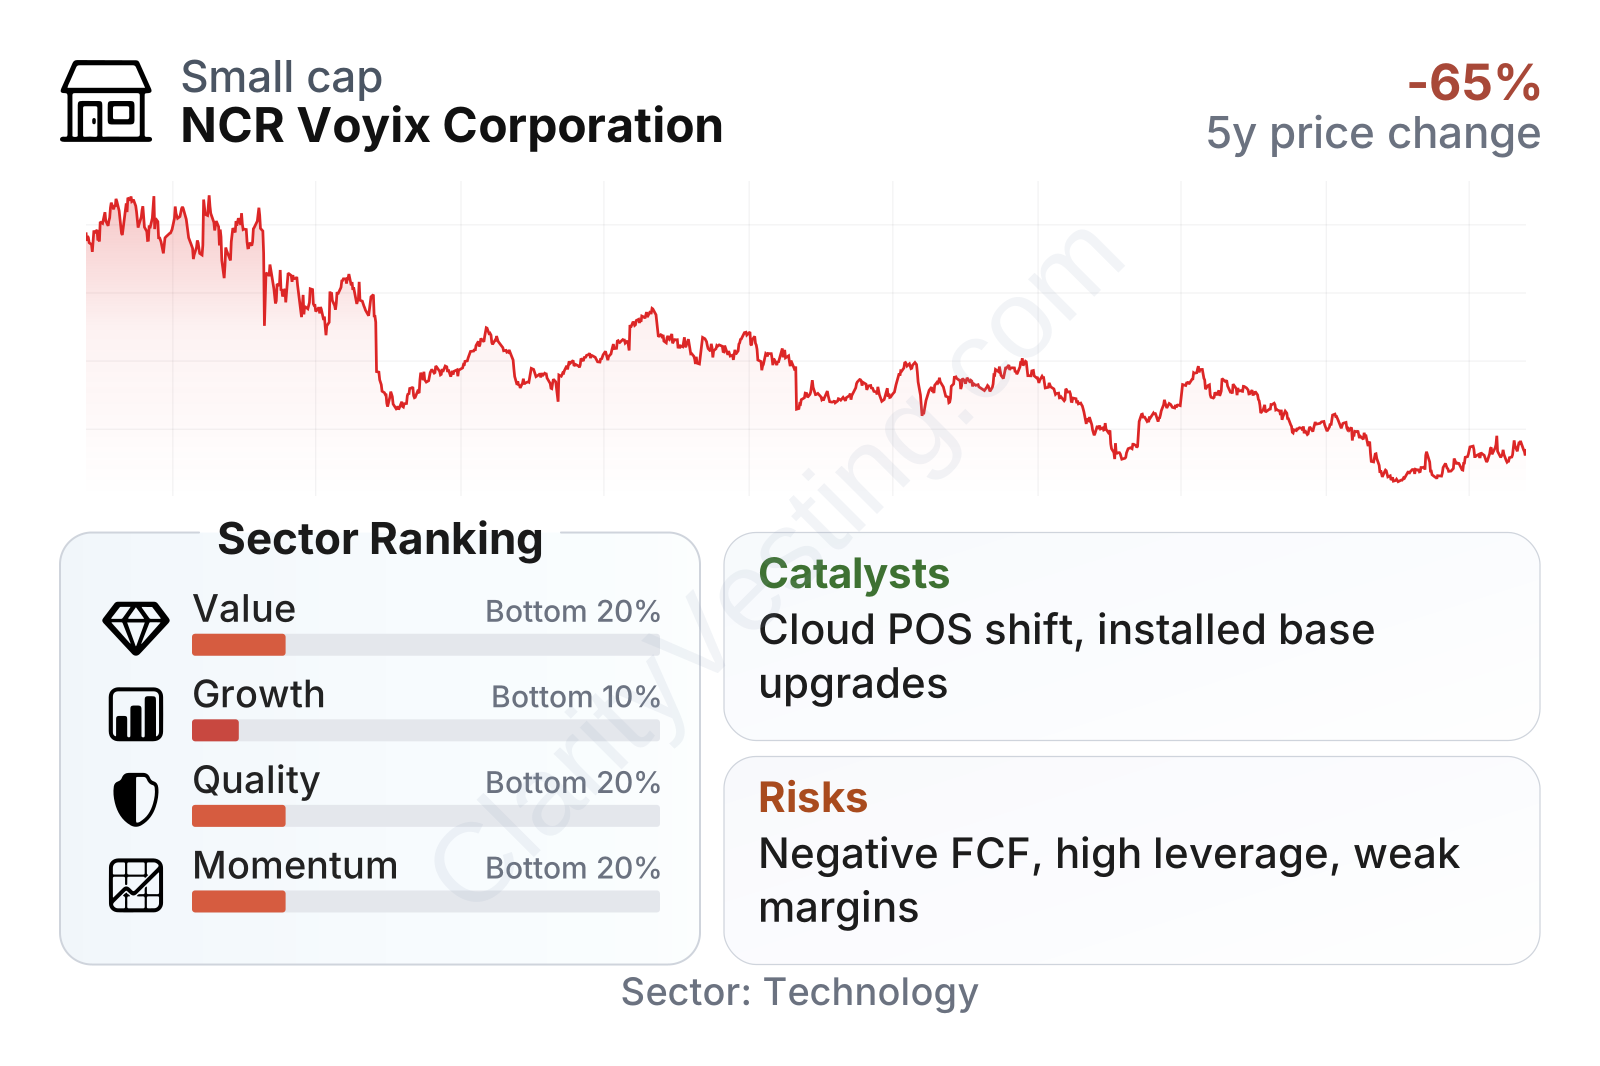
NCR Voyix is now a relatively small public technology company, and its share price has been under sustained pressure for several years. In the broader technology sector, its latest profile ranks weakly on value, growth, quality, and momentum. The most notable signals are negative free cash flow, very high net debt relative to EBIT, and margins that remain well below sector norms. The stock’s volatility is also above average, which fits a business still working through a turnaround.
Growth
NCR Voyix operates in markets with favorable long-term demand drivers. Retailers and restaurant chains continue to invest in cloud-based point-of-sale systems, self-service technology, digital ordering, payment integration, and data-driven store operations. These are real growth areas because merchants want fewer disconnected systems and more automation at the store level. In that sense, the company is participating in an attractive part of enterprise technology.
The strategic logic also makes sense on paper. NCR Voyix already has a large installed base in stores and restaurants, which can create upgrade opportunities into newer software, subscriptions, and payment-linked offerings. If the company can move customers from legacy systems toward more recurring, platform-based contracts, that could improve revenue quality over time. This installed-base advantage is one of the most important pieces of the investment case.
The near-term growth record, however, remains weak. Revenue growth has been negative in most recent periods, with the latest year-over-year result down by a little more than 20%. Some of that reflects portfolio changes and restructuring effects, but the pattern still shows that NCR Voyix has not yet translated its strategic repositioning into sustained top-line expansion.
Cash generation has also deteriorated sharply. Free cash flow was strongly positive a few years ago and has since turned materially negative. For a company trying to reposition itself, this matters a lot: software transitions often require patience, but negative cash flow reduces flexibility and raises the stakes on execution. A durable recovery would likely require stabilization in revenue, tighter working-capital management, and better operating margins.
One important catalyst is the company’s continued simplification after the separation of its ATM business. A cleaner structure can make financial performance easier to evaluate and can help management focus capital and product development on retail and restaurant software. Another potential opportunity is continued demand from large merchants modernizing checkout, self-service, and unified commerce systems. If NCR Voyix can convert more of those customer relationships into recurring software and services, the growth profile could look much stronger than it does today.
Recent company updates have also emphasized product launches, cloud migrations, and efforts to deepen partnerships across restaurant and retail ecosystems. Those initiatives support the strategic direction, but the central question is still execution: the end markets are promising, yet the company needs that demand to show up more clearly in reported revenue and cash flow.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


