Stock Analysis · Unusual Machines Inc (UMAC)
Overview
Unusual Machines Inc is a small technology company focused on the drone ecosystem. Its activities center on selling drone-related hardware and accessories and building a U.S.-based platform around components used by drone makers, hobbyists, and commercial users. The company has also highlighted a broader ambition to support domestic drone supply chains, which matters because many buyers and policymakers are looking for alternatives to foreign-made components in sensitive applications.
Based on recent company filings, revenue currently comes primarily from product sales rather than software or recurring services. The business is still at an early stage, and its mix can change quickly as acquisitions, new product lines, or supply agreements are added.
- Drone parts, electronics, and related hardware: likely the largest revenue source. This includes components and products sold into the drone market, such as flight-related electronics, accessories, and other hardware sold through the company’s operating businesses.
- Branded consumer drone products and accessories: a smaller but meaningful source tied to direct product sales to enthusiasts and retail-style customers.
- Other revenue: currently limited. Public disclosures do not indicate a large recurring software or subscription stream at this stage.
The key point for long-term analysis is that Unusual Machines is not yet a mature, diversified hardware company. It is a developing drone-focused platform whose future depends on scaling sales fast enough to absorb operating costs and turn its niche positioning into a durable business.
The long-term financial pattern shows a business that has increased revenue materially from a very small base, but expenses have risen even faster. Gross profit has improved with scale, yet selling and administrative costs remain the main reason losses are still substantial.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Computer Hardware | |
| Market Cap ⓘ | $1.15B | |
| Beta ⓘ | 14.73 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 29.51 |
| FCF Yield ⓘ | -5.10% | 4.25% |
| EBIT / EV ⓘ | -2.59% | 2.85% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 687.30% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | 403.27% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | -38.16% | -11.88% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -6.96% | 9.44% |
| ROIC (5Y Median) ⓘ | N/A | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.44 |
| Operating Margin (Latest) ⓘ | -70.08% | 9.58% |
| Operating Margin (5Y Median) ⓘ | -224.59% | 8.25% |
| Debt to Equity (Latest) ⓘ | 0.81% | 33.33% |
| Profit Margin (Latest) ⓘ | -20.29% | 7.14% |
| Free Cash Flow (Latest) ⓘ | -$58.51M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +45.48% |
| 12M Return (excl. last month) ⓘ | +154.76% | +23.48% |
| 6M Return ⓘ | +3.61% | +20.93% |
| Price vs. 200-Day MA ⓘ | +30.18% | +7.43% |
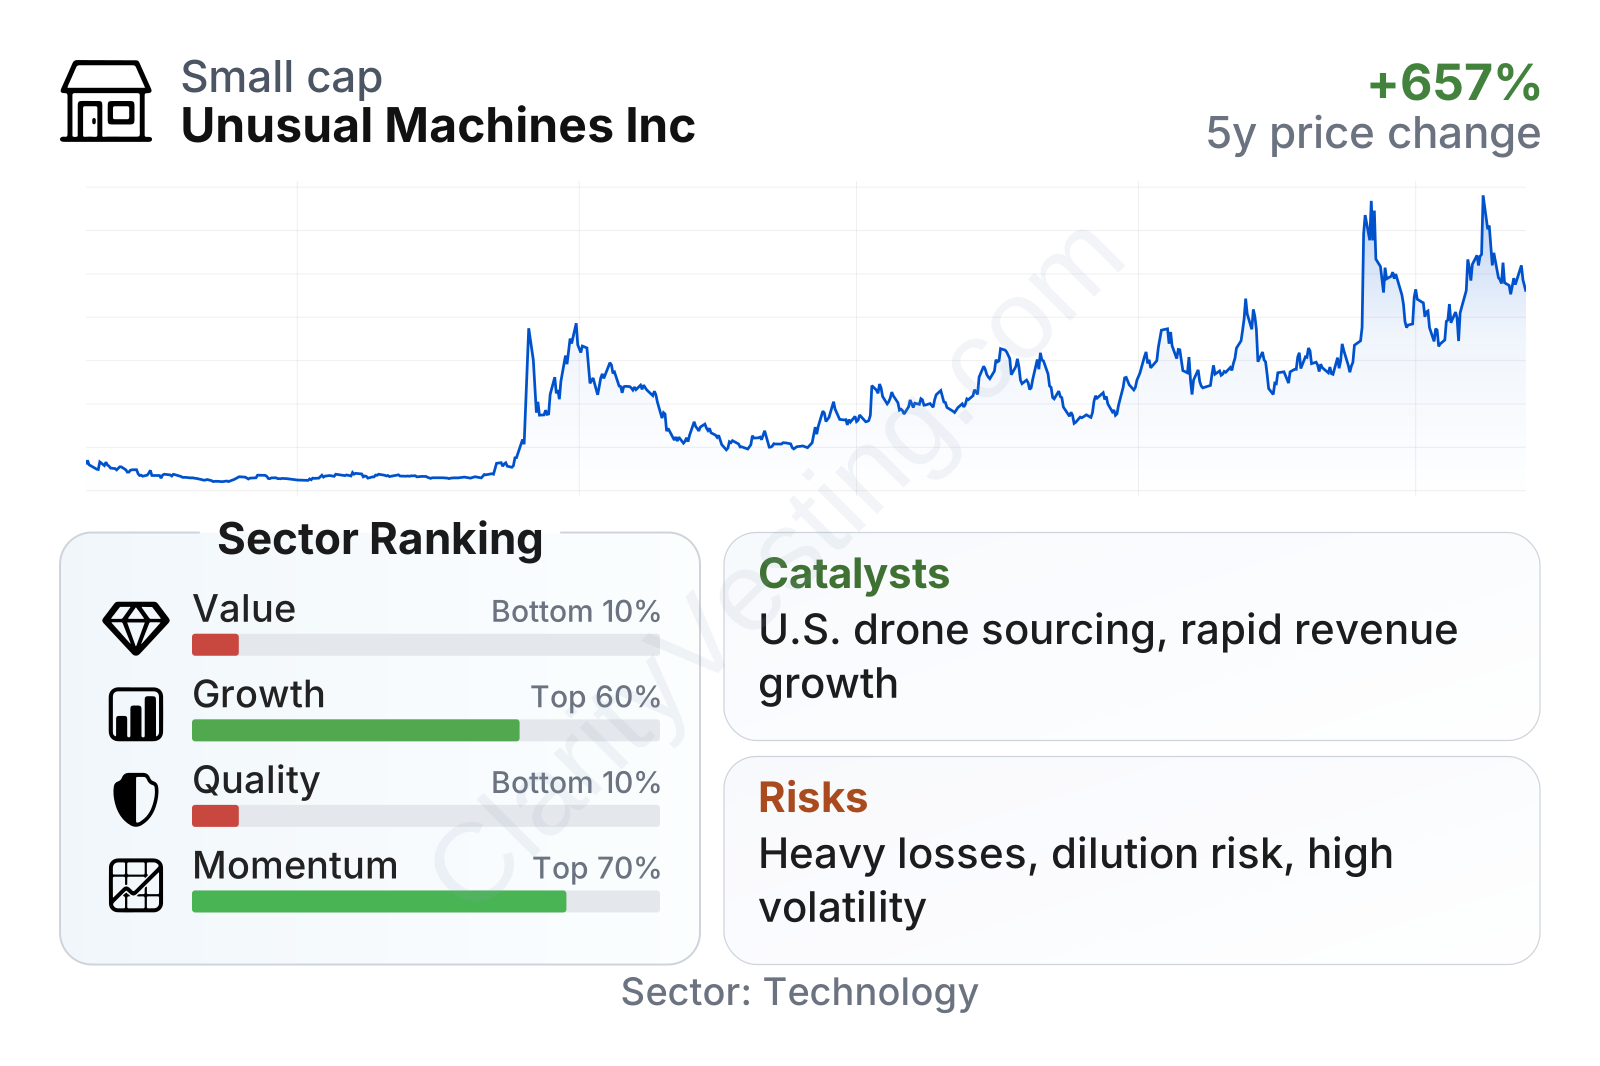
The market is treating Unusual Machines like a high-volatility small-cap growth name rather than a stable hardware manufacturer. Growth metrics stand out, with revenue expansion far above the sector median, and recent share-price momentum has also been unusually strong. At the same time, quality and value measures rank near the bottom of the sector because profitability is still negative and free cash flow remains deeply in the red. The balance sheet is a relative bright spot, with debt levels far below typical technology peers.
Growth
Unusual Machines operates in a market with real long-term potential. Drones are being adopted across recreation, industrial inspection, agriculture, defense-related applications, mapping, and public safety. In parallel, the push for a more domestic supply chain in U.S. drone hardware could create openings for companies positioned as local alternatives. That does not automatically create profits, but it does mean the company is participating in a sector with favorable structural drivers.
The company’s strategy is also understandable. Instead of trying to become a full-scale mass-market drone giant overnight, it appears to be building around components, accessories, and niche hardware positions where smaller companies can sometimes compete more effectively. That approach can make sense because components and specialized products often require less capital than trying to dominate complete drone systems against much larger rivals.
Revenue growth has accelerated sharply, moving from already strong levels to extremely high year-over-year expansion by mid-2026. Because the company is starting from a small base, these growth rates should be viewed with caution, but the direction is still important: sales momentum is clearly improving rather than fading.
Cash generation remains the weak point. Free cash flow has become more negative as the company has expanded, which suggests growth is currently being purchased through higher operating spending, inventory needs, or integration costs rather than self-funded from the business. For a young company, that is not unusual, but over time the path to stronger cash conversion matters more than revenue growth alone.
Recent company updates and filings point to the main opportunity: becoming a recognized U.S.-based supplier in a drone market where sourcing, regulation, and national security concerns are becoming more relevant. If management can translate that positioning into larger commercial relationships, distribution reach, and repeat product demand, the addressable market could expand meaningfully from its current scale.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


