Stock Analysis · ScanSource Inc (SCSC)
Overview
ScanSource Inc is a technology distributor. In simple terms, it sits between equipment makers and the businesses or resellers that ultimately use that equipment. Rather than manufacturing hardware or writing major software platforms itself, ScanSource helps vendors reach thousands of customers through logistics, product sourcing, financing, technical support, and specialized channel services. Its focus is mainly on communications, networking, cloud-related solutions, point-of-sale and payments technology, barcode and mobility products, and physical security.
The company reports through two main operating segments. Based on recent annual reporting, revenue is split approximately as follows:
- Specialty Technology Solutions — about 58%: This segment includes communications and collaboration products, networking, cloud and telecom agency services, and other technology infrastructure sold largely through resellers and agents.
- Modern Communications & Cloud — included within Specialty Technology Solutions: While not always broken out as a separate revenue line in headline reporting, this activity is strategically important because it includes recurring agency and cloud-related services tied to communications and connectivity.
- Intelisys and advisory-based connectivity services — smaller than hardware distribution but strategically meaningful: This business helps partners source telecom, cloud, and managed services, giving ScanSource exposure to more recurring commissions than a pure hardware distributor typically has.
- Retail Channel Solutions — about 42%: This segment distributes barcode scanners, mobile computers, point-of-sale systems, payment terminals, and related software and services used by retailers, warehouses, and other front-line operations.
Geographically, the business is primarily concentrated in the United States, with additional operations in Latin America and some international exposure through supplier and partner networks. The business model is high volume and low margin, which is common in distribution: large sales flow through the income statement, but only a modest share remains as profit after product costs and operating expenses.
The flow of revenue to profit reflects that structure clearly. Gross profit has recovered alongside revenue in the latest fiscal year, and interest expense has declined meaningfully from earlier peaks, showing a cleaner balance sheet. At the same time, operating expenses have risen, which limits how much of the revenue improvement turns into bottom-line expansion.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Electronics & Computer Distribution | |
| Market Cap ⓘ | $1.18B | |
| Beta ⓘ | 1.24 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 15.23 | 29.51 |
| FCF Yield ⓘ | 9.63% | 4.25% |
| EBIT / EV ⓘ | 9.75% | 2.85% |
| PEG ⓘ | 0.75 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 17.30% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | 2.07% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | 1.84% | -11.88% |
| Margin Growth (5Y Trend) ⓘ | -0.18% | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | -6.91% | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 7.67% | 9.44% |
| ROIC (5Y Median) ⓘ | 8.21% | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | -0.17 | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.10 | 0.44 |
| Operating Margin (Latest) ⓘ | 3.41% | 9.58% |
| Operating Margin (5Y Median) ⓘ | 3.50% | 8.25% |
| Debt to Equity (Latest) ⓘ | 12.18% | 33.33% |
| Profit Margin (Latest) ⓘ | 2.44% | 7.14% |
| Free Cash Flow (Latest) ⓘ | $113.84M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +96.99% | +45.48% |
| 12M Return (excl. last month) ⓘ | +19.71% | +23.48% |
| 6M Return ⓘ | +61.86% | +20.93% |
| Price vs. 200-Day MA ⓘ | +30.56% | +7.43% |
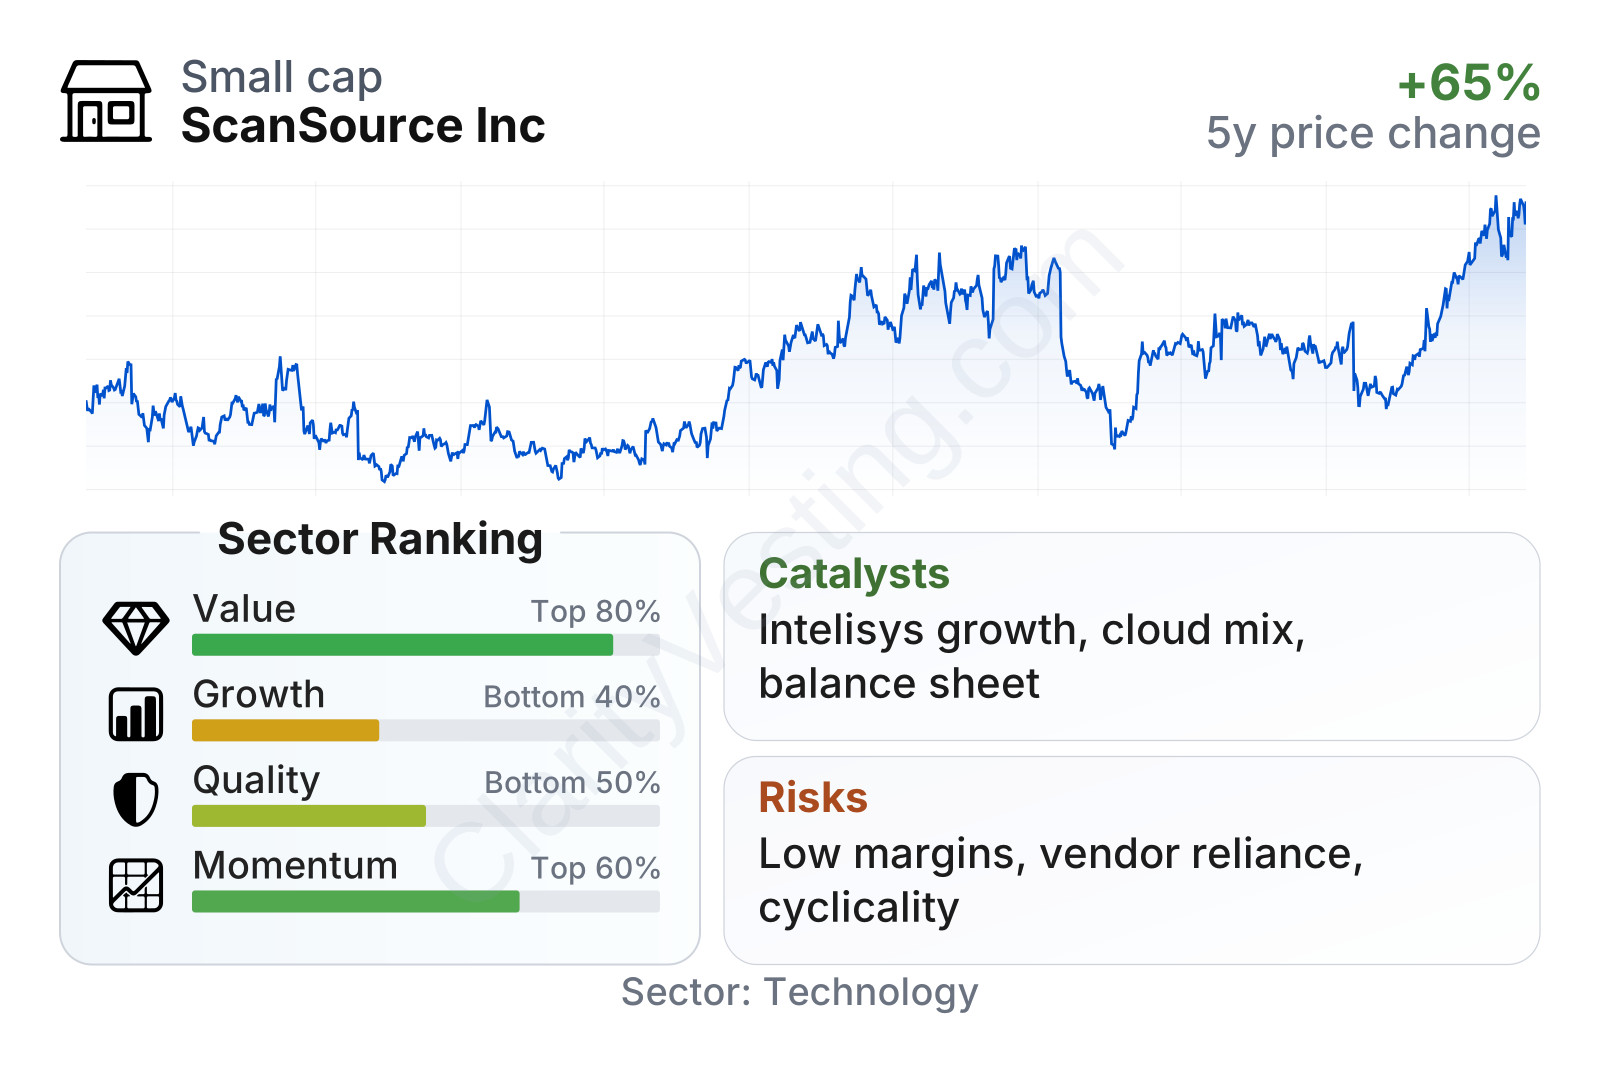
ScanSource is a small-cap technology distributor with a stock that has been more volatile than the broader market, which fits its beta above 1. On valuation, the shares trade at an earnings multiple far below the sector median, while enterprise-value-to-EBIT looks comparatively strong. The mixed part is business quality: returns on invested capital are decent but not exceptional, and operating profitability remains below typical technology-sector levels. Growth characteristics also look uneven, with recent year-over-year improvement better than the sector median but weaker longer-term compounding in revenue per share and free cash flow.
The stock performance trend has been notably stronger than much of the sector over the last several years, although the path has not been smooth. After a major run-up in 2024, the shares pulled back and then partially recovered, which suggests the market is still debating how durable the company’s recovery and earnings profile really are.
Growth
ScanSource operates in parts of the market that still have long-term relevance: cloud communications, hybrid IT infrastructure, networking, payments, retail automation, barcode capture, and mobility solutions. These are not flashy corners of technology, but they are important tools for business operations. That gives the company exposure to durable demand drivers such as digital transformation, omnichannel retail, warehouse automation, and the ongoing shift from on-premise communications hardware toward cloud and recurring connectivity services.
The company’s strategy makes sense if viewed as a transition from traditional box-moving distribution toward a broader solutions platform. The Intelisys business is central to that shift because it connects partners with telecom, cloud, and managed service providers and can create recurring commission streams. That matters for long-term investors because recurring revenue is usually more stable than one-time product transactions. ScanSource has also emphasized higher-value categories such as networking, security, and communications, where specialized channel relationships can matter more than simple scale.
Revenue momentum has been choppy over the last few years. The company moved from strong growth into a notable contraction during the post-pandemic normalization period, then returned to positive year-over-year growth more recently. The latest trend looks encouraging because growth has reaccelerated into the mid-to-high teens range, slightly ahead of the sector median, but the longer record shows that ScanSource is still working through a cyclical business rather than delivering a consistently compounding profile.
Cash generation is another important part of the growth picture. Free cash flow has been volatile, swinging from negative territory to a very strong rebound and then moderating. That pattern is common in distribution because working capital can move sharply with inventories, receivables, and supplier terms. Even so, the fact that cash flow remained positive in more recent periods supports the view that the business is financially flexible while it repositions toward higher-value and more recurring activities.
Recent company updates have pointed to improving sales trends, stronger demand in networking and communications, and continued emphasis on cloud and agent-based services. None of these developments alone transforms the business, but together they create a credible path for steadier growth if end-market demand holds up and recurring services continue to gain share inside the mix.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


