Stock Analysis · Rush Street Interactive Inc (RSI)
Overview
Rush Street Interactive Inc. is an online gambling company focused on two main activities: online casino games and online sports betting. It operates consumer-facing brands such as BetRivers and PlaySugarHouse, and it offers its products through mobile apps and websites. The company is active primarily in the United States and Canada, with an additional presence in Latin America, most notably Colombia. Its business model is straightforward: it attracts players to its platforms, earns money from gaming activity, and uses technology, marketing, and player retention tools to keep those customers engaged over time.
Revenue mainly comes from real-money online gaming. Based on the company’s reporting, the business is overwhelmingly driven by online casino and online sports betting activity, while geography also matters because North America accounts for most of the business. The broad revenue mix can be described as follows:
- Online casino and other iGaming revenue: approximately 55% to 65% of revenue in recent years. This includes digital slot games, table games, and other casino-style offerings. This part of the business typically carries higher margins than sports betting.
- Online sports betting revenue: approximately 35% to 45% of revenue. This includes wagers placed on professional, college, and international sporting events. Sports betting can produce faster customer acquisition but usually operates with lower margins and more quarter-to-quarter volatility.
- United States and Canada: approximately 85% to 95% of total revenue. These markets are the core of the company and include its largest state operations.
- Latin America: approximately 5% to 15% of total revenue. Colombia has historically been the main international market, with the region giving the company geographic diversification even though it remains much smaller than North America.
One important feature of the business is that online casino tends to be more stable and more profitable than sports betting alone. That matters for Rush Street Interactive because it is not purely a sportsbook operator. It has built its identity around a broader online gaming platform, which can help smooth results compared with businesses that depend more heavily on sports seasons and promotional spending.
The financial flow over the last several years shows a clear improvement in scale. Revenue has expanded strongly from 2021 through 2025, gross profit has risen with it, and the company has moved from meaningful losses toward positive net income and cash generation. Even so, operating profitability has not yet become consistently strong, which means the business is still in a transition from growth mode to mature earnings mode.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Gambling | |
| Market Cap ⓘ | $6.46B | |
| Beta ⓘ | 1.51 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 85.26 | 17.10 |
| FCF Yield ⓘ | 2.64% | 8.53% |
| EBIT / EV ⓘ | 5.45% | 6.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 46.30% | 5.75% |
| RPS Growth (5Y CAGR) ⓘ | -13.29% | 9.14% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.21% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.23% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 54.92% | 12.61% |
| ROIC (5Y Median) ⓘ | -69.39% | 10.72% |
| Net Debt / EBIT (Latest) ⓘ | -2.22 | 2.10 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.32 |
| Operating Margin (Latest) ⓘ | 10.82% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -7.07% | 9.64% |
| Debt to Equity (Latest) ⓘ | 7.99% | 75.78% |
| Profit Margin (Latest) ⓘ | 2.34% | 5.33% |
| Free Cash Flow (Latest) ⓘ | $170.74M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +394.02% | +14.53% |
| 12M Return (excl. last month) ⓘ | +25.61% | +3.08% |
| 6M Return ⓘ | +26.88% | +0.55% |
| Price vs. 200-Day MA ⓘ | +11.29% | -0.54% |
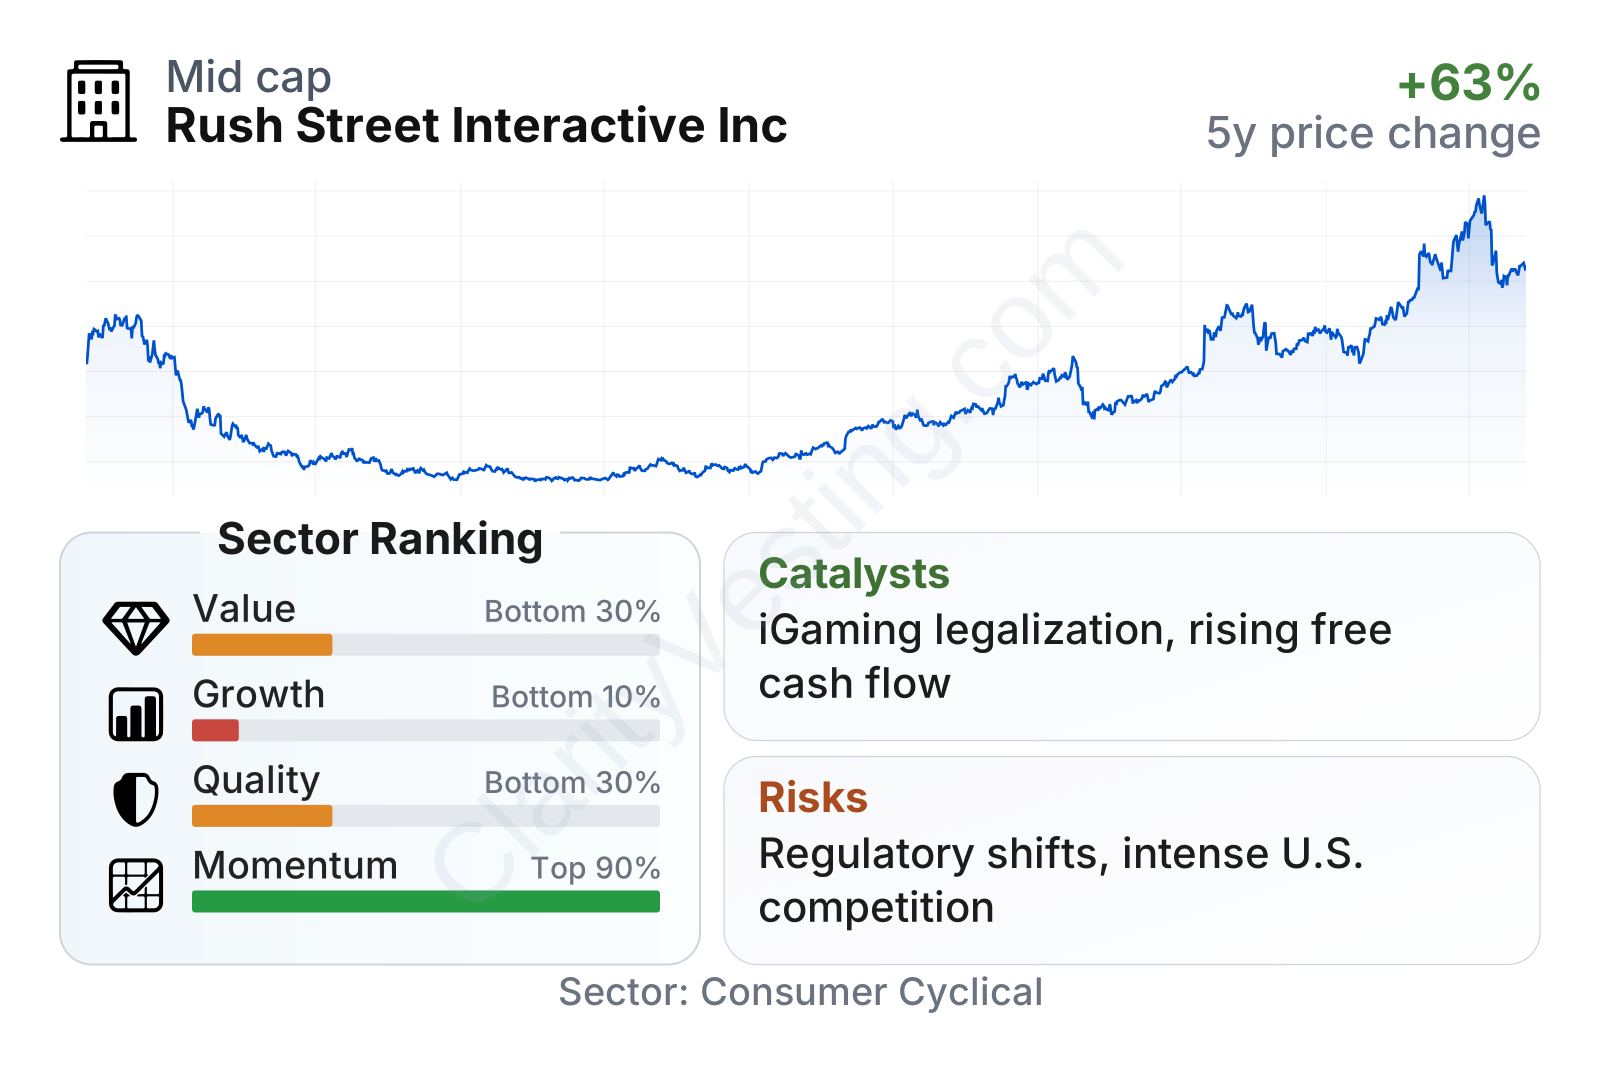
Rush Street Interactive is now a mid-sized public company with a stock that has been very volatile but has also recovered sharply from its 2022–2023 lows. The latest factor snapshot is mixed in an interesting way: momentum is very strong, leverage is low, and recent operating quality has improved, but traditional valuation measures remain demanding. The growth ranking looks weak in the table despite very strong recent year-over-year revenue expansion because the longer-term per-share record still reflects earlier dilution and the company’s long path to profitability.
Growth
The company operates in a sector that still has room to expand. Online sports betting and iGaming remain a relatively young part of the broader gambling market in North America. The main structural driver is legalization: when more states or provinces permit online wagering or online casino gaming, companies like Rush Street Interactive gain access to entirely new customer pools. Even where online sports betting is already legal, online casino remains underpenetrated, and that is a meaningful point because casino products usually generate better economics than sportsbooks.
Rush Street Interactive’s strategy is logical for long-term expansion. Rather than relying only on headline-grabbing sports betting promotions, it has emphasized a mix of sportsbook and casino products, a proprietary technology stack, and customer retention. That combination can matter because online gambling is expensive to scale if operators need to keep paying heavily for user acquisition. A platform with better retention and cross-selling between sportsbook and casino can become more efficient over time.
Revenue growth has clearly reaccelerated. After expanding at mostly mid-teens to mid-30% rates through 2023 and 2024, the business moved back above 40% year over year in early 2026. That pace is far above the broader sector median and suggests that the company is not just benefiting from market growth, but also improving execution in its existing markets.
Cash generation has also become more convincing. Free cash flow moved from clearly negative levels in 2022 and 2023 to positive territory in 2024, then continued rising through 2025 and into 2026. This shift is important because it suggests that revenue growth is no longer being bought entirely through spending, and that the platform is beginning to show operating leverage.
A notable recent opportunity is the continued expansion of regulated online gaming markets in North America. Every additional state that legalizes online casino is potentially more valuable than a sports-betting-only launch because of higher player frequency and better margins. Rush Street Interactive has also highlighted ongoing product upgrades, personalized promotions, and improved player economics in recent company communications, which fit well with its strategy of growing revenue while tightening efficiency.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


