Stock Analysis · QuinStreet Inc (QNST)
Overview
QuinStreet is a performance marketing company. In simple terms, it helps businesses find customers online and get paid when those marketing efforts lead to measurable consumer actions such as a click, lead, application, or call. The company operates digital media and client-matching platforms, especially in areas where customer acquisition is valuable and heavily regulated, such as insurance, consumer finance, home services, and business-to-business software.
Its model is different from a traditional advertising agency. QuinStreet typically uses its own websites, publisher network, technology, and data tools to connect consumers who are actively shopping for a product with companies willing to pay for those potential customers. That makes the business closely tied to client demand, online traffic quality, and the economics of the categories it serves.
Based on recent company filings, revenue is organized mainly into two broad verticals:
- Financial Services: approximately 75% to 85% of revenue in recent periods. This includes insurance, credit cards, banking, personal loans, and related consumer-finance customer acquisition programs.
- Home Services and Other: approximately 15% to 25% of revenue. This includes home improvement, moving, solar, and selected business-to-business or other marketplace categories.
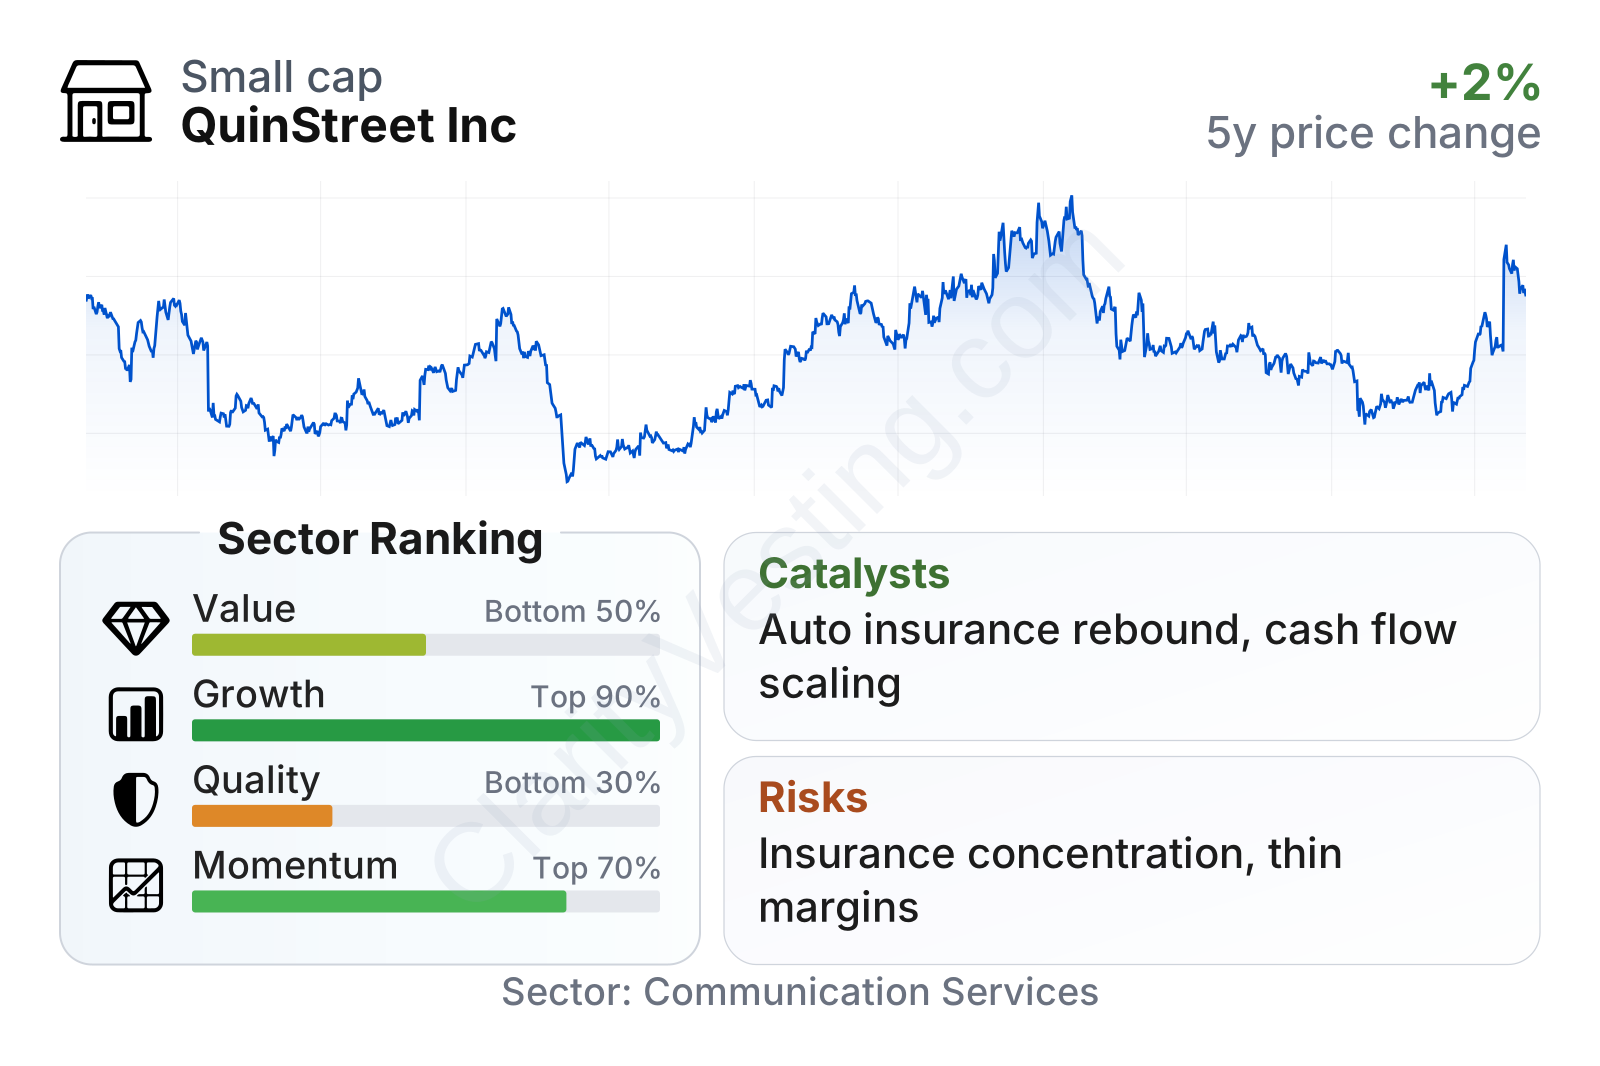
Within Financial Services, auto insurance has been a particularly important driver of the recent rebound, as large carriers restarted or increased customer acquisition spending after a weaker period for the insurance market. That concentration helps explain both the company’s recent acceleration and some of its risk profile.
The business mix has improved noticeably over the last two years. Revenue expanded sharply while operating income and net income moved from losses to profits, showing that recent volume growth has started to scale through the cost structure rather than being absorbed entirely by expenses.
The big picture is a company that acts as a digital middleman in high-value consumer categories. It does not need to manufacture a product, but it does need to continuously prove that its leads are efficient and profitable for clients.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 06, 2026 | |
| Context | ||
| Sector | Communication Services | |
| Industry | Advertising Agencies | |
| Market Cap ⓘ | $1.07B | |
| Beta ⓘ | 0.70 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.38 | 18.41 |
| FCF Yield ⓘ | 11.93% | 13.13% |
| EBIT / EV ⓘ | 3.47% | 4.58% |
| PEG ⓘ | 1.13 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 42.70% | 5.50% |
| RPS Growth (5Y CAGR) ⓘ | 20.04% | 5.02% |
| EPS Growth (5Y CAGR) ⓘ | 32.21% | -18.11% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.70% |
| FCF Growth (5Y CAGR) ⓘ | 56.69% | 5.95% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 26.81% | 8.53% |
| ROIC (5Y Median) ⓘ | -1.26% | 8.32% |
| Net Debt / EBIT (Latest) ⓘ | -1.51 | 1.70 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.78 |
| Operating Margin (Latest) ⓘ | 2.74% | 14.90% |
| Operating Margin (5Y Median) ⓘ | -0.81% | 13.00% |
| Debt to Equity (Latest) ⓘ | 23.18% | 60.48% |
| Profit Margin (Latest) ⓘ | 6.28% | 8.78% |
| Free Cash Flow (Latest) ⓘ | $127.53M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +94.90% | +48.60% |
| 12M Return (excl. last month) ⓘ | -5.44% | +2.67% |
| 6M Return ⓘ | +49.60% | +2.20% |
| Price vs. 200-Day MA ⓘ | +32.71% | +3.64% |
QuinStreet is a mid-sized company with a stock that has been volatile over the last several years. The latest factor snapshot shows a mixed profile: growth ranks near the top of its sector, momentum is also favorable, while quality remains weaker because margins are still below typical sector levels even after a strong recovery. On valuation, the earnings multiple sits below the sector median, but cash-flow-based measures look closer to average than deeply discounted. Financial leverage remains modest, which gives the company more flexibility than many peers.
Growth
QuinStreet operates in a market with durable long-term demand. Insurance carriers, lenders, and home-services providers all need efficient digital customer acquisition. Over time, advertising budgets have continued shifting toward channels where spending can be measured directly. That trend supports the company’s business model because clients increasingly want marketing partners that can show a clear return on each dollar spent.
The company’s strategy also makes sense for future growth. QuinStreet focuses on categories where one acquired customer can be worth a lot to the client, which allows room for attractive pricing if lead quality is high. It also invests in media, data, and technology to improve matching, traffic conversion, and campaign performance. If it can keep delivering strong economics to clients, that can reinforce a cycle of higher spending, more traffic monetization, and better scale.
Recent growth has been unusually strong. Revenue growth moved from declines in 2023 and early 2024 to very high year-over-year expansion in late 2024, then stayed positive into 2026 at levels still far above the sector median. Even though the peak growth rates have cooled from extreme levels, the latest readings still point to a business that remains in an expansion phase rather than a short-lived bounce ending immediately.
Cash generation has improved alongside revenue. Free cash flow was negative during the weaker period, then turned strongly positive and continued rising. That matters because it suggests the turnaround is not limited to accounting earnings. A business that can convert renewed demand into cash has a firmer base for reinvestment, acquisitions, or balance-sheet protection.
One of the clearest catalysts has been the recovery in insurance advertising demand, particularly in auto insurance. As underwriting conditions improved across parts of the insurance industry, carriers had more reason to resume policy growth and spend more on lead generation. QuinStreet has also highlighted expanding media capacity and deeper relationships with major clients as additional support for growth. If those trends continue, the company could benefit from both higher volumes and better operating leverage.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer