Stock Analysis · Everpure Inc (P)
Overview
Everpure Inc operates in computer hardware, with a focus on high-performance data infrastructure used in cloud computing, enterprise systems, and artificial intelligence workloads. The business model is centered on designing and integrating hardware platforms that help customers run demanding applications efficiently. In practical terms, the company sells servers, storage systems, and related platform solutions rather than consumer devices.
Based on the company’s recent annual reporting structure, revenue is primarily generated from product sales, with a smaller contribution from support and services. Public filings for companies in this part of the hardware industry typically show products as the clear majority of sales, while service and support revenue adds recurring but smaller income. A simple breakdown is:
- Product revenue: the large majority of total sales, driven by server and storage systems, complete rack-scale solutions, and hardware platforms used in data centers.
- Service and support revenue: a smaller share, including installation, maintenance, technical support, and other customer services tied to deployed systems.
The business profile also shows an important economic trait: gross profit has expanded as sales increased, while research and development spending remains high. That points to a company trying to capture fast-moving infrastructure demand without giving up product investment. Over the last five fiscal years, revenue rose from about $2.2 billion to about $3.7 billion, operating income moved from a loss to a positive result, and net income also turned meaningfully positive. Interest expense has fallen sharply, which suggests a cleaner balance sheet and lower financing pressure than a few years ago.
Revenue growth has been accompanied by improving profitability, but the company is still spending aggressively on research and development. That combination is often seen in hardware businesses trying to defend their technological relevance while scaling into larger markets such as AI and cloud infrastructure.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Computer Hardware | |
| Market Cap ⓘ | $31.36B | |
| Beta ⓘ | 1.43 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 132.54 | 29.51 |
| FCF Yield ⓘ | 0.41% | 4.25% |
| EBIT / EV ⓘ | 0.86% | 2.85% |
| PEG ⓘ | 1.98 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 20.40% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | 8.53% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | -18.15% | -11.88% |
| Margin Growth (5Y Trend) ⓘ | 10.53% | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | 18.92% | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 16.75% | 9.44% |
| ROIC (5Y Median) ⓘ | N/A | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | -0.59 | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.80 | 0.44 |
| Operating Margin (Latest) ⓘ | 6.35% | 9.58% |
| Operating Margin (5Y Median) ⓘ | 3.51% | 8.25% |
| Debt to Equity (Latest) ⓘ | 14.62% | 33.33% |
| Profit Margin (Latest) ⓘ | 5.94% | 7.14% |
| Free Cash Flow (Latest) ⓘ | $128.17M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +156.41% | +45.48% |
| 12M Return (excl. last month) ⓘ | +87.51% | +23.48% |
| 6M Return ⓘ | +60.95% | +20.93% |
| Price vs. 200-Day MA ⓘ | +29.65% | +7.43% |
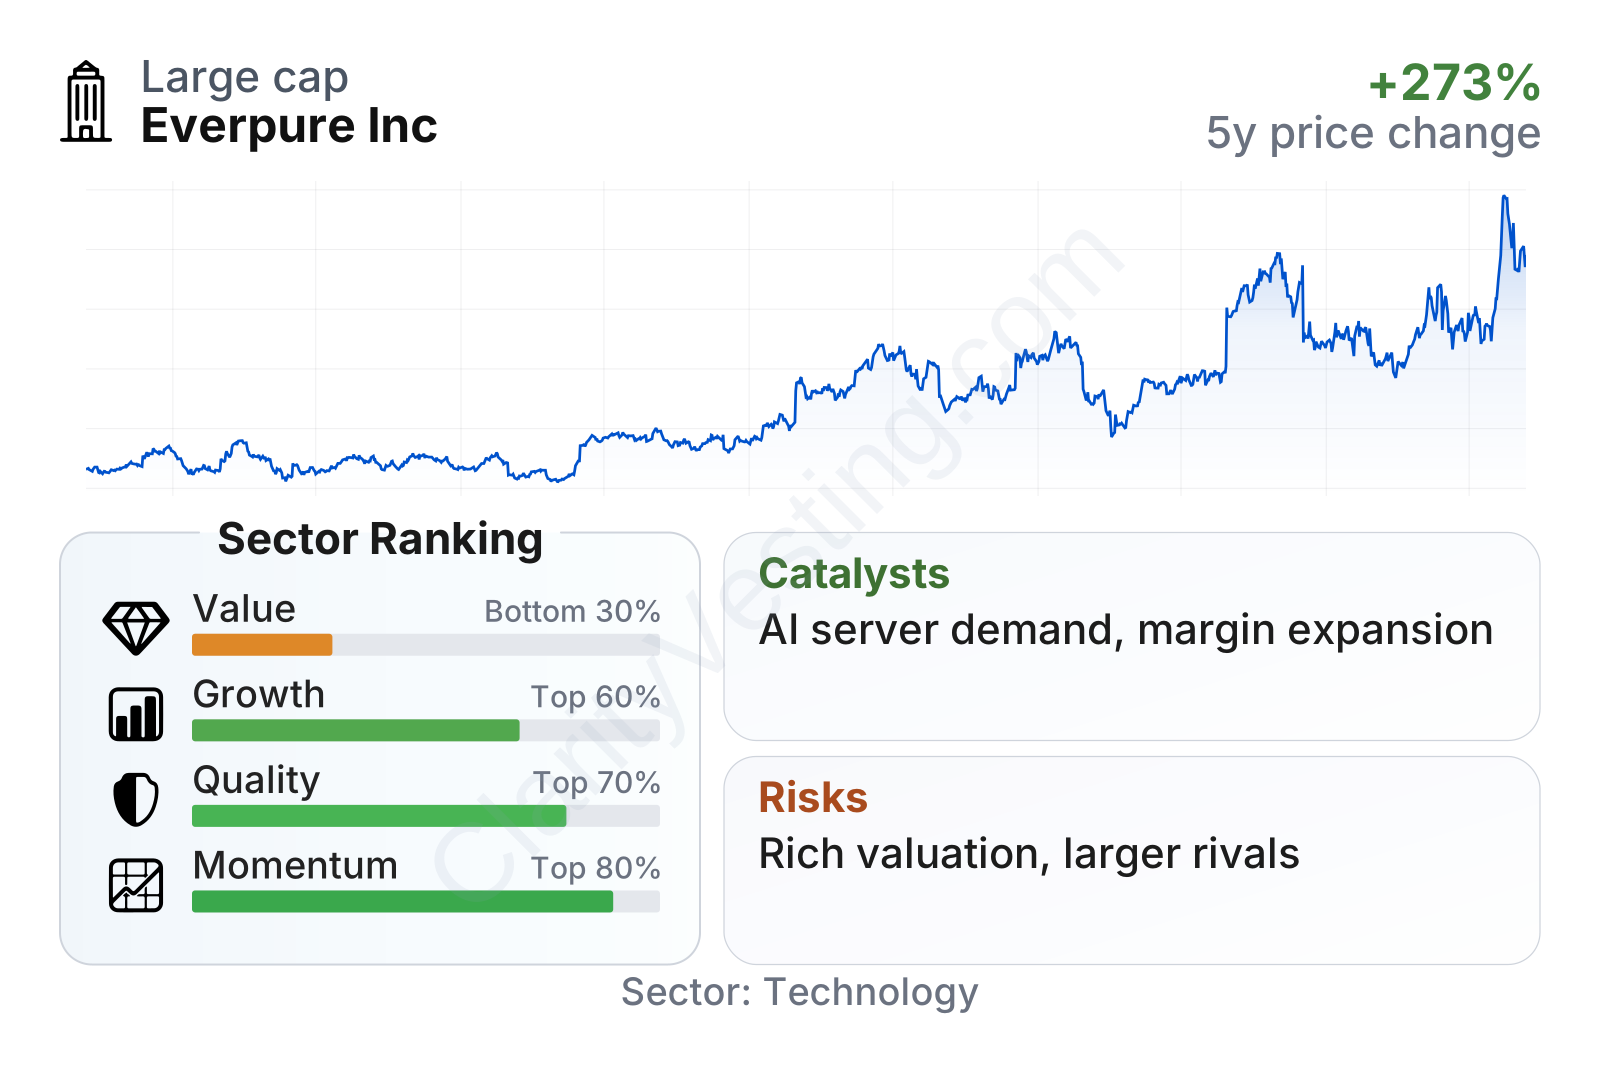
Everpure is now a large-cap technology company, but its trading profile remains more volatile than the broader market, with a beta above 1.4. The factor snapshot is mixed. Growth, quality, and momentum rank relatively well within the sector, helped by revenue acceleration, strong capital efficiency, and a stock price that has materially outperformed the sector median over multi-year and recent periods. The weak point is valuation: earnings and cash-flow-based multiples sit far above typical sector levels, which means the market is already pricing in substantial future progress.
The stock chart also reflects that tension. The share price has climbed strongly since 2023, but with notable swings along the way. That pattern usually signals a company tied to powerful themes but also to changing expectations around growth, margins, and execution.
Growth
Everpure operates in a part of technology that is benefiting from several durable industry trends: rising demand for AI infrastructure, continued buildout of cloud capacity, more complex enterprise computing needs, and ongoing investment in data-center modernization. Those are favorable end markets because they require increasingly dense and specialized hardware configurations, which can lift both system demand and average selling prices.
The company’s strategy appears aligned with that environment. It has maintained heavy research and development spending while expanding revenue, suggesting it is trying to stay close to the next wave of hardware requirements rather than competing only on standard equipment. That matters in AI-related infrastructure, where customers often need highly customized, power-intensive, and integrated systems.
Recent growth has clearly strengthened. Year-over-year revenue growth moved back into a much higher range in 2026, reaching roughly 20% on a trailing basis and accelerating sharply in the latest quarterly path. That is stronger than the sector median and signals that demand has improved after a more uneven period in 2023 and early 2024. Over a longer horizon, revenue per share growth has been broadly in line with the sector, but the latest acceleration is more notable than the five-year average.
Cash generation also supports the expansion profile. Free cash flow has trended upward over the last several years and recently stood above $600 million on a trailing basis. That does not make the stock look cheap, but it does show that growth is not purely accounting-driven. The company is translating more of its scale into cash, which gives it flexibility to invest in product development, operations, and customer support without leaning heavily on debt.
A meaningful catalyst is the broader buildout of AI servers and data-center hardware. If enterprise and hyperscale customers continue refreshing infrastructure for AI training and inference, suppliers with proven integration capabilities can benefit disproportionately. Another positive signal is margin improvement over time: the five-year operating margin trend is substantially better than the sector median, which suggests the business has been gaining discipline even though current margins are still not best-in-class.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


