Stock Analysis · OneSpaWorld Holdings Ltd (OSW)
Overview
OneSpaWorld Holdings Ltd operates health and wellness services mainly on cruise ships and, to a smaller extent, in destination resorts. Its business is built around managing onboard spas, beauty salons, fitness centers, and wellness-related retail offerings for cruise lines. In simple terms, the company does not own the ships; it runs the wellness spaces and sells treatments, products, and related services to travelers while sharing economics with its travel partners.
The company’s revenue is concentrated in the cruise industry. Based on recent annual filings, the business mix is heavily tilted toward services and product sales onboard cruise ships, with resort and destination operations contributing a much smaller share.
- Cruise ship wellness services and product sales: approximately 90%+. This includes spa treatments such as massages and facials, salon services, fitness offerings, medi-spa services where permitted, and retail sales of skincare and wellness products onboard.
- Destination resort and onshore operations: approximately 5% to 10%. This includes spa and wellness services provided at selected resorts and related locations.
- Other revenue: limited. This can include smaller ancillary streams tied to its operating model, but they are not a major driver of the group.
What stands out in the business model is that revenue depends on passenger traffic, onboard spending, treatment utilization, and retail attachment rates rather than on large fixed real estate ownership. That asset-light structure can support strong returns when travel demand is healthy, but it also makes results highly sensitive to cruise volumes and vacation spending trends.
The financial progression over the last several years shows a sharp recovery from the travel downturn, with revenue rising from a low post-pandemic base to nearly $1 billion by 2025. Profitability also improved materially after the disruption period, although the most recent annual figures suggest gross profit pressure even as revenue kept expanding, which is worth watching.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Leisure | |
| Market Cap ⓘ | $2.21B | |
| Beta ⓘ | 0.90 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 27.52 | 17.10 |
| FCF Yield ⓘ | 3.55% | 8.53% |
| EBIT / EV ⓘ | 4.25% | 6.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.50% | 5.75% |
| RPS Growth (5Y CAGR) ⓘ | 55.20% | 9.14% |
| EPS Growth (5Y CAGR) ⓘ | 20.67% | -18.21% |
| Margin Growth (5Y Trend) ⓘ | 46.37% | -0.23% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.30% | 12.61% |
| ROIC (5Y Median) ⓘ | 11.96% | 10.72% |
| Net Debt / EBIT (Latest) ⓘ | 0.52 | 2.10 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.88 | 2.32 |
| Operating Margin (Latest) ⓘ | 9.58% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 8.46% | 9.64% |
| Debt to Equity (Latest) ⓘ | 15.60% | 75.78% |
| Profit Margin (Latest) ⓘ | 8.02% | 5.33% |
| Free Cash Flow (Latest) ⓘ | $78.23M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +88.75% | +14.53% |
| 12M Return (excl. last month) ⓘ | +21.76% | +3.08% |
| 6M Return ⓘ | +6.38% | +0.55% |
| Price vs. 200-Day MA ⓘ | -6.79% | -0.54% |
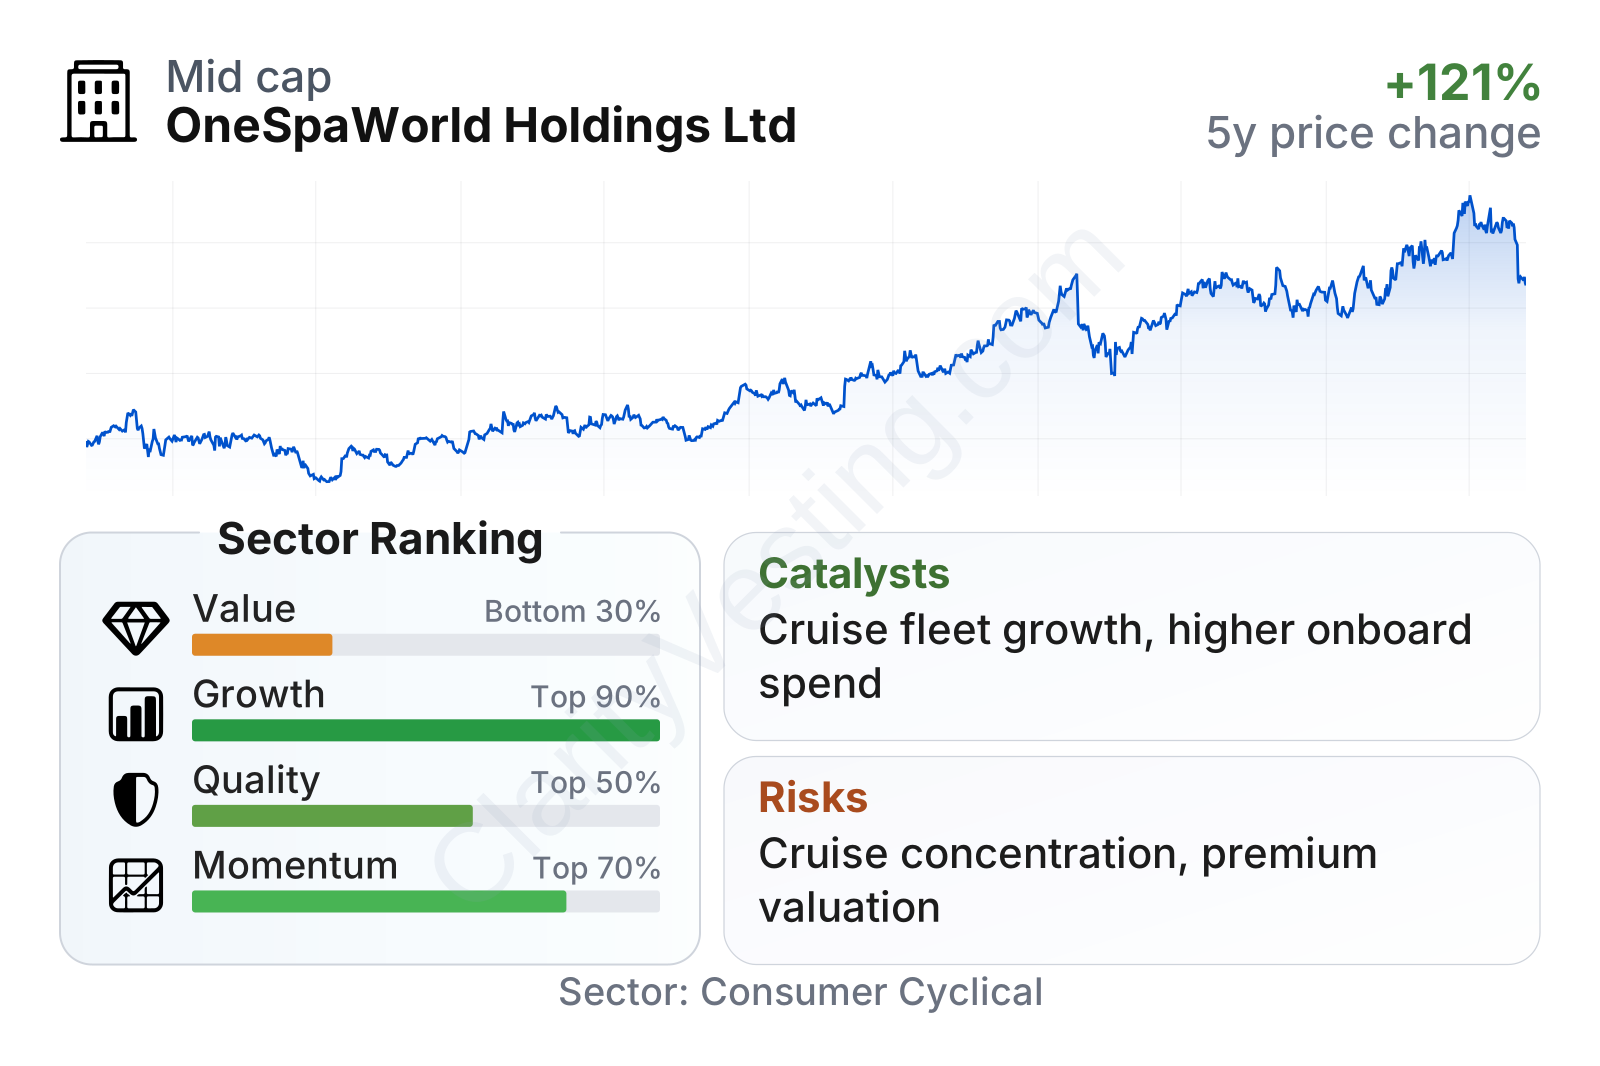
OneSpaWorld is now a mid-sized public company with a market value in the low single-digit billions and a beta slightly below 1, suggesting share-price volatility that has been broadly in line with, or a bit lower than, the market. The broad picture from the factor table is clear: growth and market performance have been strong relative to the sector, balance sheet quality is solid, but valuation metrics look demanding. Revenue growth is running above the sector median, profitability is healthy, and leverage is much lower than most peers. The trade-off is that the stock is priced at a meaningfully higher earnings multiple and offers a lower cash flow yield than the sector median, so the market is already recognizing much of the company’s recovery and expansion profile.
Growth
OneSpaWorld operates in a sector with favorable long-term support: leisure travel, cruise capacity growth, and consumer interest in wellness experiences. The company sits at the intersection of two durable trends. First, cruise operators continue to add ships and premium onboard experiences to raise passenger spending. Second, wellness has become a more important part of vacation spending, which supports demand for spa treatments, beauty services, and higher-ticket wellness offerings.
The company’s strategy is logical for this environment. It focuses on long-standing relationships with major cruise lines, onboard service execution, training and staffing, digital tools that can improve booking and guest conversion, and product sales tied to treatments. Because new ships typically come with wellness space designed into the guest experience, fleet growth across partner cruise lines can create a steady pipeline for additional locations without OneSpaWorld needing to build standalone properties itself.
Growth has normalized from the very high rebound rates seen after the travel recovery, but recent year-over-year increases still point to a business expanding faster than much of its sector. That matters because it suggests the company is no longer relying only on a one-time post-pandemic recovery; it is still adding revenue on top of a much larger base.
Cash generation is another important positive. Free cash flow moved from negative territory during the recovery period to clearly positive levels, and it has remained solid even after the rebound phase. While the latest trailing figure is below the earlier peak, the business is still producing meaningful cash, which gives management room for debt reduction, capital allocation flexibility, and operational investment.
A notable catalyst is continued cruise industry capacity expansion. Each incremental ship launch by partner fleets can create fresh treatment rooms, salon stations, retail points of sale, and onboard wellness demand. The company has also highlighted initiatives around upgraded wellness concepts and higher-yield services, which could lift revenue per passenger beyond simple volume growth. In recent company updates, management has continued to point to healthy demand trends, ship additions, and operational execution as key opportunities for further expansion.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


