Stock Analysis · NCR Atleos Corporation (NATL)
Overview
NCR Atleos Corporation is a financial technology and self-service infrastructure company focused on cash access, ATM networks, and related software and services. The business was separated from NCR Corporation in 2023 and now operates as an independent public company. In simple terms, Atleos helps banks, credit unions, retailers, and other institutions manage ATMs, move cash efficiently, and connect to a large network that allows consumers to withdraw and deposit money in many locations.
Its business model combines hardware, software, recurring service contracts, transaction processing, and network revenue. That mix matters because it gives the company exposure not only to selling machines, but also to ongoing usage of those machines and the software layer around them.
Based on company reporting, revenue is mainly generated from the following activities:
- Self-Service Banking segment — roughly 65% to 75%: ATM hardware, installation, maintenance, managed services, software, and professional services for financial institutions.
- Network segment — roughly 25% to 35%: transaction-driven revenue from ATM access, surcharge-free and branded cash access networks, and services tied to cash withdrawal and deposit activity.
The revenue profile also shows a useful pattern: total sales have been relatively stable in the low-$4 billion range, while operating income improved meaningfully after the spin-off period. Gross profit has also trended upward over the last few years, suggesting the company has been getting more out of each dollar of sales even without rapid top-line expansion.
Revenue has been steady, but the more important shift is in profitability. Operating income rose sharply from 2023 to 2024 and stayed elevated in 2025, helped by lower operating expenses as a share of revenue. That suggests Atleos is becoming more efficient, although interest expense still absorbs a large portion of those gains.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Software - Application | |
| Market Cap ⓘ | $3.45B | |
| Beta ⓘ | 0.56 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 17.93 | 29.51 |
| FCF Yield ⓘ | 3.13% | 4.25% |
| EBIT / EV ⓘ | 8.51% | 2.85% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 0.10% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | 3.16% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -11.88% |
| Margin Growth (5Y Trend) ⓘ | 2.09% | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | -8.30% | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 13.12% | 9.44% |
| ROIC (5Y Median) ⓘ | 9.13% | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | 4.97 | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | 5.32 | 0.44 |
| Operating Margin (Latest) ⓘ | 11.41% | 9.58% |
| Operating Margin (5Y Median) ⓘ | 8.45% | 8.25% |
| Debt to Equity (Latest) ⓘ | 632.76% | 33.33% |
| Profit Margin (Latest) ⓘ | 4.44% | 7.14% |
| Free Cash Flow (Latest) ⓘ | $108.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +45.48% |
| 12M Return (excl. last month) ⓘ | +27.85% | +23.48% |
| 6M Return ⓘ | +5.21% | +20.93% |
| Price vs. 200-Day MA ⓘ | +8.17% | +7.43% |
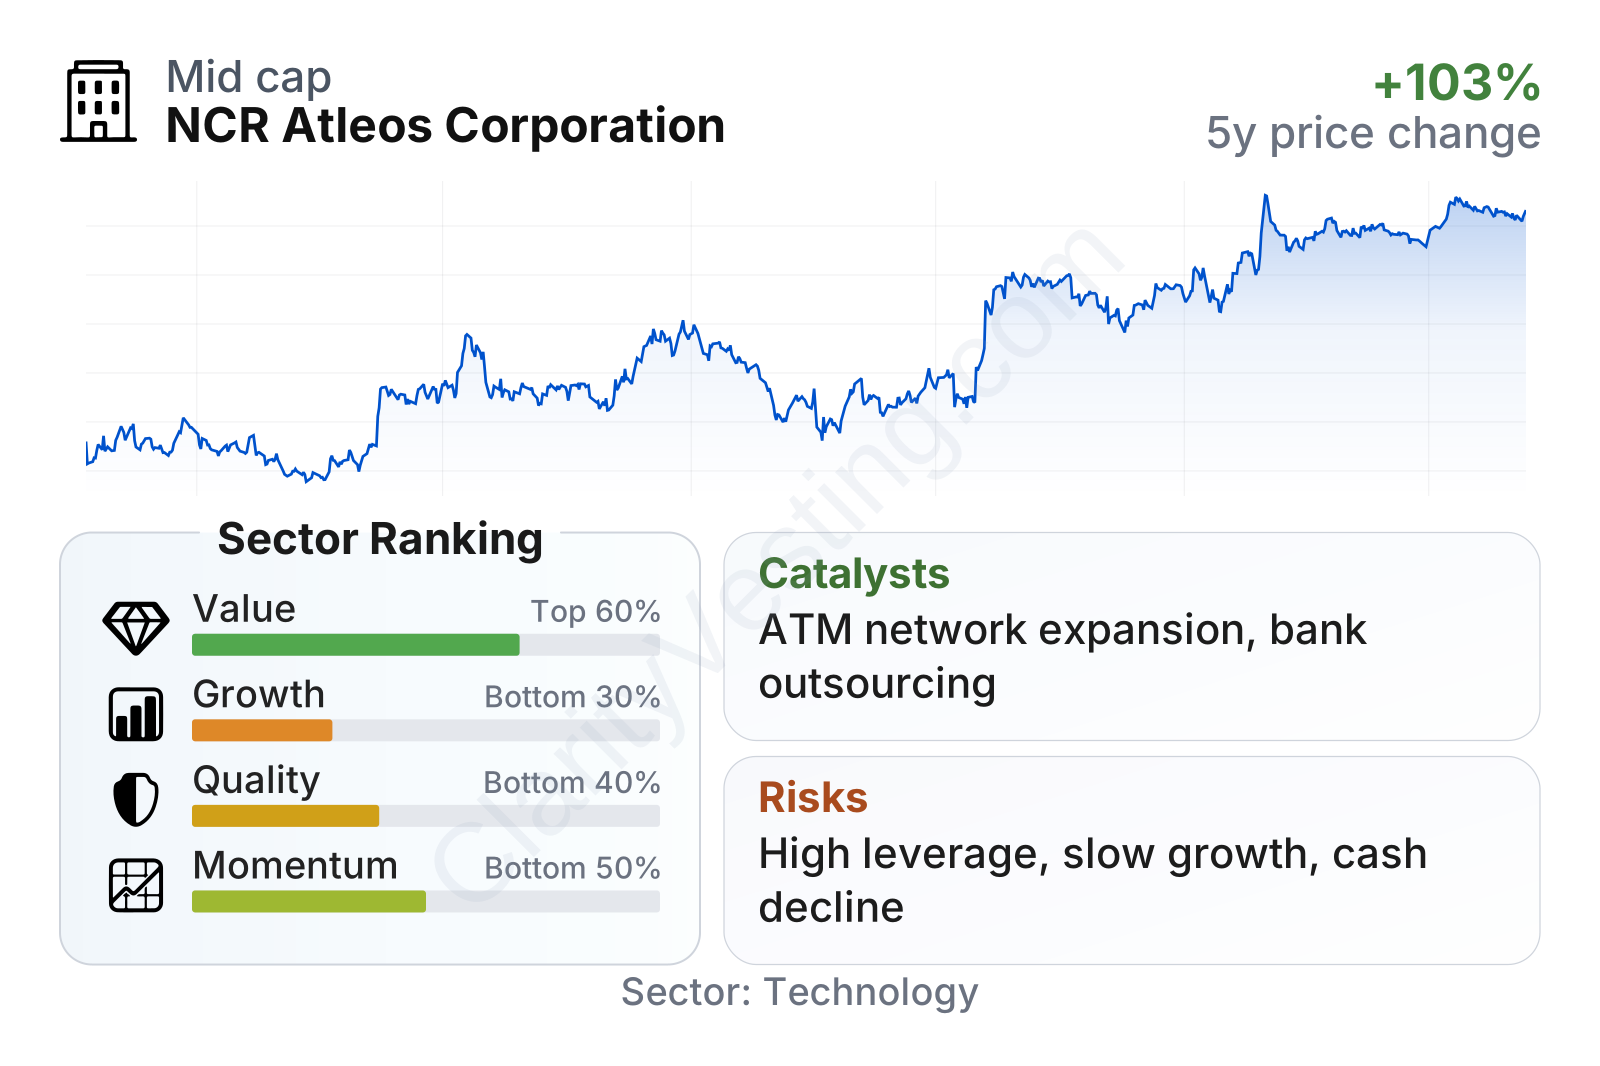
Atleos is a mid-sized technology company with a stock that has moved up strongly since late 2023. Recent momentum has been better than much of the sector over the last year, while the valuation multiple remains below the sector median. The mixed picture is in the fundamentals behind that valuation: operating margins and returns on invested capital are solid, but growth ranks weakly against peers and leverage remains unusually high.
Growth
Atleos operates in a niche that does not look like a typical high-growth software market, but it sits in an area that remains relevant: physical cash access. Even in a world of digital payments, cash is still important for many consumers, retailers, and underbanked populations. Banks also continue to look for ways to reduce branch costs while keeping customer access points available, which supports outsourced ATM management and shared cash infrastructure.
The company’s strategy appears logical for this environment. Instead of depending only on selling ATMs, it is emphasizing connected services, ATM-as-a-service capabilities, software, and network transactions. That can make revenue more recurring and can strengthen customer relationships over time. A large installed base and a broad servicing footprint can also create switching friction, because banks do not casually replace cash infrastructure providers.
Growth has been modest rather than fast. Recent year-over-year revenue changes have hovered around flat to low-single-digit gains, with some quarters better than others. That aligns with the broader impression of the business: this is not a company driven by explosive sales growth, but by infrastructure relevance, recurring service activity, and execution on margin improvement.
Cash generation is an important point to watch. Free cash flow has been positive, but it has also been volatile, with a noticeable decline from earlier levels. For a business with meaningful debt, stable cash conversion matters more than headline revenue growth. A stronger free cash flow trend would improve the overall growth profile because it would give Atleos more room to reduce debt, invest in software and network expansion, and absorb industry swings.
Potential catalysts are tied less to a booming end market and more to execution. Expansion of its cash access network, deeper outsourcing by banks, cross-selling software and managed services into the installed base, and continued cost discipline could all support earnings growth even if revenue stays relatively moderate. The company has also highlighted partnerships and network expansion initiatives in its public communications, which point to a strategy built around making its ATM and cash network more valuable to both financial institutions and retailers.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


