Stock Analysis · Meritage Corporation (MTH)
Overview
Meritage Homes Corporation is a U.S. homebuilder focused on designing and selling single-family homes. The company operates in multiple fast-growing and large housing markets, with a business model centered on acquiring land, developing communities, building homes, and delivering finished houses to buyers. It has increasingly emphasized move-in ready and entry-level homes, which helps it serve households looking for affordability and faster purchase decisions.
Its revenue is overwhelmingly tied to homebuilding, with only a small contribution from financial and related services. Based on recent annual reporting, the main sources of revenue can be summarized as follows:
- Home closings: about 98% to 99% — revenue from selling completed homes across its communities. This is the core of the business and includes the sale price of homes and lots delivered to customers.
- Land and other homebuilding revenue: about 1% or less — occasional sales of land, lots, or other items connected to community development.
- Financial services: about 1% or less — mortgage-related and title-related activity that supports the home sale process, either directly or through affiliated arrangements.
Geographically, Meritage is diversified across major Sun Belt and western markets such as Texas, Florida, Arizona, California, the Carolinas, Tennessee, and Georgia. That matters because population growth, job creation, and housing demand have generally been stronger in many of these regions than in slower-growing parts of the country.
The business has shown that it can produce large revenue and profit dollars when housing conditions are favorable, but it is still a cyclical company. Revenue rose from a little above $5 billion in 2021 to nearly $6.4 billion in 2024 before easing back to about $5.9 billion in 2025. Profitability followed a similar path, peaking during the strongest part of the housing cycle and then moderating as affordability pressure and incentives increased.
Over the last several years, Meritage expanded revenue meaningfully while keeping selling overhead fairly controlled. The more recent change is that gross profit and net income have compressed faster than revenue, showing that today’s challenge is less about demand disappearing entirely and more about margins tightening as the company works to keep homes affordable and sales moving.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Residential Construction | |
| Market Cap ⓘ | $4.19B | |
| Beta ⓘ | 1.36 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.90 | 17.10 |
| FCF Yield ⓘ | 9.91% | 8.53% |
| EBIT / EV ⓘ | 9.36% | 6.46% |
| PEG ⓘ | 0.54 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -13.80% | 5.75% |
| RPS Growth (5Y CAGR) ⓘ | 5.32% | 9.14% |
| EPS Growth (5Y CAGR) ⓘ | -39.73% | -18.21% |
| Margin Growth (5Y Trend) ⓘ | -8.60% | -0.23% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.31% | 12.61% |
| ROIC (5Y Median) ⓘ | 19.48% | 10.72% |
| Net Debt / EBIT (Latest) ⓘ | 2.16 | 2.10 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.59 | 2.32 |
| Operating Margin (Latest) ⓘ | 8.81% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 18.58% | 9.64% |
| Debt to Equity (Latest) ⓘ | 36.52% | 75.78% |
| Profit Margin (Latest) ⓘ | 6.11% | 5.33% |
| Free Cash Flow (Latest) ⓘ | $414.70M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +2.67% | +14.53% |
| 12M Return (excl. last month) ⓘ | +0.39% | +3.08% |
| 6M Return ⓘ | +3.75% | +0.55% |
| Price vs. 200-Day MA ⓘ | -7.88% | -0.54% |
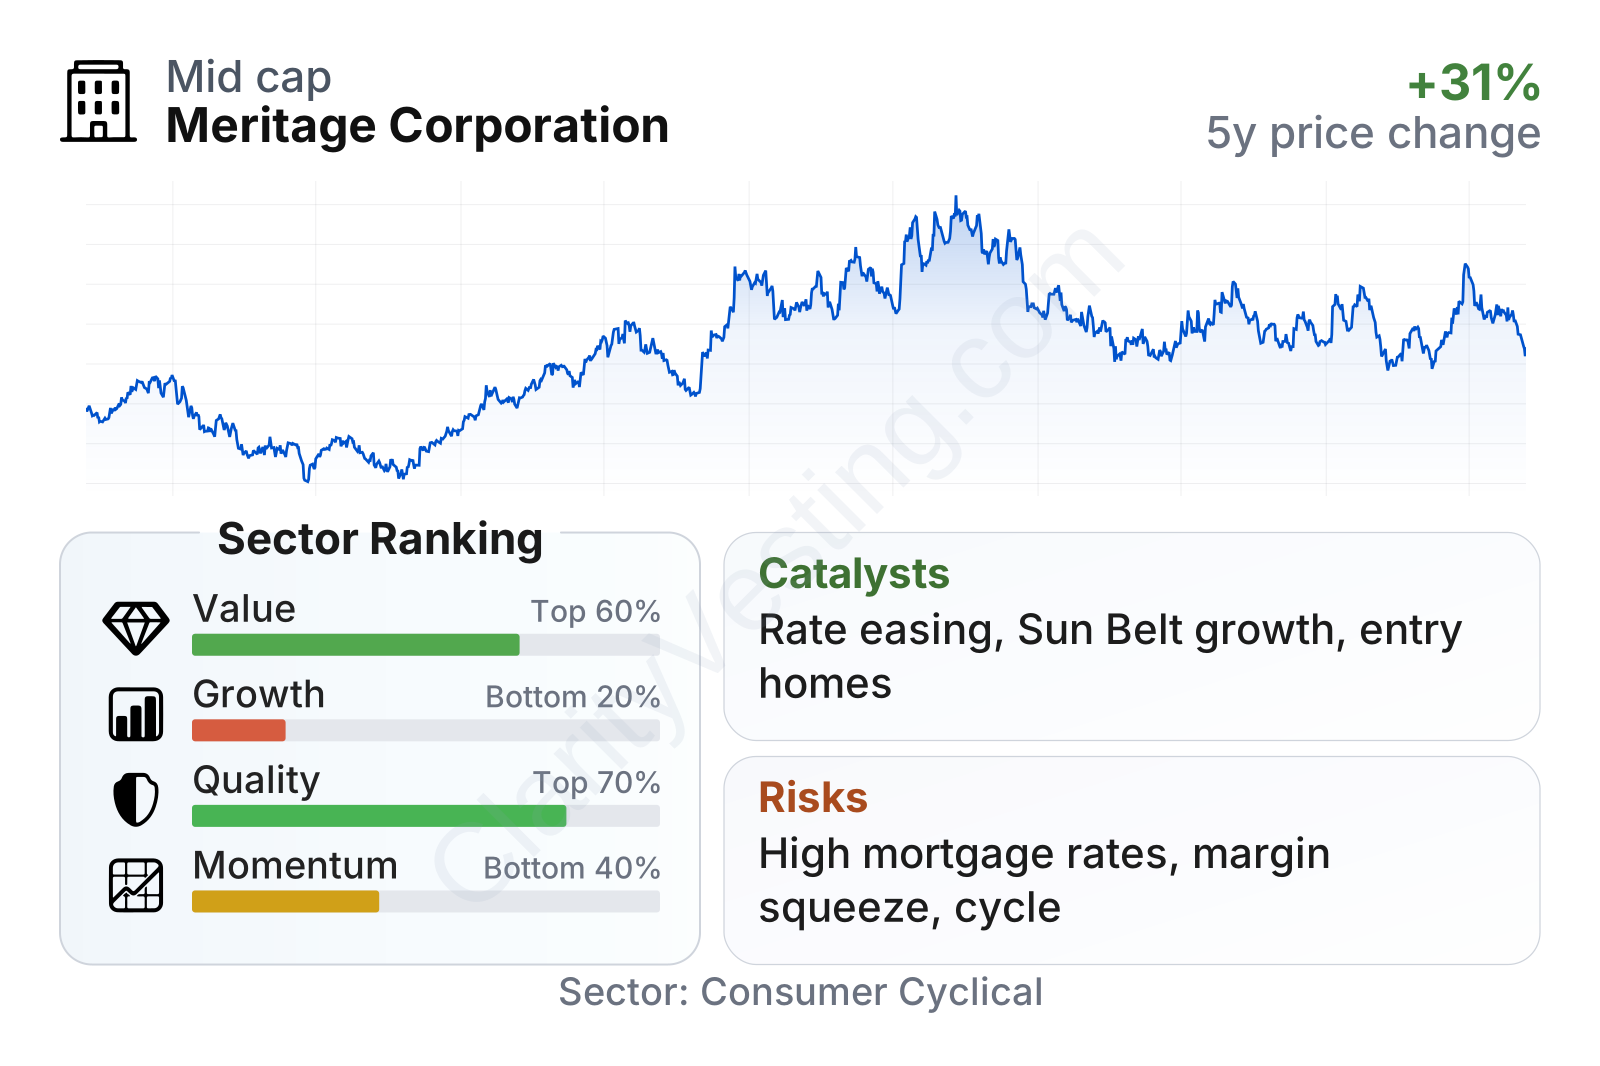
Meritage sits in the mid-cap range and carries above-market share-price volatility, which is common for homebuilders. The overall profile is mixed but understandable for a cyclical company: valuation metrics look stronger than much of the sector, balance-sheet leverage remains moderate, and profitability is still slightly above the industry median on net margin. The weaker area is growth, where recent revenue and earnings trends have lagged the broader consumer cyclical group as the housing market cooled.
The stock’s path over the last few years reflects that cyclicality clearly. After a strong run into 2024, it gave back part of those gains, even though shorter-term performance has been firmer than much of the sector. That combination usually signals a market that still recognizes Meritage’s operating quality, but is no longer willing to award the unusually low earnings multiples seen earlier in the cycle.
Growth
Residential construction remains a structurally important sector because the United States still faces a long-running housing supply shortage in many markets. Over the long term, that creates a supportive backdrop for builders that can control land costs, keep construction efficient, and offer homes at price points that match household budgets. Meritage’s strategy is aligned with that reality: it has leaned heavily into entry-level and first move-up buyers, standardized floorplans, shorter build cycles, and a move-in ready approach designed to reduce friction for buyers.
This strategy makes sense in the current environment because affordability is one of the central issues in housing. A builder that can offer lower monthly payments through smaller footprints, efficient construction, and targeted incentives can still capture demand even when mortgage rates remain elevated. Meritage has also focused on markets with population inflows and relatively better employment growth, which improves the odds of sustained absorption over time.
That said, recent top-line momentum has turned negative. Revenue growth was strong in 2022, became uneven in 2023 and 2024, and has been negative in the latest periods. This helps explain why the company ranks near the bottom of the sector on current growth measures. The important question for long-term analysis is whether this is a structural problem or a cyclical slowdown. At this stage, it looks more cyclical than structural: the company is still active in attractive regions and still serving one of the most needed parts of the housing market, but near-term demand is being held back by financing costs and consumer affordability pressure.
Cash generation has also been volatile, which is normal in homebuilding because land purchases, development timing, and inventory movements can cause major swings from one period to another. Even so, Meritage remains free-cash-flow positive on a trailing basis, and its free cash flow yield compares favorably with much of the sector. That suggests the business is still converting a meaningful amount of earnings into cash despite a tougher operating backdrop.
One of the most important catalysts is any improvement in mortgage-rate conditions or affordability. Even a modest easing in rates could unlock sidelined demand for entry-level buyers, which is exactly where Meritage is concentrated. Another potential tailwind is continued migration into the Sun Belt, where the company already has a broad footprint. Company-led community expansion and lot pipeline execution also matter, because they determine how well Meritage can translate market demand into closings over the next several years.
Recent company updates have continued to emphasize community count, spec inventory availability, and affordability-focused product positioning. Those are meaningful because they show management is adapting to current demand conditions rather than waiting for the market to normalize on its own.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


