Stock Analysis · Melco Resorts & Entertainment Ltd (MLCO)
Overview
Melco Resorts & Entertainment Ltd is a casino and hospitality company focused on integrated resorts in Asia and Europe. Its properties combine gaming floors with hotel rooms, restaurants, retail, entertainment, and convention space. The group is best known for its exposure to Macau, one of the world’s largest legal gambling markets, and it also operates in Manila and Cyprus.
The business is driven primarily by casino activity, with a smaller but still meaningful contribution from hotels, food and beverage, entertainment, and other resort services. Based on the company’s recent annual disclosures, revenue is heavily concentrated in Macau, while City of Dreams Manila and City of Dreams Mediterranean and other Cyprus operations provide additional diversification.
Main revenue sources can be summarized as follows:
- Gaming revenue: approximately 85% to 90% of total revenue. This includes baccarat and other table games, mass-market play, VIP-related activity where applicable, and slot machines/electronic gaming.
- Non-gaming revenue: approximately 10% to 15% of total revenue. This includes hotel rooms, food and beverage, retail leases, entertainment, and other resort services.
- By geography, Macau: approximately 75% to 85% of total revenue. The largest contributors are City of Dreams, Studio City, and Altira Macau, with Mocha Clubs adding machine gaming exposure.
- By geography, Manila: approximately 10% to 15% of total revenue through City of Dreams Manila, an integrated resort serving both local and tourist demand.
- By geography, Cyprus: approximately 5% to 10% of total revenue through City of Dreams Mediterranean and related satellite casinos.
That structure makes Melco a fairly focused company rather than a globally diversified gaming giant. The upside is that a recovery in Macau can have a strong effect on earnings and cash flow. The downside is that weakness in Macau can dominate the entire group’s results.
The flow of the business over recent years shows a sharp rebound after the pandemic period: revenue climbed from roughly $1.3 billion in 2022 to more than $5.1 billion in 2025, while operating income moved from heavy losses to solid profitability. One important detail is that interest expense has remained very large throughout the recovery, which means financing costs still absorb a meaningful share of the operating improvement.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Resorts & Casinos | |
| Market Cap ⓘ | $1.91B | |
| Beta ⓘ | 0.58 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.49 | 17.10 |
| FCF Yield ⓘ | 33.43% | 8.53% |
| EBIT / EV ⓘ | 9.82% | 6.46% |
| PEG ⓘ | 0.38 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -5.70% | 5.75% |
| RPS Growth (5Y CAGR) ⓘ | 32.28% | 9.14% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.21% |
| Margin Growth (5Y Trend) ⓘ | 42.00% | -0.23% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.56% | 12.61% |
| ROIC (5Y Median) ⓘ | 3.09% | 10.72% |
| Net Debt / EBIT (Latest) ⓘ | 9.92 | 2.10 |
| Net Debt / EBIT (5Y Median) ⓘ | 13.13 | 2.32 |
| Operating Margin (Latest) ⓘ | 12.33% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 7.22% | 9.64% |
| Debt to Equity (Latest) ⓘ | -446.89% | 75.78% |
| Profit Margin (Latest) ⓘ | 4.50% | 5.33% |
| Free Cash Flow (Latest) ⓘ | $636.89M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -50.54% | +14.53% |
| 12M Return (excl. last month) ⓘ | -36.41% | +3.08% |
| 6M Return ⓘ | -8.18% | +0.55% |
| Price vs. 200-Day MA ⓘ | -16.43% | -0.54% |
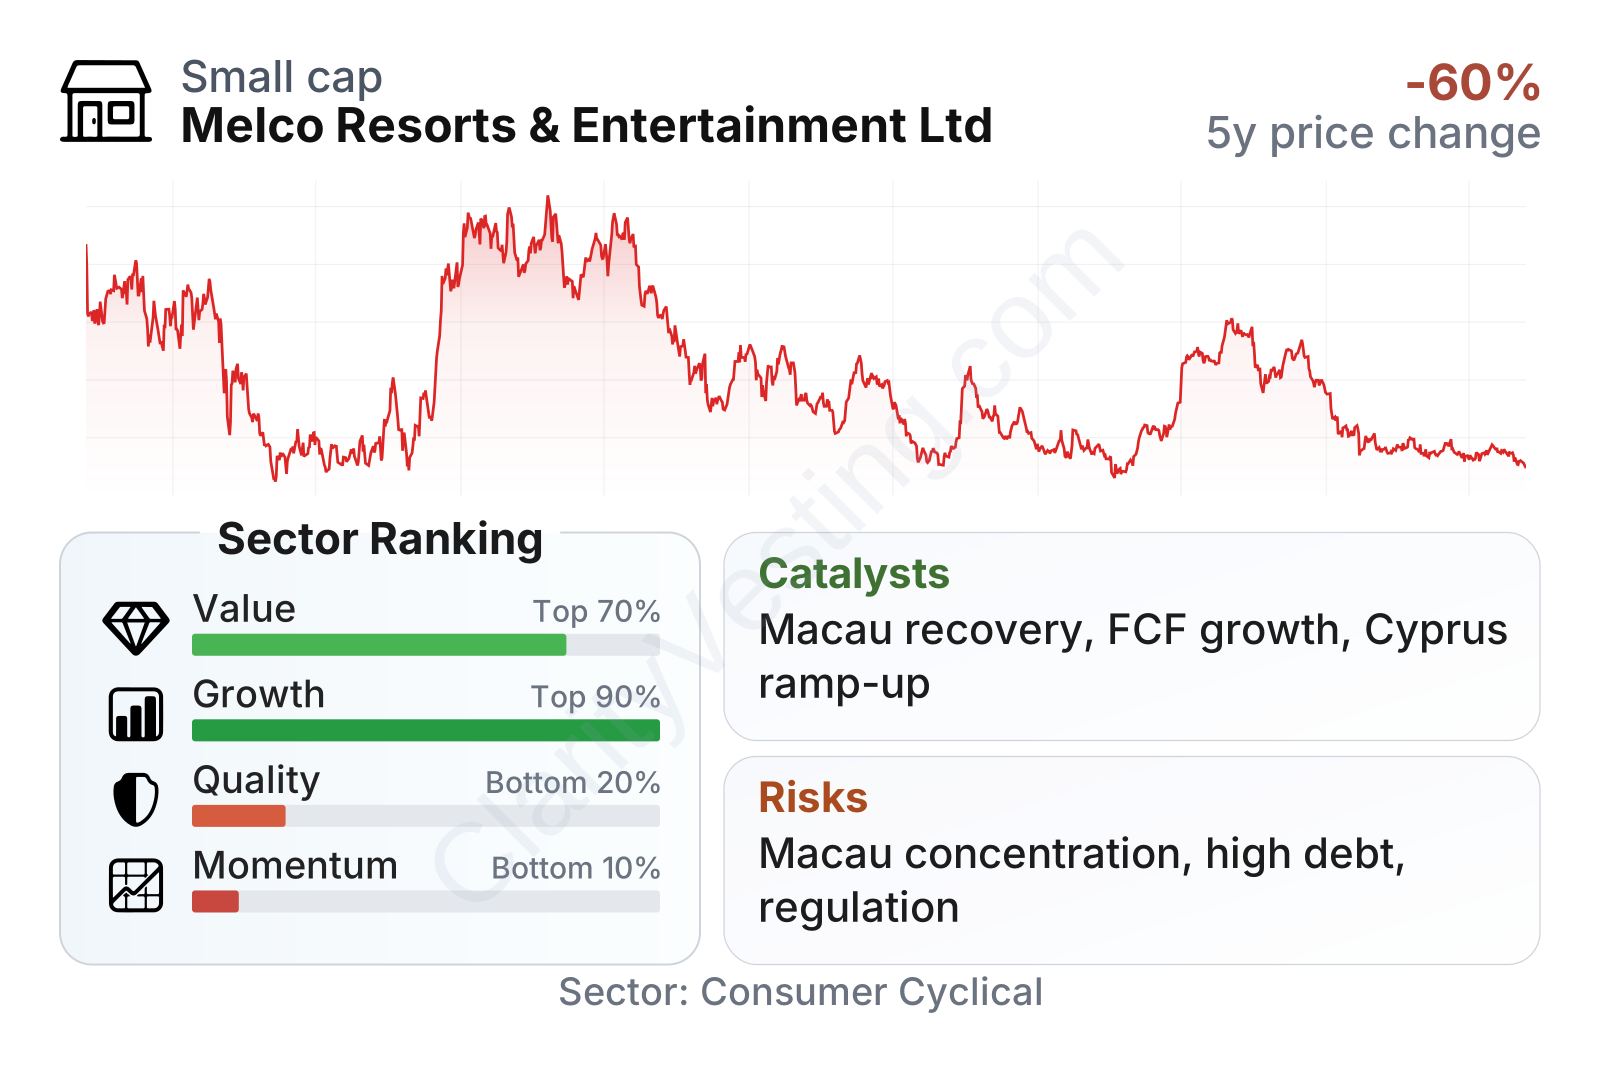
Melco looks inexpensive on several headline valuation measures, with earnings and cash-flow multiples below the sector median. Growth metrics also stand out over a multiyear period, reflecting the rebound from depressed pandemic-era activity. The weak area is balance-sheet quality: leverage remains elevated, returns on invested capital have lagged stronger peers over time, and share-price momentum has been poor despite recent operational improvement.
Growth
Melco operates in a sector that can still grow over the long run, but it is not a simple straight-line growth business. Casino resorts benefit from rising tourism, premium travel spending, and entertainment demand, especially in destination markets with limited licenses. Macau remains the key long-term driver because it has a unique scale in Asian gaming, and Melco has meaningful assets there with established brands and large capacity.
The company’s strategy is logical for this industry. It focuses on integrated resorts that go beyond gaming alone, which is important because regulators in Macau increasingly emphasize tourism diversification, non-gaming attractions, and broader visitor appeal. Melco has also continued to invest in property upgrades, premium customer experiences, hotel capacity, entertainment offerings, and operating efficiency. That approach fits the direction of the market: attracting more mass-market and premium-mass customers rather than relying only on older VIP patterns.
Recent revenue growth is no longer in the explosive rebound phase seen after reopening, but the business has still been expanding at a healthy pace. The latest year-over-year growth rate is in the low double digits, after a much stronger post-reopening surge in 2023 and slower normalization during 2024 and 2025. In other words, the recovery phase has matured, and Melco is now being judged more on sustainable earnings power than on reopening momentum.
Cash generation is one of the most encouraging parts of the current picture. Free cash flow has turned strongly positive, and the latest trailing figure is substantial relative to the company’s size. That matters because cash flow gives Melco more room to manage debt, fund maintenance and selective improvements, and absorb volatility in demand.
Several catalysts could support future expansion. Continued improvement in Macau visitation, better spending per visitor, stronger premium-mass demand, and further ramp-up from newer or upgraded resort attractions would all help. Cyprus also offers a smaller but potentially valuable growth leg, since City of Dreams Mediterranean is a newer asset that can still build brand recognition and operating scale. In addition, if financing conditions improve over time, more of Melco’s operating gains could flow through to net income.
Recent company updates have continued to highlight property enhancements, entertainment programming, and efforts to capture premium demand in Macau. None of that changes the fact that the business remains cyclical, but it does suggest management is positioning the portfolio for a market that rewards destination quality and customer experience rather than pure gaming capacity alone.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


