Stock Analysis · Light & Wonder Inc (LNWO)
Overview
Light & Wonder is a gambling technology company that supplies products and content to casinos and digital gaming operators. Its business spans physical casino machines, casino systems, table game products, and online game content. In simple terms, the company makes money by helping casinos run slot floors, by selling or leasing gaming machines and related systems, and by distributing games through digital channels.
The business is organized around three main revenue engines. Based on recent annual reporting, the mix is roughly as follows:
- Gaming: about 66% to 70% — the largest segment. This includes slot machines sold to casinos, participation and leased machines that generate recurring fees, gaming systems software, hardware, maintenance, and table products.
- SciPlay: about 20% to 23% — social casino and mobile games where users play free-to-play titles and spend on in-game purchases.
- iGaming: about 10% to 12% — real-money digital casino content and platforms supplied to regulated online operators.
This structure matters because it gives Light & Wonder a blend of recurring cash flow and growth exposure. The casino equipment business is more mature and tied to operator spending, while social gaming and iGaming give the company access to faster-moving digital markets. Over the past several years, revenue has expanded materially, and operating income has improved even as the company kept investing in research and development.
One notable pattern is that gross profit has climbed steadily from a little over $1.5 billion in 2021 to just above $2.0 billion by 2025, while interest expense has trended lower than earlier post-restructuring levels. That points to a business that has become more efficient and financially sturdier than it was a few years ago, even if net income still moves around because of accounting items and financing costs.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Gambling | |
| Market Cap ⓘ | $6.52B | |
| Beta ⓘ | 0.39 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 25.63 | 17.10 |
| FCF Yield ⓘ | 8.50% | 8.53% |
| EBIT / EV ⓘ | 5.84% | 6.46% |
| PEG ⓘ | 0.53 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 2.30% | 5.75% |
| RPS Growth (5Y CAGR) ⓘ | 15.42% | 9.14% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.21% |
| Margin Growth (5Y Trend) ⓘ | 11.94% | -0.23% |
| FCF Growth (5Y CAGR) ⓘ | -1.49% | 4.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 10.08% | 12.61% |
| ROIC (5Y Median) ⓘ | N/A | 10.72% |
| Net Debt / EBIT (Latest) ⓘ | 7.36 | 2.10 |
| Net Debt / EBIT (5Y Median) ⓘ | 7.47 | 2.32 |
| Operating Margin (Latest) ⓘ | 20.33% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 17.71% | 9.64% |
| Debt to Equity (Latest) ⓘ | 1707.62% | 75.78% |
| Profit Margin (Latest) ⓘ | 8.09% | 5.33% |
| Free Cash Flow (Latest) ⓘ | $554.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +13.18% | +14.53% |
| 12M Return (excl. last month) ⓘ | +3.18% | +3.08% |
| 6M Return ⓘ | +2.89% | +0.55% |
| Price vs. 200-Day MA ⓘ | -3.40% | -0.54% |
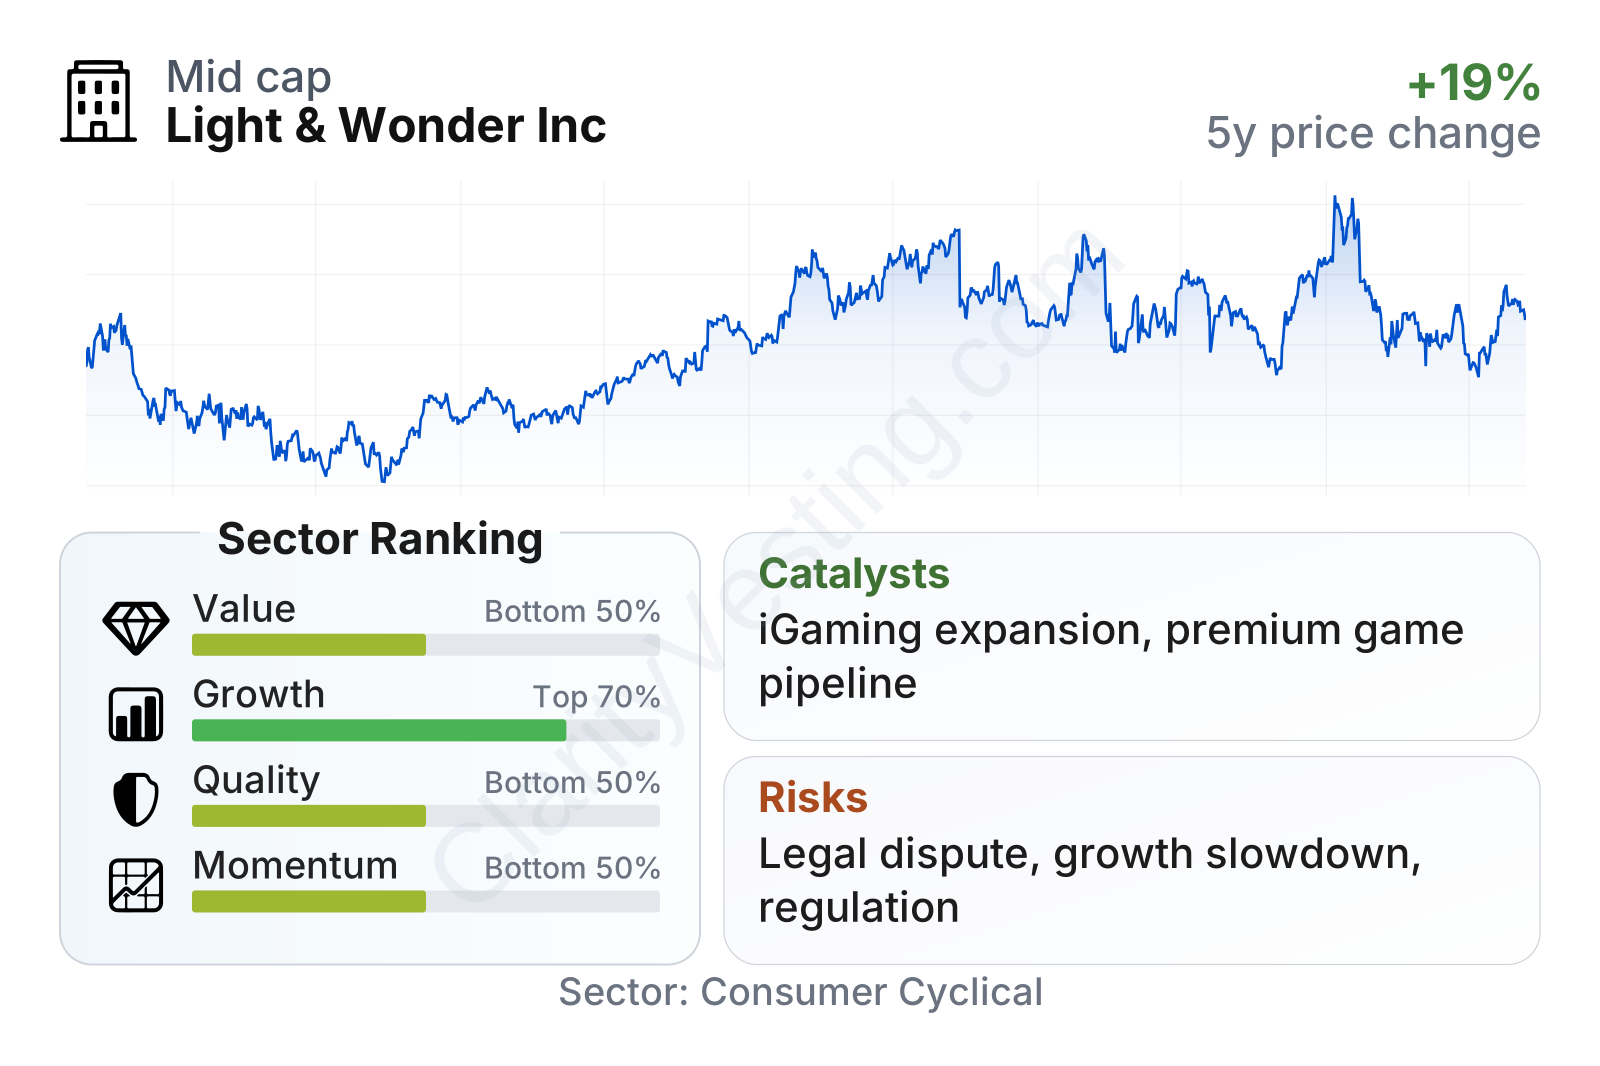
Light & Wonder is a mid-sized company by public market standards, with a market value in the several-billion-dollar range. The stock has been volatile over the last few years, rising strongly into 2024 and then giving back part of those gains more recently. In the factor snapshot, growth and quality are better than many sector peers, while value looks less attractive because the earnings multiple sits above the sector median. Momentum is currently weak, reflecting the stock’s softer recent trading. On the positive side, the company combines a solid operating margin, profit margin above the sector median, and unusually low net debt relative to earnings on a trailing basis.
Growth
The company operates in parts of the gambling industry that still have room to expand, especially digital casino content and mobile-based gaming. Land-based casino equipment is not a hypergrowth business, but replacement demand, premium game cabinets, systems upgrades, and international placements can still support steady expansion. The more interesting long-term angle is that Light & Wonder is not dependent on just one format: it has exposure to casino floors, mobile social gaming, and regulated online casino content.
The strategy is coherent. Management has spent the last few years simplifying the business, focusing on gaming, social casino, and iGaming rather than maintaining a broader and less connected portfolio. That sharper focus can make capital allocation more effective, especially when paired with game development and cross-platform content reuse. A title that performs well on casino floors can sometimes be adapted to mobile or online channels, which can improve returns on content investment.
Revenue growth has clearly slowed from the very strong post-recovery phase. The business was regularly posting double-digit year-over-year gains through much of 2023 and 2024, but more recent quarterly growth has moved down toward the low-single-digit range, with one quarter dipping slightly negative before growth resumed. That does not necessarily break the long-term case, but it does show that the easiest phase of expansion is likely over and that future gains will need to come more from execution than from a broad rebound in demand.
Cash generation remains an important support. Free cash flow has been positive again after a weak period in 2023, and the trailing level is now comfortably in the hundreds of millions of dollars. That gives the company flexibility for debt management, product investment, acquisitions, or shareholder returns. For a company in gaming technology, that matters because scale and fresh content are critical, and sustained cash flow helps fund both.
A meaningful catalyst is the continued growth of regulated online casino markets in North America and other jurisdictions. Every time a new market opens, operators need content, aggregation, and platform support. Light & Wonder is already established in this niche, which gives it a way to grow without having to build a new business from scratch. Another catalyst is ongoing demand for premium leased and participation slot machines, which tend to produce recurring, higher-quality revenue than one-time hardware sales.
Recent company updates have also continued to emphasize game pipeline strength, product launches, and the expansion of digital distribution. None of that guarantees a major acceleration, but it fits a sensible long-term approach: stronger franchises, broader content reach, and better monetization across channels.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


