Stock Analysis · Lumentum Holdings Inc (LITE)
Overview
Lumentum Holdings Inc. is a photonics company. In simple terms, it makes advanced optical and laser components that help move, sense, and process light. Those products are used in telecom networks, cloud data centers, industrial applications, consumer electronics, and defense-related markets. The business sits at the intersection of connectivity and high-performance sensing, which makes it relevant to several long-term technology themes.
The company reports its business mainly through two operating segments. Based on the latest annual reporting structure and recent filings, revenue is primarily generated from:
- Cloud & Networking: approximately 60% to 65% of revenue. This includes optical components and modules used in cloud data centers, AI-related network upgrades, telecom transport, and other high-speed communications infrastructure.
- Industrial Tech: approximately 35% to 40% of revenue. This includes lasers and photonic products used in industrial manufacturing, 3D sensing, semiconductor-related applications, and defense or scientific uses.
That revenue mix matters because it shows Lumentum is no longer only tied to traditional telecom spending. A larger share now depends on cloud and data center demand, where bandwidth needs are rising quickly as AI workloads expand. At the same time, the industrial side adds diversification, although it can be cyclical and sensitive to manufacturing conditions.
The broader financial flow also shows a business that has experienced sharp swings. Revenue and gross profit recovered strongly in the latest period, while research and development spending remained substantial. That is consistent with a company trying to protect its technology position even during uneven profitability.
The recent picture suggests a powerful rebound in revenue and gross profit, but also unusually large losses at the bottom line. That combination often points to one-time charges or accounting items rather than a clean read on everyday operating performance, so headline earnings need to be treated carefully.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Communication Equipment | |
| Market Cap ⓘ | $83.93B | |
| Beta ⓘ | 1.54 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 144.99 | 29.51 |
| FCF Yield ⓘ | 0.66% | 4.25% |
| EBIT / EV ⓘ | -8.63% | 2.85% |
| PEG ⓘ | 0.63 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 109.30% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | 15.02% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | 6.49% | -11.88% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | -4.98% | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -107.73% | 9.44% |
| ROIC (5Y Median) ⓘ | -3.26% | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | 2.34 | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.44 |
| Operating Margin (Latest) ⓘ | -237.26% | 9.58% |
| Operating Margin (5Y Median) ⓘ | -9.11% | 8.25% |
| Debt to Equity (Latest) ⓘ | 35.99% | 33.33% |
| Profit Margin (Latest) ⓘ | -230.10% | 7.14% |
| Free Cash Flow (Latest) ⓘ | $550.50M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +1838.18% | +45.48% |
| 12M Return (excl. last month) ⓘ | +679.27% | +23.48% |
| 6M Return ⓘ | +50.47% | +20.93% |
| Price vs. 200-Day MA ⓘ | +32.56% | +7.43% |
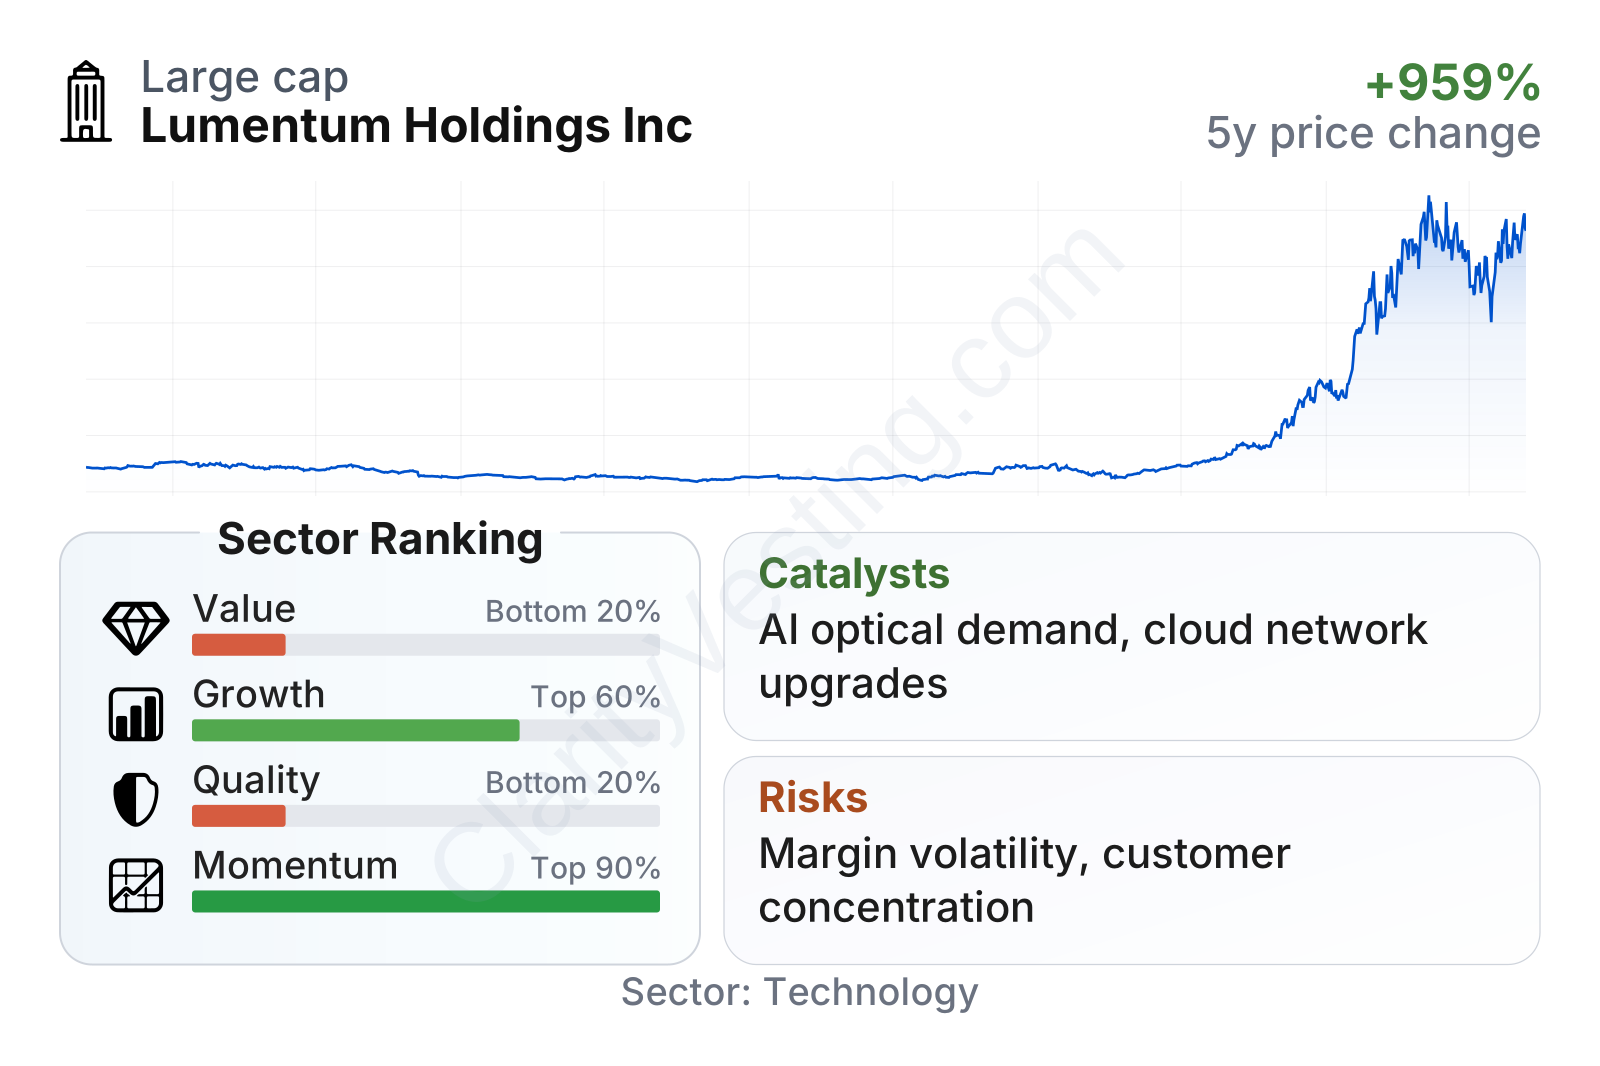
Lumentum’s profile is mixed. Growth and share-price momentum rank well versus much of the technology sector, but value and quality metrics are weak. Revenue growth is far above the sector median, yet profitability, returns on capital, and cash flow yield remain less impressive. The stock has also been much more volatile than the average company, which fits a business exposed to fast-changing demand cycles and major shifts in market expectations.
The share-price history shows how dramatic sentiment changes have been. After a long weak period, the stock moved sharply higher, which means the market is already pricing in a large improvement in the business outlook. That makes execution more important from here.
Growth
Lumentum operates in markets with attractive long-term demand drivers. Data traffic continues to rise, cloud infrastructure keeps expanding, and AI clusters require more optical interconnects to move data quickly between servers, racks, and facilities. Those trends support demand for the kind of high-speed optical components Lumentum sells. This is a real growth area rather than a mature, low-change corner of technology.
The company’s strategy also makes sense on paper. It focuses on photonic components and modules where performance, reliability, and manufacturing know-how matter. That can create room for pricing power and deeper customer relationships, especially in cloud networking where product qualification can be long and technical switching costs can be meaningful.
The recent revenue trend is especially important. After a difficult downturn, growth turned positive and then accelerated to more than 100% year over year in the latest reading, far above the sector median. Part of that reflects recovery from a weak base, but the magnitude still suggests that cloud-related demand and product mix have improved materially.
Cash generation has also recovered. Free cash flow was negative during the downturn, then turned clearly positive again in the latest trailing period. That is a healthier sign than revenue growth alone because it suggests the rebound is starting to translate into real financial flexibility, even if consistency still needs to be proven.
A notable recent catalyst is the company’s exposure to AI-network infrastructure. Lumentum has highlighted demand tied to high-speed optical connectivity, and that theme has become much more important across the industry as AI systems require denser and faster links. In addition, the company completed the acquisition of NeoPhotonics in recent years, which expanded its reach in high-speed optical networking. If integration benefits continue to show up in product depth and customer access, that can support future growth beyond a simple cyclical rebound.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


