Stock Analysis · Kopin Corporation (KOPN)
Overview
Kopin Corporation is a small technology company that designs and supplies specialized display components and optical systems used in defense, industrial, medical, and consumer applications. Its core expertise is in microdisplays, display backplanes, and optics that allow digital images to be shown very close to the eye in compact devices such as helmet-mounted displays, thermal weapon sights, pilot systems, and augmented reality products.
The business is centered on components rather than mass-market finished devices. That matters because Kopin is usually selling high-value parts and subsystems to larger equipment makers, especially in defense and enterprise markets. In recent years, management has increasingly emphasized military and defense programs, where product cycles can be long but contracts can also be more durable once a design is selected.
Based on the company’s recent filings and disclosures, revenue mainly comes from product sales and related engineering activity tied to microdisplays and optical solutions. Public filings do not always break revenue into a clean percentage split by end market every quarter, but the company’s business can be understood through the following main sources:
- Display products and components: microdisplays, OLED and LCD-based near-eye displays, and display backplanes used in military vision systems, thermal imaging devices, and wearable electronics. This appears to be the largest revenue source.
- Optical systems and modules: optics, eyepieces, and integrated subsystems used with head-mounted or weapon-mounted display solutions. This has become increasingly important as defense products move toward more complete assemblies.
- Engineering services and program-related development: customer-funded work tied to product customization, prototyping, and defense program support. This is typically smaller than product revenue but can help establish future production awards.
- Application exposure by end market: defense is the company’s most strategically important end market, followed by industrial and medical uses, with consumer wearables representing a smaller and less predictable opportunity.
The financial flow over the last several years shows a business that has struggled with uneven gross profit and operating losses, but it also shows a sharp improvement in 2025 when the company briefly returned to positive operating income and net income. That improvement is important, although it has not yet fully translated into sustained cash generation.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Sep 12, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Electronic Components | |
| Market Cap ⓘ | $1.02B | |
| Beta ⓘ | 3.55 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 137.50 | 29.51 |
| FCF Yield ⓘ | -1.80% | 4.25% |
| EBIT / EV ⓘ | N/A | 2.85% |
| PEG ⓘ | 8.75 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 50.60% | 15.40% |
| RPS Growth (5Y CAGR) ⓘ | -19.14% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | -29.53% | -11.88% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 9.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.44% |
| ROIC (5Y Median) ⓘ | -46.78% | 8.30% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.54 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.44 |
| Operating Margin (Latest) ⓘ | N/A | 9.58% |
| Operating Margin (5Y Median) ⓘ | -36.37% | 8.25% |
| Debt to Equity (Latest) ⓘ | 1.68% | 33.33% |
| Profit Margin (Latest) ⓘ | 18.26% | 7.14% |
| Free Cash Flow (Latest) ⓘ | -$18.42M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +245.91% | +45.48% |
| 12M Return (excl. last month) ⓘ | +151.79% | +23.48% |
| 6M Return ⓘ | +155.81% | +20.93% |
| Price vs. 200-Day MA ⓘ | +65.51% | +7.43% |
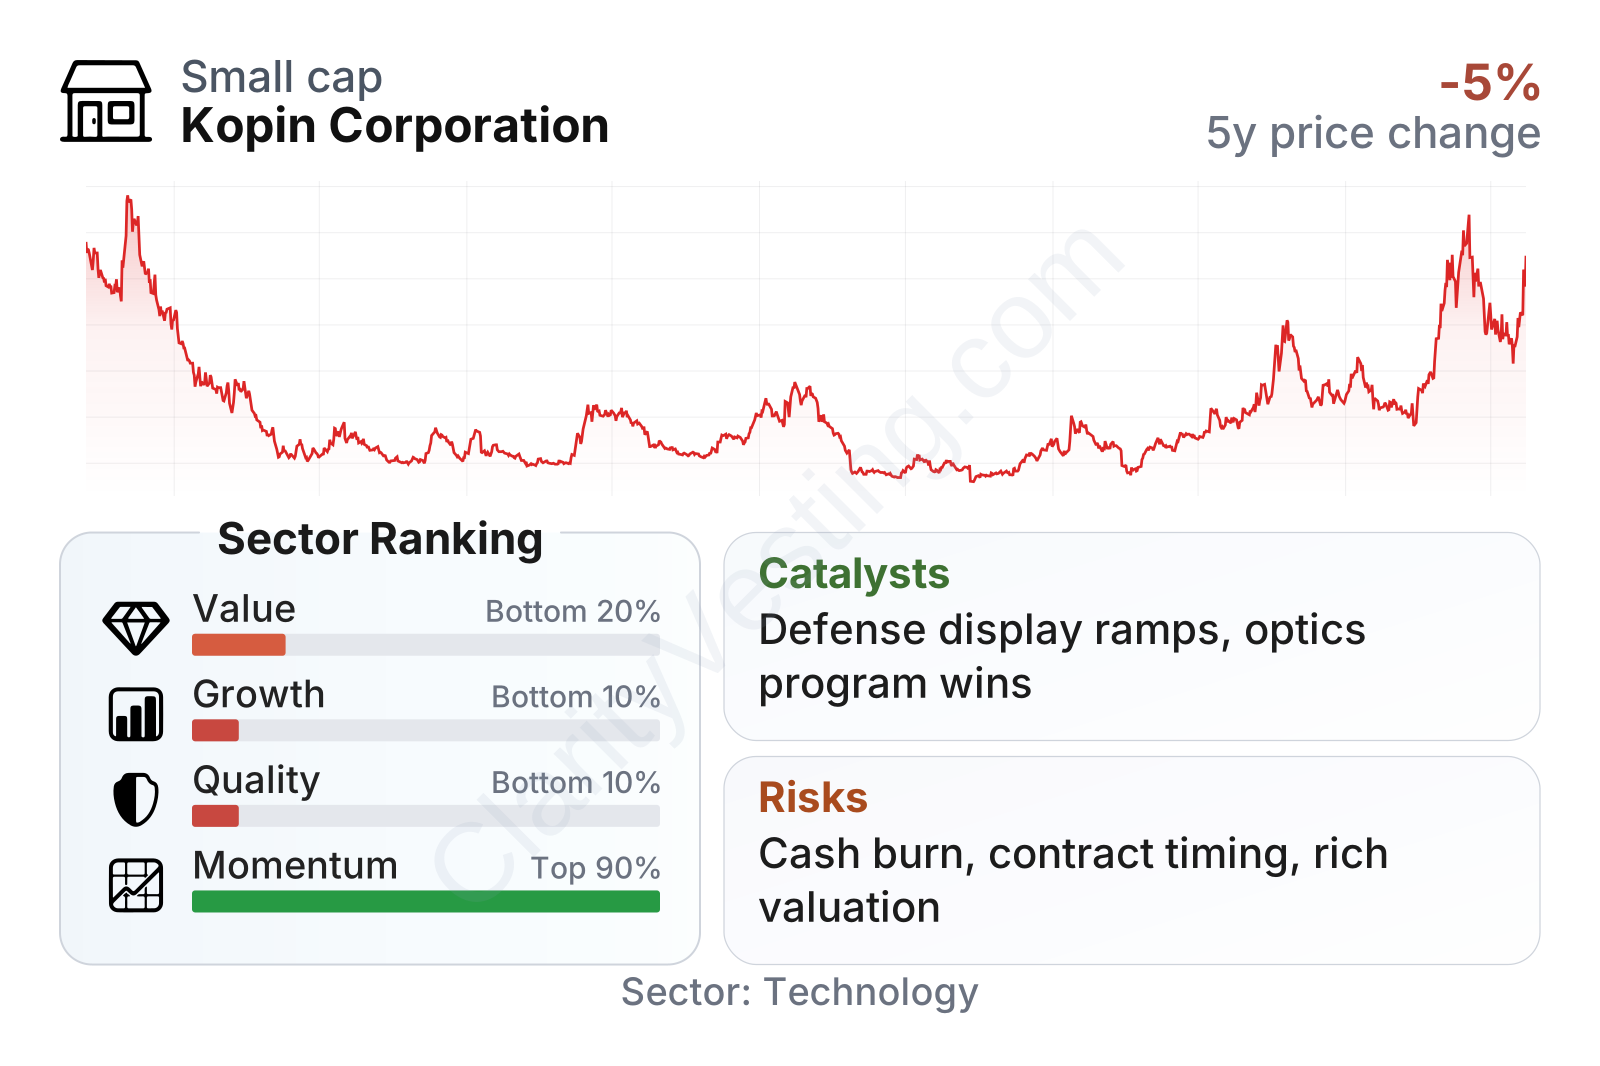
Kopin is a small-cap company with unusually high share-price volatility, reflected in a beta above 3. The factor summary is mixed: momentum is very strong, but value, growth quality, and business quality rank near the bottom of the broader technology sector. In plain terms, the stock has moved up sharply, yet the underlying financial profile still looks fragile compared with most peers.
The recent margin picture is better than the long-term record suggests. Profit margin has turned positive and is now above the sector median, but free cash flow remains negative and the longer five-year track record for revenue per share, earnings, and returns on capital is still weak. That combination usually signals a company in transition rather than one with already proven financial strength.
Growth
Kopin operates in markets that have real structural growth potential. Defense modernization is increasing demand for advanced soldier vision systems, pilot displays, thermal sights, and compact optical modules. At the same time, the broader near-eye display market continues to benefit from interest in augmented reality, wearable computing, and specialized industrial visualization tools. These are growing fields, although not all parts of them are growing at the same pace or with the same reliability.
The company’s strategy makes sense on paper because it is focusing on applications where performance, ruggedness, weight, power efficiency, and optical quality matter more than low-cost consumer scale. That gives Kopin a better chance to compete on engineering depth instead of price alone. Defense programs are especially relevant here because once a supplier is designed into a system, replacement can be difficult and qualification barriers are meaningful.
Recent revenue trends show how uneven that growth path has been. After periods of contraction, year-over-year revenue growth accelerated sharply in the latest period to roughly 51%, far above the sector median. That is encouraging and suggests some program wins or delivery timing benefits are starting to come through. Still, the five-year trend remains weak, which means a few strong quarters are not enough by themselves to prove a lasting growth engine.
Cash generation is the part that still needs work. Even with the return to accounting profitability, trailing free cash flow has stayed negative at roughly the mid-teen millions of dollars below zero. For a company trying to scale through specialized technology programs, that means growth is present, but self-funded growth is not yet firmly established.
As for catalysts, the most important ones are tied to defense adoption and program expansion. Company updates in recent periods have highlighted progress in military displays, thermal imaging, and optical systems, areas that can materially change revenue if production orders broaden. Another meaningful catalyst is the industry shift toward higher-performance near-eye displays in professional and mission-critical use cases, where Kopin’s niche technology has a clearer role than in mass consumer electronics.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


