Stock Analysis · Genius Sports Ltd (GENI)
Overview
Genius Sports Ltd is a sports technology company that sits in the middle of the global sports ecosystem. It works with sports leagues, federations, sportsbooks, media companies, and brands. Its core role is to collect official sports data, distribute that data in real time, help betting operators manage trading and risk, and support fan engagement through advertising and digital products.
The business is built around long-term rights agreements with sports organizations. Those agreements give Genius Sports access to official live data and, in some cases, streaming and advertising inventory. The company then monetizes those rights by selling data feeds, betting technology, media services, and targeted advertising products to customers around the world.
Based on recent annual reporting, Genius Sports generates revenue from three main operating segments:
- Betting Technology, Content & Services: approximately 70% to 75% of revenue. This is the largest business and includes official sports data, live trading services, pricing and risk tools, and related technology sold to sportsbooks and betting operators.
- Media Technology, Content & Services: approximately 20% to 25% of revenue. This segment includes programmatic advertising, fan activation campaigns, and digital marketing products that help sportsbooks and sports organizations acquire and engage users.
- Sports Technology & Services: approximately 5% to 10% of revenue. This smaller unit provides technology for sports leagues and federations, including data capture, video tools, and performance-related software.
That revenue mix matters because it shows Genius Sports is not simply a software vendor. It is a rights-based infrastructure provider. The company’s position depends on securing official data relationships and turning them into recurring commercial revenue across betting, media, and technology services.
The financial flow over the last several years shows a business that has scaled rapidly. Revenue has moved from roughly $260 million in 2021 to about $670 million in 2025, while gross profit has improved materially from negative territory to clearly positive. The weaker point is operating cost discipline: selling, general and administrative expense rose sharply in 2025, which helps explain why strong top-line growth has not yet translated into consistent bottom-line profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Communication Services | |
| Industry | Internet Content & Information | |
| Market Cap ⓘ | $1.60B | |
| Beta ⓘ | 1.91 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 17.88 |
| FCF Yield ⓘ | -4.14% | 14.65% |
| Dividend Yield ⓘ | N/A | 2.79% |
| EBIT / EV ⓘ | -5.95% | 4.81% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 64.70% | 5.50% |
| RPS Growth (5Y CAGR) ⓘ | 10.84% | 4.60% |
| EPS Growth (5Y CAGR) ⓘ | -33.94% | -17.78% |
| Margin Growth (5Y Trend) ⓘ | N/A | 1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 6.01% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.09% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -11.85% | 8.61% |
| ROIC (5Y Median) ⓘ | -13.72% | 8.32% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.01 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.88 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.27 |
| Net Debt / Assets ⓘ | 31.49% | 18.77% |
| EBITDA / Interest ⓘ | N/A | 8.49 |
| Operating Margin (Latest) ⓘ | -17.35% | 15.56% |
| Operating Margin (5Y Median) ⓘ | -17.35% | 13.53% |
| Debt to Equity (Latest) ⓘ | 120.04% | 59.65% |
| Profit Margin (Latest) ⓘ | -22.99% | 8.78% |
| Free Cash Flow (Latest) ⓘ | -$66.44M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +19.16% | +44.29% |
| 12M Return (excl. last month) ⓘ | -44.52% | +2.52% |
| 6M Return ⓘ | +40.72% | +2.69% |
| Price vs. 200-Day MA ⓘ | -6.08% | +0.77% |
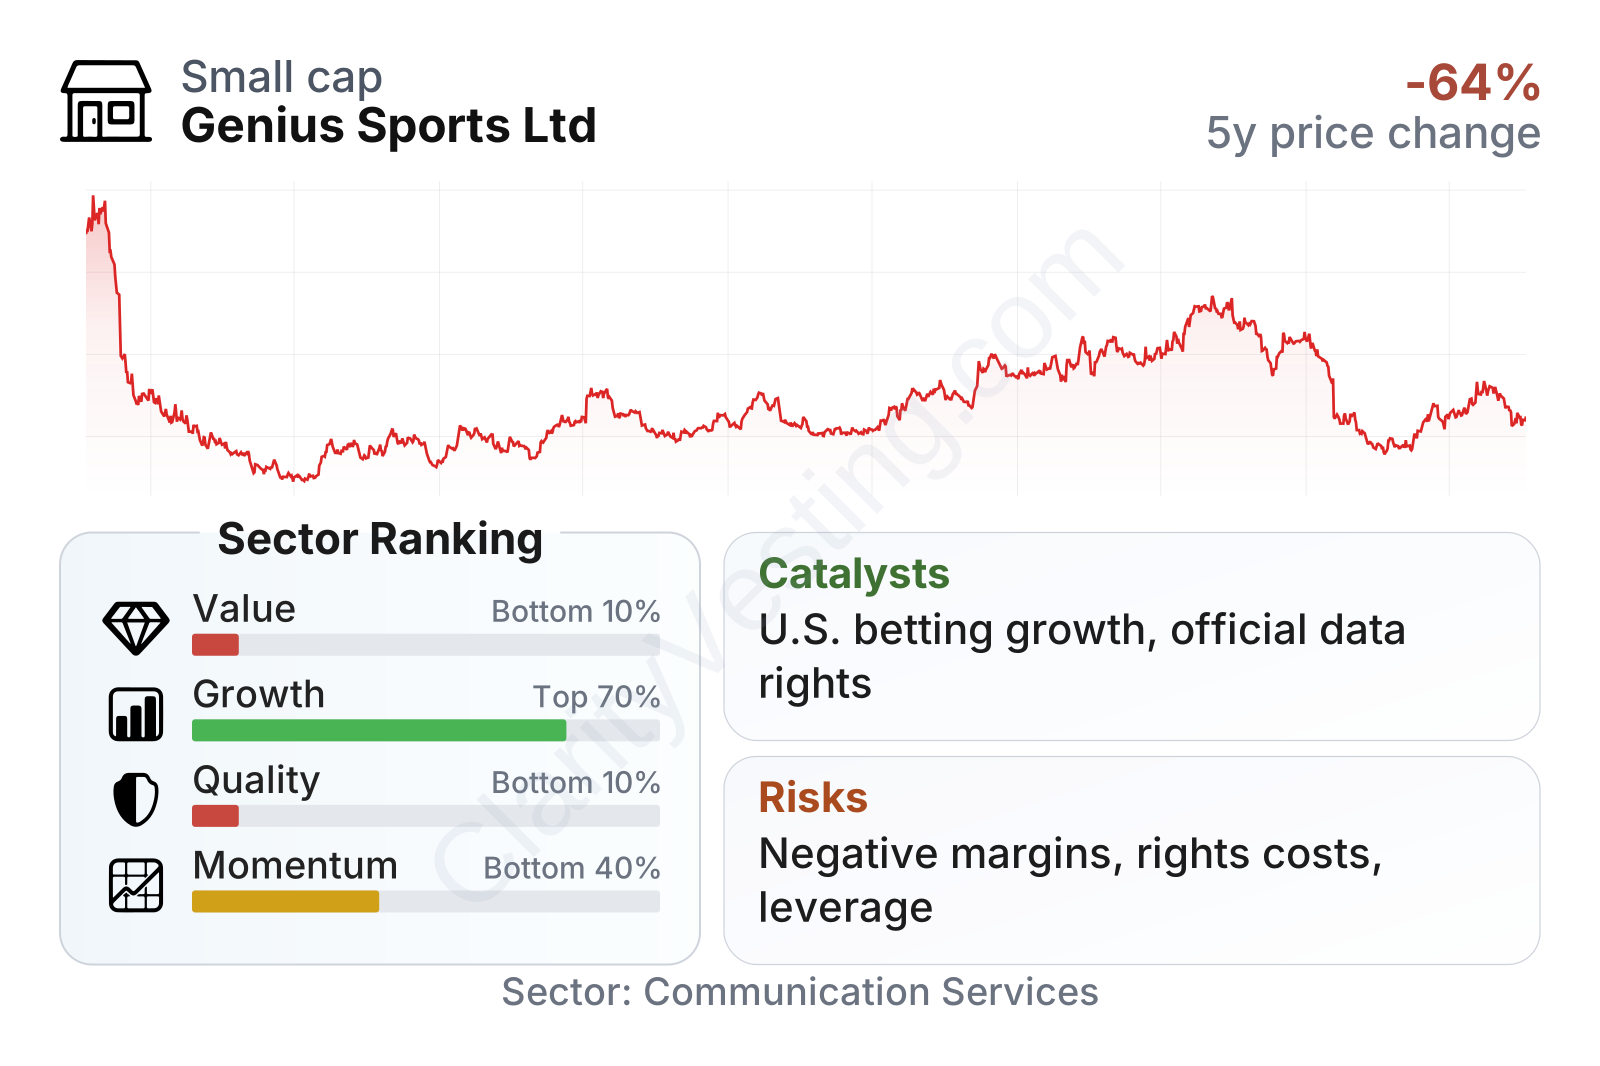
The market currently values Genius Sports as a mid-cap company, and the stock has been volatile, with a beta close to 1.9. In simple terms, that suggests the shares have tended to move more sharply than the broader market. The factor profile is mixed: growth stands above much of the sector, but value and quality rank near the bottom. That combination usually reflects a company with meaningful revenue momentum but weak current profitability and cash generation.
The latest comparison also highlights the core tension in the case. Revenue growth is far above the sector median, and five-year revenue-per-share expansion has also been strong. At the same time, return on invested capital, operating margin, and free cash flow remain notably weaker than typical sector levels. This is a company being judged more on future scale and strategic position than on present earnings power.
Growth
Genius Sports operates in a market that still has structural tailwinds. Sports betting continues to expand as more jurisdictions regulate online wagering, while leagues and media groups are placing greater value on official real-time data, integrity services, and digital fan monetization. That creates a favorable backdrop for a company that already has established relationships across these parts of the value chain.
The company’s strategy is logical for that environment. It aims to lock in exclusive or hard-to-replace rights, then sell multiple services on top of those rights. This can create a compounding effect: an official data agreement can support sportsbook products, in-play betting tools, streaming, and advertising campaigns at the same time. If execution is solid, each new major rights deal can open several revenue streams rather than just one.
Recent growth has been strong, although not perfectly smooth. After a slower period in 2023 and parts of 2024, year-over-year revenue growth accelerated again and reached roughly 65% in the most recent period shown, far above the sector median of about 6%. That kind of acceleration usually points to either large contract wins, stronger customer activity, or easier comparisons after a softer period. It also shows the business still has meaningful operating momentum when commercial conditions line up.
Cash generation has also improved. Trailing free cash flow was deeply negative in earlier periods, then moved close to break-even and briefly turned positive by early 2026 on the chart shown. That shift is important because it suggests the company may be approaching a stage where scale begins to support self-funding operations more effectively, even if reported earnings remain uneven.
A major catalyst remains the broader legalization and professionalization of sports betting, especially in the United States and other newly regulated markets. Genius Sports has also benefited from its role as an official data and technology partner to prominent leagues and organizations, which can strengthen switching costs and expand commercial reach. Recent company communications have continued to emphasize deeper product integration, AI-enabled automation, and cross-selling between betting and media customers, all of which fit the company’s platform strategy.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


